


- GHASALC Backs BoG Reforms but Warns Disorderly Transition Could Hit Depositors, Jobs and MSME Credit
Ghana’s savings and loans industry has backed the Bank of Ghana’s planned microfinance sector reforms but warned that a poorly sequenced transition could undermine depositor protection, threaten jobs and constrict credit to households and small businesses that remain heavily dependent on specialised financial institutions.
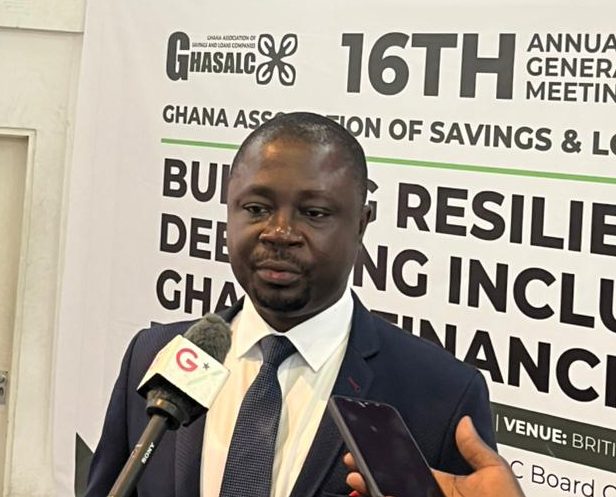
Tweneboah Kodua Boakye, Chief Executive Officer of the Ghana Association of Savings & Loans Companies, said the industry accepts the case for stronger regulation, improved governance and more resilient institutions, but insists that implementation must be realistic and sensitive to the economic role played by lower-tier lenders.
“Our position has been that good reforms must also produce sustainable institutions, build confidence, protect depositors and jobs,” Mr Boakye said at the Association’s 16th Annual General Meeting.
“We must ensure that the transition to the new framework is orderly, realistic and sensitive to the important role our institutions play in providing financial services to underserved segments of the economy.”
The warning is particularly significant because the scale of the sector means the reforms will affect far more than the institutions being regulated.
Deposits mobilised by savings and loans companies increased from GH¢6.10 billion in 2024 to GH¢8.54 billion in 2025, while credit extended to households and businesses rose from GH¢5.65 billion to GH¢7.24 billion over the same period.
That places billions of cedis in household savings and business financing within the scope of a regulatory transition that could reshape licensing, capital requirements, institutional identity and the number of firms operating in the market.
GHASALC’s argument is therefore not that regulation should be weakened. Rather, it is that stronger regulation must be implemented in a way that does not inadvertently destabilise otherwise viable institutions or reduce access to finance for customers who already have fewer options within the formal banking system.
“We support the destination; we must work together on the journey,” Mr Boakye said.
That formulation captures the central policy challenge confronting the Bank of Ghana.
Regulators need institutions with stronger balance sheets, better governance, improved risk management and greater capacity to absorb shocks. But the transition towards those objectives can itself create instability if capital thresholds, liquidity expectations or compliance costs rise faster than firms can restructure.
Savings and loans institutions typically operate closer to households, traders and micro, small and medium-sized enterprises than many traditional banks. Their customers may have limited collateral, less formal documentation or more volatile income patterns, making them less attractive to conventional lenders.
If reforms force significant consolidation or exit without adequate transition mechanisms, the country could end up with fewer but stronger institutions while simultaneously weakening the financing channels available to precisely the customers the sector was designed to serve.
The industry’s own numbers make that trade-off difficult to ignore. While deposits and lending expanded strongly in 2025, non-performing loans improved only marginally, declining from 15.00% to 14.00%.
It means the industry is entering the reform period with expanding balance sheets but persistent credit risk, alongside pressure from funding costs, liquidity management, technology expenditure and regulatory compliance.
For regulators, that strengthens the case for reform. For operators, it strengthens the argument for careful sequencing.
A system with weak institutions can endanger depositors, but a reform process that triggers unnecessary failures can also harm depositors, employees and borrowers.
The test is therefore whether the regulatory overhaul can distinguish between institutions that are fundamentally unsustainable and those that are viable but require time, capital or restructuring to meet a higher standard.
GHASALC has already begun repositioning itself for what it expects to be a substantially different industry architecture.
Mr Boakye said members had voted unanimously to restructure the Association under the emerging regulatory framework, with a new identity expected from January 2027.
The Association is moving towards becoming the Ghana Association of Microfinance Banks, although the final nomenclature will depend on the institutional category ultimately approved under the Bank of Ghana’s framework.
“It is about repositioning the Association to become the voice, knowledge hub, advocacy platform and strategic partner of the new industry,” the prepared address said.
The shift points to the likelihood that regulatory reform will alter not just capital thresholds, but also how institutions are classified, represented and positioned within Ghana’s broader financial system.
It may also change the competitive boundaries between savings and loans companies, microfinance institutions, finance houses and other specialised lenders.
Technology is emerging as the second major pressure point.
GHASALC, together with GHAMFIN and CUA, is pursuing an Inclusive Instant Payment System powered by Mojaloop, intended to promote interoperability and connect smaller financial institutions more effectively to Ghana’s wider payments ecosystem.
“The objective is not merely to introduce another payment platform. The broader vision is to promote interoperability and inclusive instant payments,” Mr Boakye said.
The significance of that initiative lies in the changing economics of financial services.
Banks, fintech companies and telecommunications operators are increasingly using digital onboarding, mobile applications, instant payments and data-driven credit tools to compete for customers who were once served mainly through physical branches or relationship banking.
For smaller institutions, the cost of developing comparable proprietary technology can be prohibitive.
Shared infrastructure therefore offers a potential route to remaining competitive without forcing each institution to finance an entire payments architecture independently.
GHASALC also sees Tazama, an open-source fraud-detection platform, as part of efforts to strengthen security and risk management as digital adoption deepens.
“We do not want our members to watch the digital financial revolution from the sidelines. We want them to be participants and beneficiaries,” Mr Boakye said.
That ambition is directly connected to the regulatory debate. A financially inclusive sector cannot remain technologically excluded. If smaller institutions are expected to meet stronger governance, compliance and reporting standards while simultaneously competing against highly digitalised banks and fintechs, they will need both capital and access to shared infrastructure.
Ghana’s small-business landscape is fragmented, with many firms operating with limited collateral, incomplete financial records or informal business structures.
Savings and loans institutions argue that their closer relationship with these businesses gives them an informational advantage, allowing them to assess borrowers in ways that go beyond standard bank documentation.
But that advantage alone will not be enough in the next phase of the industry.
Stronger balance sheets, better governance, improved risk assessment and collaboration will become increasingly important.
“The future will therefore belong to institutions that know how to collaborate,” Mr Boakye said.
That is likely to involve partnerships not only within the industry but also with payment providers, fintechs, technology companies, development partners and regulators.
GHASALC said it is already strengthening engagement with the Bank of Ghana, Ministry of Finance, GHAMFIN, GIZ, GhIPSS and other stakeholders as the sector prepares for the transition.
The experience of Ghana’s previous financial-sector clean-up adds weight to the industry’s caution.
Regulatory intervention can strengthen confidence and remove weak institutions, but the process can also carry social and economic costs when firms fail, jobs disappear and customers lose access to familiar channels of finance.
The coming microfinance reforms will therefore be judged on two fronts. The first is whether they create safer, better-capitalised and more professionally governed institutions.
The second is whether they preserve enough competition and distribution capacity to ensure that low-income households, small businesses and underserved communities are not pushed further away from formal finance.
“The reforms will challenge us. Technology will disrupt us. Competition will test us. But these same forces can make us better, stronger and more relevant,” Mr Boakye said.
“The question is not whether the industry will change. It will. The question is whether we will change with it. And my answer is: Yes, we will.”
For Ghana, the stakes are larger than the survival of individual savings and loans companies.
With GH¢8.54 billion in deposits and GH¢7.24 billion in credit already flowing through the sector, the microfinance reform programme is effectively a test of whether financial stability and financial inclusion can be strengthened at the same time. The Bank of Ghana’s challenge is to raise the bar without pulling away the ladder.

