


- First National Bank Turns Business Performance into Collateral for Unsecured SME Finance
First National Bank has reintroduced its system pre-approved unsecured business loan facility, seeking to replace the traditional demand for physical collateral with evidence drawn from a company’s financial behaviour, transactional history and capacity to manage credit.
The facility will provide qualifying businesses with access to loans and overdrafts for working capital and expansion without requiring the conventional property or other fixed assets that frequently prevent small and medium-sized enterprises from borrowing.
The proposition is simple but potentially consequential: a business that keeps accurate records, deposits its revenue consistently and operates its bank account responsibly can build a financial profile strong enough to support an automated lending decision.
For Ghanaian SMEs, this represents a different interpretation of collateral. Instead of asking only what asset a borrower can surrender when a loan fails, the bank is placing greater emphasis on whether the enterprise generates dependable cash flows and displays disciplined financial conduct.
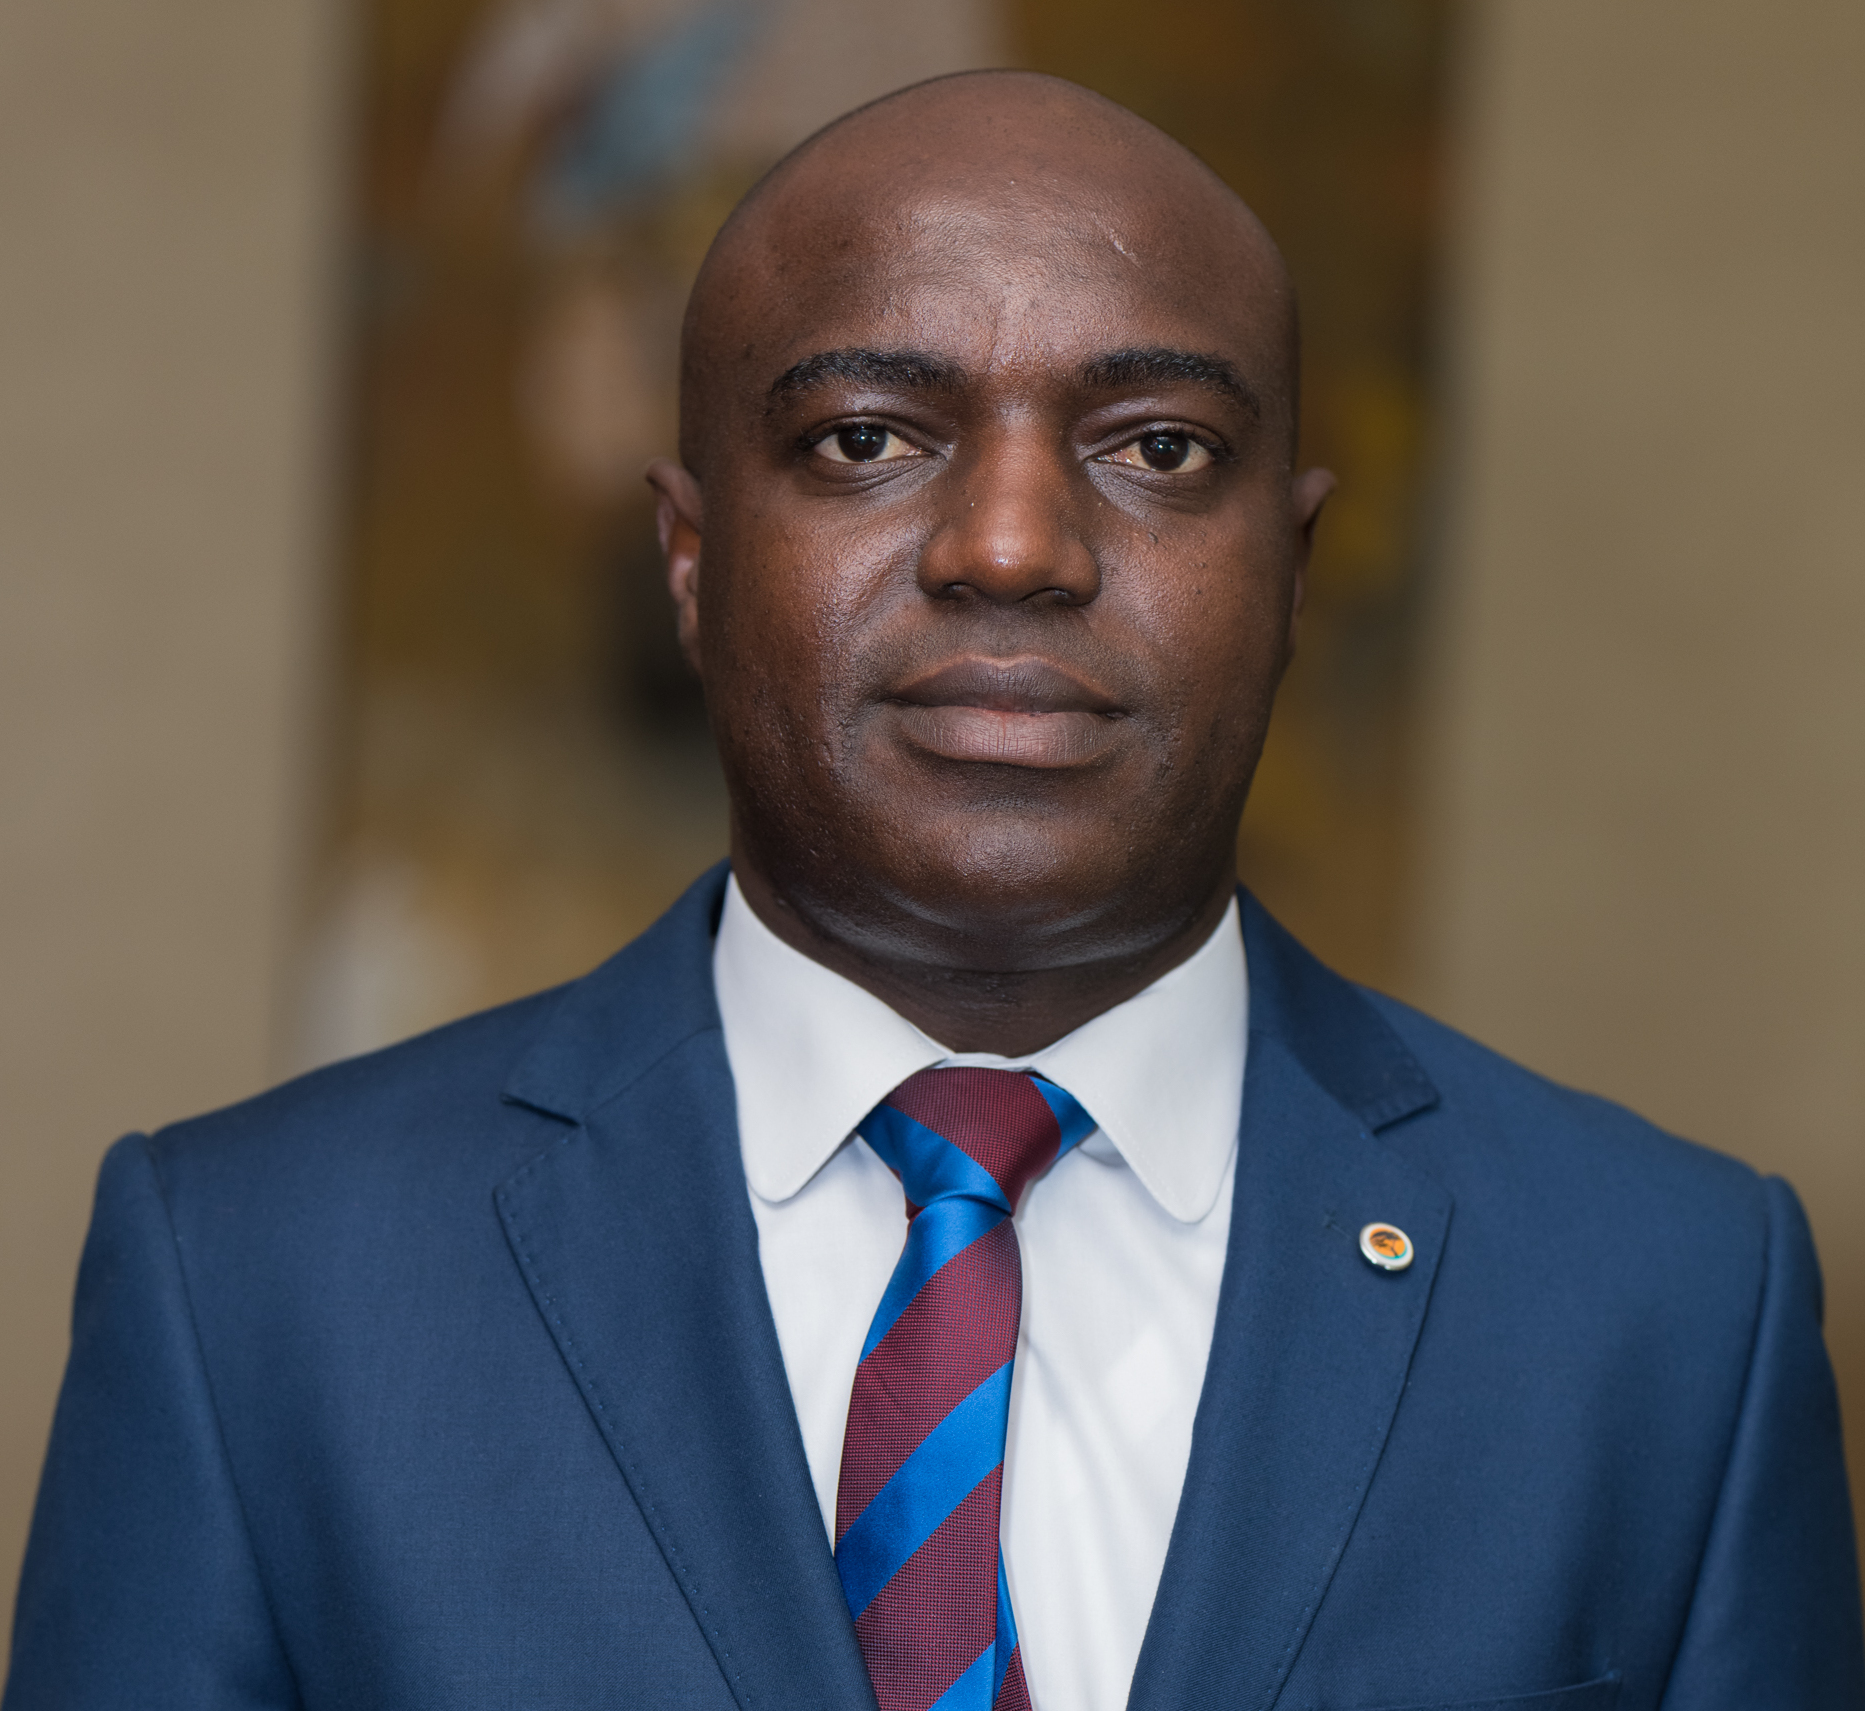
Mark Achiampong, Head of Commercial and Business Banking at First National Bank, said the initiative reflected the lender’s intention to make financing more accessible, affordable and convenient.
“We want to support entrepreneurs who are ready to grow, create jobs and invest in their businesses,” he said. “Maintaining accurate financial records and consistently banking revenue is more than an administrative responsibility. It is a powerful way for businesses to demonstrate their creditworthiness and unlock access to finance.”
The renewed facility addresses one of the structural contradictions facing smaller businesses. Many enterprises require capital to purchase inventory, accept larger orders, install equipment or enter new markets, but lack the land, buildings or other registered assets traditionally demanded by lenders.
Some businesses may be profitable and commercially viable while operating from rented premises or relying on movable equipment with limited collateral value. Their inability to provide property does not necessarily mean they cannot repay credit, but conventional underwriting can treat both conditions as though they were identical.
Cash-flow-based assessment offers a route around that problem. Transaction data can show how frequently revenue enters an account, whether balances fluctuate predictably, how a business meets existing obligations and whether its income can absorb repayments.
Mr Achiampong said the bank’s assessment model examines transactional behaviour, financial performance and the customer’s credit-risk profile before determining eligibility.
“With our pre-approved unsecured loan offering, a business’s financial track record does the work,” he said. “Businesses that maintain disciplined records, bank their revenue consistently and manage their accounts well build a track record that works in their favour.”
Pre-approval, however, should not be confused with automatic entitlement. Unsecured credit places greater risk on the lender because recovery cannot depend on a pledged asset. Eligibility, pricing and limits will consequently reflect the quality of the business’s records, account conduct and repayment capacity.
That makes the facility both an opportunity and a behavioural incentive. Enterprises that conduct most transactions in cash, mix business and personal spending or keep incomplete accounts may remain invisible to the assessment system even when their underlying operations are sound.
The product therefore reinforces a broader lesson for SMEs: financial record-keeping is not merely a requirement for taxation or annual reporting. It increasingly determines whether a business can obtain formal credit, negotiate favourable terms and demonstrate its strength to investors or commercial partners.
Businesses seeking to benefit will need to separate personal and enterprise finances, issue and retain invoices, reconcile bank accounts, record expenses and deposit revenue regularly. Consistency matters because occasional large deposits may provide less evidence of repayment capacity than a stable and explainable pattern of activity.
The bank must equally ensure that its system does not reproduce existing exclusions in a less visible form. Automated assessment can improve speed and consistency, but models depend on the information and assumptions used to construct them.
Young businesses, seasonal enterprises and firms operating in sectors with irregular payment cycles may appear riskier than they truly are. Women-owned enterprises and informal businesses could also be disadvantaged if historical banking data reflect longstanding inequalities in access to accounts, assets and formal contracts.
First National Bank will therefore need transparent eligibility rules, effective channels for customers to correct inaccurate information and a process for reviewing cases that do not fit standard patterns. Technology should support sound judgment rather than make lending decisions impossible to question.
Responsible lending is particularly important because easier access to credit can create its own risks. Working-capital loans should finance inventory, receivables and short-term operating needs capable of generating cash for repayment. Borrowing to cover persistent losses may merely postpone financial distress.
Overdrafts also require discipline. Their flexibility can help businesses manage timing differences between customer payments and supplier obligations, but continuous use can turn short-term support into expensive permanent debt.
The bank should provide borrowers with clear information on interest, fees, repayment schedules, penalties and the circumstances under which facilities may be reviewed or withdrawn. Speed should not come at the expense of informed consent.
The initiative could also deepen formalisation. Entrepreneurs who recognise that banking revenue and keeping records improve access to financing have a commercial reason to move transactions into traceable channels. That creates better information for lenders and stronger financial visibility for businesses.
Yet banks cannot resolve the SME financing gap alone. High operating costs, delayed customer payments, weak contract enforcement and uncertain economic conditions can undermine otherwise viable borrowers. Credit works best when accompanied by financial-management support, reliable market access and a predictable business environment.
First National Bank’s approach nevertheless marks an important conceptual shift. It recognises that a company’s most valuable security may not be a building or parcel of land, but its demonstrated ability to generate revenue and manage money responsibly.
“In many ways, strong financial performance becomes a form of collateral, helping businesses access the funding they need to scale and succeed,” Mr Achiampong said.
The ultimate test will be whether the facility moves beyond attractive language and extends meaningful credit to businesses previously excluded by collateral requirements. If implemented transparently and priced responsibly, it could turn everyday financial discipline into a bridge between entrepreneurial potential and investable growth.

