


- CUTS Backs Digital VAT but Warns Overseas Students Could Pay an Unfair Price
Ghana’s effort to collect taxes from cross-border digital services has won qualified support from CUTS International, Accra, but the policy think tank has warned that its implementation could produce an inequitable outcome for students enrolled in recognised overseas distance-learning programmes.
In a statement issued on October 15, CUTS described real-time collection on taxable cross-border digital services as necessary to protect the country’s revenue base and create fairer competition between local and foreign suppliers. However, it urged the government to distinguish digital consumption from recognised education delivered online, arguing that the tax treatment should reflect the nature of the service rather than the location of the provider’s platform.
The intervention places two legitimate policy objectives in tension. Ghana needs to capture revenue as commerce migrates online. Yet the country also needs affordable access to education and professional skills. A collection system designed to prevent taxable digital imports from escaping VAT could therefore become counterproductive if it raises the cost of qualifications for working students.
CUTS clarified that the charge often described as “20 per cent VAT” is not a new tax. It combines 15 per cent VAT with the 2.5 per cent National Health Insurance Levy and the 2.5 per cent Ghana Education Trust Fund Levy. Real-time deductions through participating payment providers are intended to improve enforcement of existing obligations on qualifying digital services.
That distinction matters because public debate can easily treat a more visible collection mechanism as a fresh tax. CUTS stressed that the use of an online payment channel alone should not determine liability and that exempt supplies must retain their exemption.
The think tank’s argument for taxing digital consumption is grounded in competitive neutrality. Software, music, films, games and antivirus products that were once purchased on CDs or DVDs are increasingly delivered through downloads and subscriptions. If tax applied when a product was bought physically but disappears when the same need is met electronically by an overseas supplier, digitalisation progressively narrows the tax base.
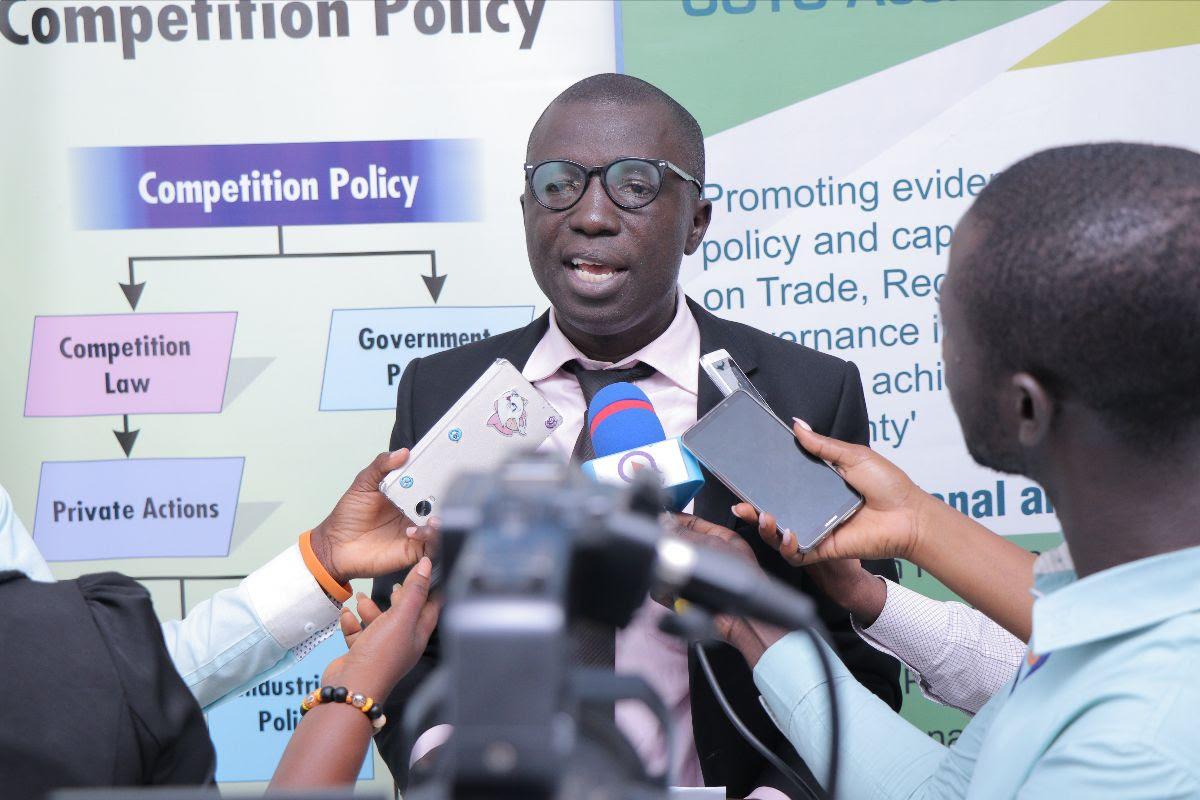
“A software purchase should not escape tax because the customer receives a download instead of a CD. As commerce moves online, tax collection must follow,” said Appiah Kusi Adomako, Director of the West Africa Regional Centre of CUTS International.
He warned that leaving taxable digital imports outside effective collection would create a growing hole in Ghana’s revenue base. It could also disadvantage VAT-compliant Ghanaian suppliers competing against foreign businesses serving the same consumers without collecting equivalent taxes.
Properly administered, it is also a market-governance instrument: comparable taxable services should face comparable obligations, regardless of whether they arrive across a shop counter or through a screen. The risk, however, lies in using a broad collection architecture without sufficiently precise exemptions and redress mechanisms.
CUTS linked stronger revenue mobilisation to Ghana’s ability to finance public services and reduce dependence on borrowing. “Taxes are the subscription we pay to live in a civilised society,” Mr Adomako said, pointing to Free Senior High School and other social interventions financed from public revenue.
But the organisation also placed a reciprocal obligation on the state. Better collection must be matched by prudent spending, reduced waste and transparent accounting. Taxpayers are more likely to accept efficient enforcement when they can see that government treats their contributions as scarce public resources rather than an open-ended source of financing.
Transparency must extend to the point of payment. CUTS called on banks and suppliers to separate the service price, statutory taxes and bank charges, allowing customers to understand exactly what has been deducted. Such disclosure would help distinguish lawful taxation from processing fees.
The Ghana Revenue Authority’s arrangements for wrongful deductions received praise, although CUTS said credibility would depend on execution. Banks should make complaints simple, issue reference numbers and process refunds promptly. The GRA should publish clear channels, resolution deadlines and escalation procedures, while customers should retain invoices and transaction records.
The possibility of double taxation matters. Where a foreign supplier already collects Ghanaian VAT, an additional bank deduction on the same payment would impose an unlawful duplicate cost. Coordination among the GRA, payment providers and overseas suppliers is therefore central to making real-time collection accurate rather than merely automatic.
Education presents the sharper test. CUTS cited the University of London, whose Ghana tax notice states that it is registered with the GRA and applies 15 per cent VAT plus the two 2.5 per cent levies to payments by Ghana-resident students. CUTS emphasised that this is collection under Ghanaian requirements, not a separate British tax imposed on Ghanaian learners.
“Two students living in Ghana and pursuing comparable recognised qualifications deserve fair tax treatment,” Mr Adomako said. Charging a learner because a university teaches from abroad, while comparable tuition from an approved Ghanaian institution is exempt, raises an equity question that the current framework must confront.
The economic issue is access. Distance education allows workers and people with family responsibilities to gain recognised qualifications without paying for relocation, travel and overseas living expenses. Adding 20 per cent to tuition can erode that advantage and exclude students for whom remote study is the only realistic route to international education.
CUTS is therefore asking the Ministry of Finance, GRA and Ministry of Education to clarify the exemption rules and create a transparent recognition process for qualifying foreign programmes. Any relief should rest on clear accreditation criteria and apply to the levies as well as VAT. If existing legislation prevents equivalent treatment, the organisation says government should amend it.
The proposal does not weaken the case for taxing commercial digital services. Rather, it demands a more intelligent tax boundary. Streaming entertainment, software subscriptions and recognised university tuition may share a payment channel, but they do not serve the same public purpose.
Ghana’s challenge is to make digital taxation both effective and discriminating. Closing collection gaps can strengthen revenue and competition, but fairness will determine whether the system earns trust. By protecting genuine education while taxing consumption consistently, government can show that digital enforcement is not simply about collecting more, but about collecting correctly.

