


- Government Sees Community Banks as Next Engine of Local Enterprise Finance
Ghana’s improving macroeconomic outlook and the ongoing recapitalisation of the Bank of Ghana are expected to provide a stronger foundation for the country’s newly branded community banking sector, Deputy Finance Minister Thomas Nyarko Ampem has said.
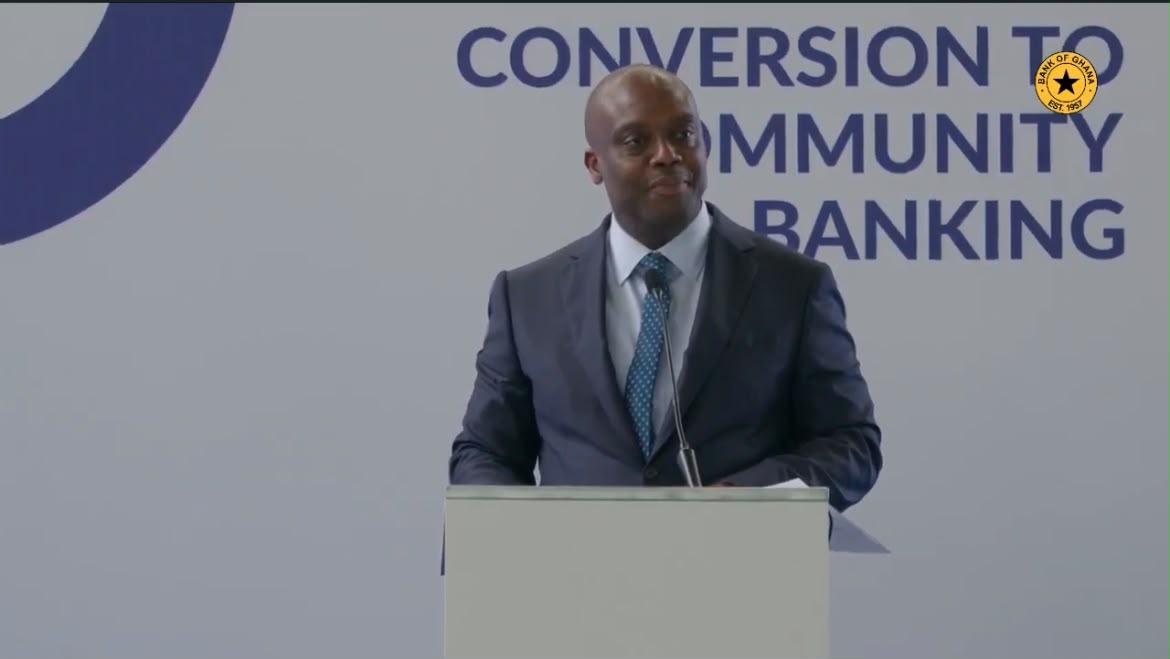
Delivering the keynote address on behalf of Finance Minister Dr Cassiel Ato Forson at the commemoration of 50 years of rural banking and the formal transition to community banking, Mr Ampem said the sector’s evolution represents more than a name change. It marks a strategic shift from expanding physical banking access to building digitally enabled financial institutions capable of supporting Ghana’s next phase of inclusive development.
He described the transition as “the renewal of a vision for a changing economy,” arguing that community banks must now reposition themselves as modern, technology-driven institutions that promote financial literacy, support agriculture, finance small businesses and serve as trusted development partners in local economies.
“The community bank of the future must be more than a lender,” he said. “It must become a trusted development partner, a digital financial service provider, a champion of financial literacy, a catalyst for agriculture and a cornerstone of inclusive growth.”
The Deputy Finance Minister said the sector had grown from a policy experiment launched in 1976 into a nationwide financial network comprising 147 licensed institutions, nearly 1,000 branches and more than eight million customers.
That scale, he noted, makes community banking one of Ghana’s most important channels for financial inclusion, particularly for farmers, traders, small-scale entrepreneurs and households that have historically remained outside the reach of mainstream commercial banking.
“Only a few sectors can claim to have transformed lives so quietly, so consistently and so profoundly,” Mr Ampem said.
His comments come at a time when Ghana is seeking to consolidate recent macroeconomic gains while directing more credit into productive sectors. For policymakers, community banks are expected to play a stronger role in mobilising domestic savings, financing agriculture, supporting micro and small enterprises, and extending financial services to communities where large commercial banks have limited presence.
Mr Ampem linked the sector’s future prospects to stronger policy coordination between the Ministry of Finance and the Bank of Ghana, citing disciplined fiscal management and complementary monetary policy as key pillars of the emerging stability.
He also disclosed that government issued a GH¢5 billion bond in March 2026 to begin recapitalising the Bank of Ghana, describing it as the first phase of a programme aimed at restoring the central bank’s balance sheet by 2032. He said the 2027 Budget would include a further allocation to continue the recapitalisation process.
According to him, rebuilding the Bank of Ghana’s financial strength will reinforce institutional independence, preserve monetary policy credibility and strengthen confidence in the financial system.
The recapitalisation of the central bank has become a key part of Ghana’s post-crisis financial repair agenda, following the pressures created by fiscal stress, debt restructuring and earlier losses on the Bank’s balance sheet. For the broader financial system, a stronger central bank balance sheet is expected to support confidence, policy credibility and supervisory authority.
For community banks, the improved macroeconomic environment could create room for stronger deposit mobilisation, better liquidity planning and more disciplined lending to productive sectors. But Mr Ampem cautioned that the next phase of growth must be built on digital transformation, sound governance and prudent risk management.
He urged the institutions to embrace technology while preserving their community-centred identity, warning indirectly against a model that pursues digital expansion without adequate controls, accountability and customer trust.
That balance will be central to the future of the sector. Community banks have built their relevance on proximity, familiarity and local knowledge. Their advantage lies in understanding the farmers, traders, artisans and small enterprises that drive local economies. But to remain competitive, they must combine that relationship-based model with digital channels, stronger data systems, modern risk tools and improved customer service.
Mr Ampem reaffirmed government’s commitment to working with the Bank of Ghana, ARB Apex Bank and industry stakeholders to strengthen the sector, saying the next phase of community banking should focus not only on expanding access to finance but also on broadening economic opportunity.
“The pioneers of 1976 built institutions that expanded access to finance,” he said. “Our responsibility is to build institutions that expand prosperity.”
The message from government is clear: community banks are expected to become more than rural deposit-taking institutions. They are being positioned as local development engines capable of linking financial inclusion to enterprise growth, agriculture, savings mobilisation and job creation.
As Ghana’s economy stabilises, the challenge will be whether the sector can convert its deep community roots into stronger, better governed and digitally capable institutions.
The next 50 years of community banking will therefore be judged not only by the number of branches opened or customers served, but by how effectively the sector helps turn access to finance into shared prosperity.

