

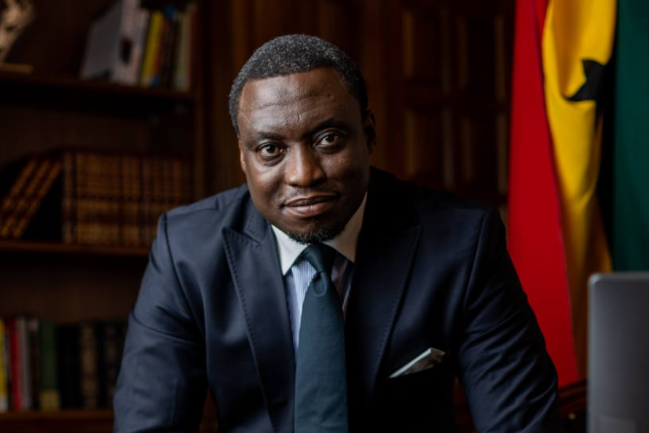

- BoG Must Publish Microfinance Recapitalisation Scorecard to Restore Investor Confidence — Sam Ankrah
Economist and investment strategist Dr Sam Ankrah has called on the Bank of Ghana to publish detailed data on the progress of the country’s microfinance recapitalisation exercise, arguing that greater transparency is needed to restore confidence among investors, depositors and institutions operating within the sector.
His intervention comes as Ghana implements a revised regulatory framework intended to strengthen smaller financial institutions through higher capital requirements, consolidation and tighter supervision. The Bank of Ghana’s reforms require affected institutions to demonstrate how they intend to meet the new thresholds, making the quality and timeliness of regulatory disclosure increasingly important as deadlines approach.
The issue is particularly consequential for rural and community banks, which are being transitioned into Community Banks under the revised microfinance framework. Existing institutions are required to meet a GH¢5million minimum capital requirement by December 31, 2026, while new urban Community Banks face a GH¢10million threshold.
Institutions unable to meet the requirement independently have several options, including raising fresh capital, merging with stronger institutions or transferring assets and liabilities under regulatory supervision. Those that were below the required capital level were expected to notify the central bank by June 30 of the route they intended to pursue and provide further progress updates by September 30.
Ankrah’s argument places transparency at the centre of the exercise. If investors are expected to inject fresh capital into microfinance and community banking institutions, they need enough information to distinguish businesses making credible progress from those that may eventually require restructuring, acquisition or regulatory intervention.
Publishing a sector-wide recapitalisation scorecard could therefore reduce uncertainty. Such a disclosure could show how many institutions already meet the requirements, how many have submitted credible capital restoration plans, which are pursuing mergers and how many remain materially below the regulatory threshold.
That matters because recapitalisation is not merely an accounting exercise. Investors deciding whether to put money into a financial institution will want to understand its existing capital position, asset quality, governance, profitability and the probability that further injections may be required after the initial regulatory threshold is met.
The legal framework already gives the Bank of Ghana substantial powers over institutions that become undercapitalised. Under the Banks and Specialised Deposit-Taking Institutions Act, an undercapitalised institution can be required to submit an acceptable capital restoration plan within 45 days and restore capital adequacy within the prescribed period, while more seriously undercapitalised institutions can face stronger supervisory action.
The transparency question is therefore not about weakening supervision or exposing confidential information about individual customers. It is about whether the market receives enough aggregated and institution-level regulatory information to understand how successfully the reform is progressing and where vulnerabilities remain.
Ghana has particular reason to avoid uncertainty around smaller deposit-taking institutions. The country’s previous financial-sector clean-up demonstrated how quickly weaknesses in governance, liquidity and capital can become a broader confidence problem when customers begin to question whether their deposits are safe.
The IMF estimated that the earlier clean-up of specialised deposit-taking institutions and microfinance companies generated significant resolution costs, including about GH¢1.00 billion for the microfinance clean-up and GH¢3billion for savings and loans companies and finance houses.
That history makes the current exercise especially sensitive. Recapitalisation can strengthen institutions before they reach a point of distress, but the process itself can create anxiety if customers and prospective investors do not know which firms are compliant and which are struggling.
The Bank of Ghana’s revised framework attempts to address structural weaknesses rather than wait for failures. It replaces the previous tiered microfinance structure with clearer categories including Microfinance Banks, Community Banks, Credit Unions and Last-Mile Providers, while providing different pathways for institutions unable to meet capital requirements independently.
The reforms could also trigger a period of consolidation. Institutions with viable businesses but insufficient shareholder capital may find mergers or acquisitions more attractive than attempting to raise the entire shortfall independently, creating opportunities for investors seeking exposure to Ghana’s financial inclusion market.
But consolidation works best when the market has credible information. Potential acquirers need to know the scale of capital deficits and regulatory timelines, while shareholders require enough visibility to decide whether they should inject more funds, dilute their holdings or seek strategic partners.
There are already examples of institutions changing their capital strategy to meet the deadline. Amanano Community Bank, for instance, moved to convert GH¢1.95 million earmarked for dividends into bonus shares as it sought to close the gap between its GH¢3.08 million stated capital and the new GH¢5million requirement.
Such responses demonstrate that recapitalisation can force difficult choices even for institutions reporting profits. Retaining earnings strengthens the balance sheet, but it can also mean shareholders forgoing immediate distributions in favour of preserving the institution’s regulatory standing.
Ankrah’s call therefore raises a broader question for the Bank of Ghana: should recapitalisation progress remain largely a matter between the regulator and individual institutions until the deadline passes, or should the market be given a clearer running account of how the sector is adjusting?
There is a case for the latter. Transparency can itself become a regulatory instrument because institutions know that progress will be visible, investors can allocate capital more efficiently and customers are less dependent on rumours about which institutions may be vulnerable.
Disclosure would need to be handled carefully to avoid triggering unnecessary deposit withdrawals from institutions that remain viable but are still completing legitimate capital-raising plans. Yet withholding too much information also carries risks, particularly in a sector where confidence can deteriorate rapidly once uncertainty takes hold.
The most useful approach may therefore be a structured Bank of Ghana scorecard showing compliance categories, aggregate capital shortfalls and progress against regulatory milestones, supported where appropriate by institution-specific disclosures required under the framework.
That would allow the central bank to protect genuinely supervisory information while giving the market enough evidence to judge whether the reform is on course.
The recapitalisation programme ultimately has to achieve more than a higher statutory capital number. Ghana needs stronger microfinance and community banking institutions capable of protecting deposits, financing small businesses and supporting households that remain underserved by universal banks.
Capital is one part of that equation; governance, risk management and sustainable lending are equally important. But without confidence, even a technically well-designed reform can struggle to attract the private money needed to complete the transition.
That is why Ankrah’s transparency argument deserves attention. As the December deadline approaches, the credibility of Ghana’s microfinance reform will increasingly depend not only on how many institutions survive the recapitalisation exercise, but on whether the Bank of Ghana can demonstrate clearly and consistently how the sector is getting there.

