


- BoG Holds Policy Rate At 14%, Matching Norvanreports Forecast as Inflation Risks Persist
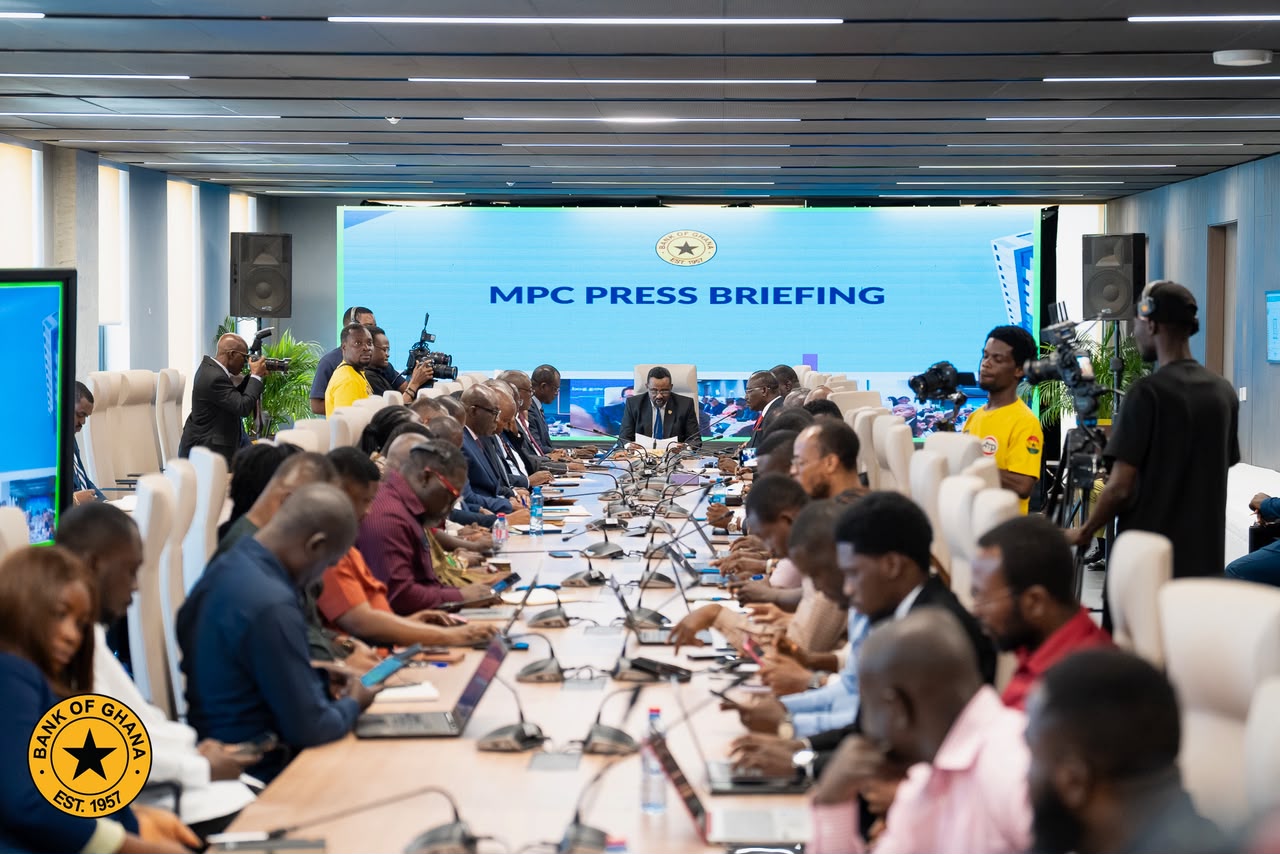
The Bank of Ghana has maintained its benchmark interest rate at 14 per cent for a third consecutive meeting, confirming the outcome anticipated by NorvanReports in an analysis published ahead of the Monetary Policy Committee’s decision.
The Committee voted unanimously to hold the rate after assessing the risks to inflation and economic growth as broadly balanced.
The decision came despite headline inflation remaining below the central bank’s target band, core inflation easing and commercial lending rates declining sharply over the past year.
“Based on these considerations, the Monetary Policy Committee viewed the balance of risks to inflation and growth broadly balanced, and the Committee voted by a unanimous decision to maintain the monetary policy rate at 14.0 per cent,” Governor Dr Johnson Pandit Asiama said.
In pre-decision assessment, NorvanReports concluded that a hold was the most proportionate of the MPC’s three options.
The analysis, titled Bank of Ghana Likely to Hold Policy Rate at 14% as Reserve Losses Outweigh Low Inflation ( https://norvanreports.com/bank-of-ghana-likely-to-hold-policy-rate-at-14-as-reserve-losses-outweigh-low-inflation/ ), argued that the case for a cut appeared persuasive when viewed through inflation alone but became considerably weaker once Ghana’s external position, exchange-rate pressures, rising oil prices and expanding domestic liquidity were considered.
“The most likely outcome is therefore a hold at 14.00 per cent,” the analysis concluded. “The prudent choice is patience.”
The MPC’s decision validates that central argument, although the Committee’s public explanation placed greater emphasis on inflation, global conditions and resilient domestic growth than on the decline in international reserves.
The strongest argument for further monetary easing was Ghana’s low inflation rate.
Headline inflation stood at 5 per cent in August, up from 4.6 per cent in July but still below the lower boundary of the Bank of Ghana’s medium-term target of 8 per cent, plus or minus 2 percentage points.
The policy rate is therefore 9 percentage points above headline inflation, leaving Ghana with a substantially positive real interest rate.
Core inflation excluding energy and utility prices eased to 4.2 per cent in August from 4.3 per cent in July, suggesting that the recent increase in headline inflation was not yet evidence of a broad resurgence in underlying price pressures.
“Despite this, broad inflation expectations and core inflation measures eased, indicating a moderation in underlying inflation,” Dr Asiama said.
The wide gap between the policy rate and inflation provided the MPC with theoretical room to cut. Market interest rates have also declined substantially following the Bank’s earlier easing.
The interbank weighted average rate had fallen to 10.2 per cent by August from 23.28 per cent a year earlier. The Ghana Reference Rate declined to 10.61 per cent from 19.67 per cent, while the average commercial bank lending rate dropped to 15.9 per cent from 24.2 per cent.
These changes have materially eased financing conditions for businesses and households.
Yet the MPC appears to have concluded that monetary policy had already delivered substantial support and that another reduction was unnecessary while the economy remained exposed to external shocks.
Although inflation remains low, its direction has become less reassuring.
Headline inflation fell to 3.2 per cent in March but subsequently increased to 3.4 per cent in April, 3.7 per cent in May and 5.3 per cent in June. It eased to 4.6 per cent in July before rising again to 5 per cent in August.
The August increase was driven principally by non-food inflation, which rose to 6.8 per cent from 6.1 per cent.
Utility tariff adjustments and elevated crude oil prices were among the factors behind the increase.
This composition matters because falling food prices can keep headline inflation subdued even while costs rise across housing, transport, utilities and services.
Further utility tariff adjustments could directly raise household expenses and business operating costs. Higher petroleum prices may increase transport fares and production costs, while a stronger US dollar could make imported fuel, machinery, pharmaceuticals and intermediate goods more expensive.
A reduction in the policy rate would do little to address an international oil-price shock or an administratively determined utility increase. It could, however, weaken the return on cedi-denominated assets at a time when Ghana needs to preserve exchange-rate stability.
The Governor identified additional risks from geopolitical tensions and global supply-chain disruptions.
The MPC nevertheless recognised that continued fiscal consolidation, improved food supplies and exchange-rate stability could offset some of these pressures.
“On the other hand, continued fiscal consolidation, improved food supply conditions, and exchange-rate stability, these present offsetting downside risks going forward,” Dr Asiama said.
NorvanReports’ pre-decision analysis identified Ghana’s international reserves as the strongest constraint on another rate cut.
Gross international reserves declined from US$14.16bn in March to US$11.07bn in August a reduction of approximately US$3.09bn, or 21.8 per cent, in five months.
Import cover consequently fell from 5.7 months to 4.2 months.
Under the IMF programme definition, reserves declined from US$12.24bn in March to US$9.05bn in August, while programme import cover dropped from 4.9 months to 3.4 months.
Net international reserves also fell by almost US$3.18bn, from US$11.87bn to US$8.69bn.
The Bank subsequently reported some recovery, with gross reserves rising to US$12.05bn by September 22, equivalent to 4.5 months of import cover. But that improvement did not fully reverse the decline recorded since March.
NorvanReports argued that the coexistence of an US$8.86bn merchandise trade surplus and falling central-bank reserves showed that strong exports alone did not fully capture Ghana’s external vulnerability.
“The Bank therefore needs to rebuild its net foreign assets before the seasonal increase in dollar demand during the fourth quarter,” the analysis said. “A rate cut could make that task harder by reducing the return on cedi assets and reinforcing expectations of further currency weakness.”
The MPC statement did not explicitly identify reserve losses as the decisive factor behind the hold. But its warnings about a stronger dollar, elevated oil prices and tighter global financial conditions point to the same underlying concern: preserving external stability.
The domestic economy also does not appear to require emergency monetary support.
Real gross domestic product expanded by 6 per cent in the second quarter, following growth of 6.4 per cent in the first. Services and industry were the main drivers of the second-quarter performance.
Private-sector credit growth accelerated to 35.5 per cent in August, while the average lending rate declined by more than 8 percentage points compared with the previous year.
These figures suggest that earlier monetary easing is already being transmitted through parts of the financial system.
Strong credit growth can support investment, employment and economic activity. But if it continues significantly above nominal economic growth, it may also stimulate imports, increase domestic liquidity and eventually create inflationary or exchange-rate pressures.
NorvanReports had noted that reserve money expanded by 29.7 per cent, narrow money by 22.4 per cent and broad money by 23.4 per cent.
The expansion does not guarantee a new inflation surge, as some of it reflects financial normalisation following a prolonged period of tight monetary conditions. But it weakens the argument that the economy requires another immediate rate reduction.
The MPC can instead observe how the recent growth in credit and liquidity affects consumer spending, imports, asset prices and inflation.
Keeping the policy rate at 14 per cent does not necessarily mark the end of Ghana’s monetary-easing cycle.
Inflation remains favourable, core price pressures are contained and commercial borrowing costs have fallen. If oil prices stabilise, the cedi strengthens and international reserves recover further, the case for another reduction could become stronger.
But the Bank is signalling that it will not respond mechanically to current inflation.
Monetary policy must consider not only the level of inflation but also its composition, expected direction and the external buffers supporting currency stability.
An increase in the policy rate would have been difficult to justify while inflation remained below target and inflation expectations were easing. A cut was more plausible but would have exposed the Bank to additional risk at a time of rising energy costs, reserve pressure, cedi depreciation and rapid credit growth.
The Committee therefore selected the middle course anticipated by NorvanReports: neither reversing the easing cycle nor extending it prematurely.
For businesses, the decision provides stability but delays the prospect of another policy-induced decline in borrowing costs. Commercial rates may continue to fall gradually, although banks will also price loans according to credit risk, funding costs and the quality of their balance sheets.
For the cedi, the hold maintains a relatively attractive interest-rate position while allowing the Bank to rebuild reserves and monitor fourth-quarter foreign-exchange demand.
The MPC’s decision ultimately reinforces the conclusion reached in the earlier NorvanReports analysis: Ghana’s immediate monetary challenge is no longer simply to bring inflation down.
It is to preserve the stability already achieved without exhausting the external buffers that helped produce it.

