

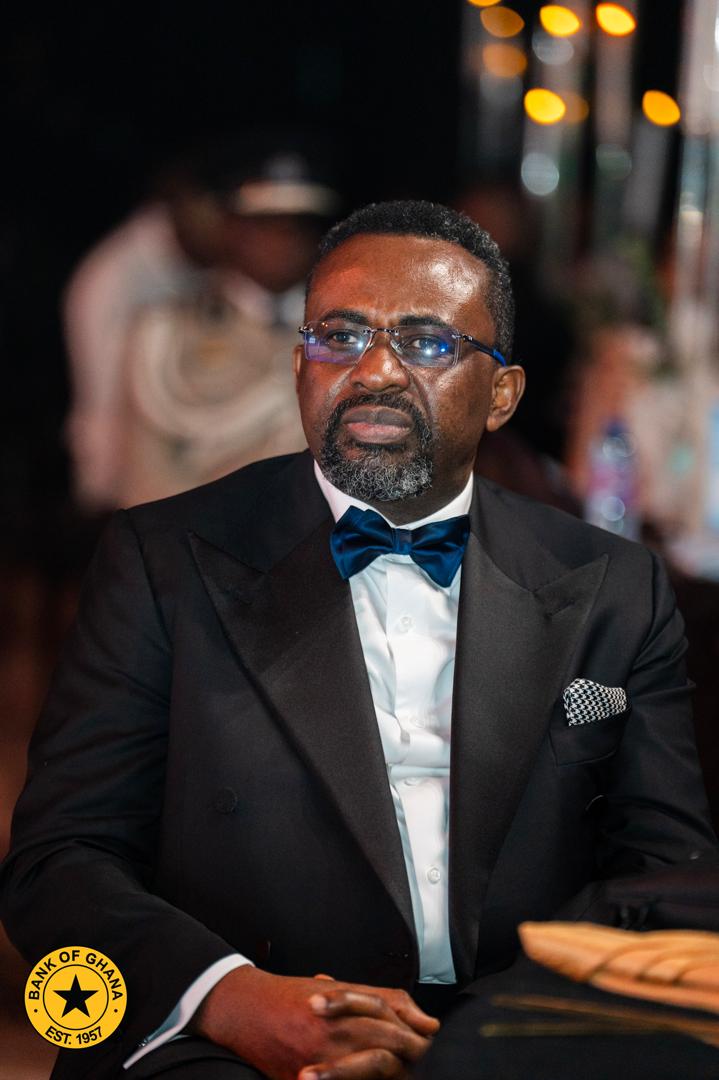

- Dr Asiama Says Ghana’s Stability Gains Require Cautious Monetary Policy
Bank of Ghana Governor Dr Johnson Pandit Asiama has defended the Monetary Policy Committee’s decision to hold the policy rate at 14% since May, saying the pause followed emerging inflation risks even as lower borrowing costs and stronger private credit supported economic activity.
Addressing Parliament’s Committee on Economy and Development on November 6, Dr Asiama described the first half of 2026 as a “period of consolidation”. He said inflation had fallen sharply before turning upwards, the cedi had depreciated after a strong appreciation in 2025, and the Bank needed to rebuild foreign-exchange reserves amid global uncertainty.
The Bank began 2026 with two rate cuts. In January, it reduced the policy rate by 2.5 percentage points, from 18% to 15.5%, and in March cut it by a further 1.5 points to 14%. The committee then held the rate at 14% in May, July and September.
The shift from easing to holding reflected a change in the balance of risks. Inflation reached a low of 3.2% in March, but rose to 5.3% in June. Dr Asiama attributed the increase partly to higher global oil prices, utility tariff adjustments and other domestic price changes. By October, inflation had reached 5.5%, still below the Bank’s medium-term target band of 6% to 10%.
The Governor said the committee paused rate cuts to preserve the credibility built during the disinflation process and allow earlier reductions to flow through the economy. The rate, he said, is not only a cost of borrowing but an anchor for inflation expectations. The Bank expects inflation to move into the target band in the coming quarters, though the timing will depend on domestic and external prices.
That caution sits alongside evidence that monetary easing had begun to reach borrowers. The average lending rate fell from 27% in June 2025 to 15.6% in June 2026, while the 91-day Treasury bill rate declined from 14.7% to 5.3%. Private-sector credit growth rose to 41.2% in June, which the Governor said supported credit to productive sectors.
The key question for the Bank is whether stronger credit can continue without reigniting price pressures, especially if currency weakness and imported energy costs persist. The committee’s three consecutive holds suggest it is prioritising the durability of lower inflation over further near-term reductions in borrowing costs.
The external accounts illustrate the tension. Ghana recorded a trade surplus of US$8.81 billion and a current account surplus of US$5.1 billion in the first half of the year, supported by export performance and external inflows. Gross international reserves stood at US$12.94 billion at end-June, equivalent to five months of import cover.
But the cedi depreciated by about 7.9% against the US dollar in the first half. Dr Asiama linked the movement to foreign-exchange demand for energy imports and dividend payments, as well as uncertainty associated with the conflict in the Middle East.
The statement also noted that the cedi had appreciated by 40.7% against the dollar in 2025, making the subsequent adjustment part of a sharp reversal from the previous year’s gains.
The pressure on reserves continued after June. The Bank reported that gross international reserves fell to US$11.07 billion, or 4.2 months of import cover, at end-August, before recovering to US$12.05 billion, equal to 4.5 months of cover, by September 22.
The increase from the August level was welcome, but reserves remained below the US$13.8 billion recorded at the end of 2025.
The Bank is targeting 15 months of import cover by 2028 through the Ghana Accelerated National Reserve Accumulation Programme, which became operational in April. Achieving that objective will require sustained accumulation of foreign assets, particularly as import, dividend and other external payment demands compete for foreign exchange.
The Governor said the Bank had also changed how it manages liquidity and intervenes in the foreign-exchange market. In June, it replaced the dynamic cash reserve ratio with a uniform 20% requirement held in cedis.
The change allowed banks to use some of their existing investments in open market operation bills to meet the new requirement, reducing the stock of interest-bearing bills and lowering the Bank’s sterilisation costs.
The Bank continues to use open market operation bills to absorb excess liquidity, alongside sterilising foreign-exchange purchases and coordinating with the Finance Ministry on government cash management. These measures aim to prevent unintended liquidity injections that could complicate inflation control.
On foreign-exchange interventions, Dr Asiama said the Bank had adopted pre-announced windows, clearer rules-based triggers and stronger forward guidance on reserve objectives and the circumstances in which it would not intervene. The objective is to make intervention more transparent and predictable for importers, exporters and financial institutions.
The Governor said exchange-rate volatility in the first half was lower than in the corresponding period of each of the previous four years, despite the depreciation.
That distinction matters: a currency can weaken while trading conditions remain orderly, but continued reserve losses could make confidence more difficult to sustain. The Bank’s challenge is to rebuild buffers without creating expectations that it will defend a particular exchange-rate level.
The banking sector indicators provided a more positive picture. Total banking assets increased by 30.7% to GH¢502.4 billion, while the capital adequacy ratio stood at 20.4%.
The non-performing loans ratio fell from 23.1% in June 2025 to 16.1% in June 2026, and further to 15.7% in August. The Governor said the sector remained resilient, while noting the need to sustain that improvement.
Fiscal developments also supported monetary policy. The overall deficit was estimated at 0.4% of GDP in the first half, below the 2% target for the period, while public debt stood at about 45% of GDP. Dr Asiama said these developments helped the broader stabilisation effort.
The policy picture is therefore mixed but coherent: lower inflation and borrowing costs have created room for recovery, while cedi depreciation, oil-price risks and reserve levels counsel restraint. The Bank’s immediate test will be whether it can maintain price stability and support credit growth while rebuilding foreign-exchange buffers.
Dr Asiama told MPs the Bank would remain “data-dependent” and take necessary action to safeguard price stability. For households and businesses, that means the prospect of further rate cuts will depend not only on inflation’s direction, but also on whether external pressures ease and reserve accumulation becomes more durable

