

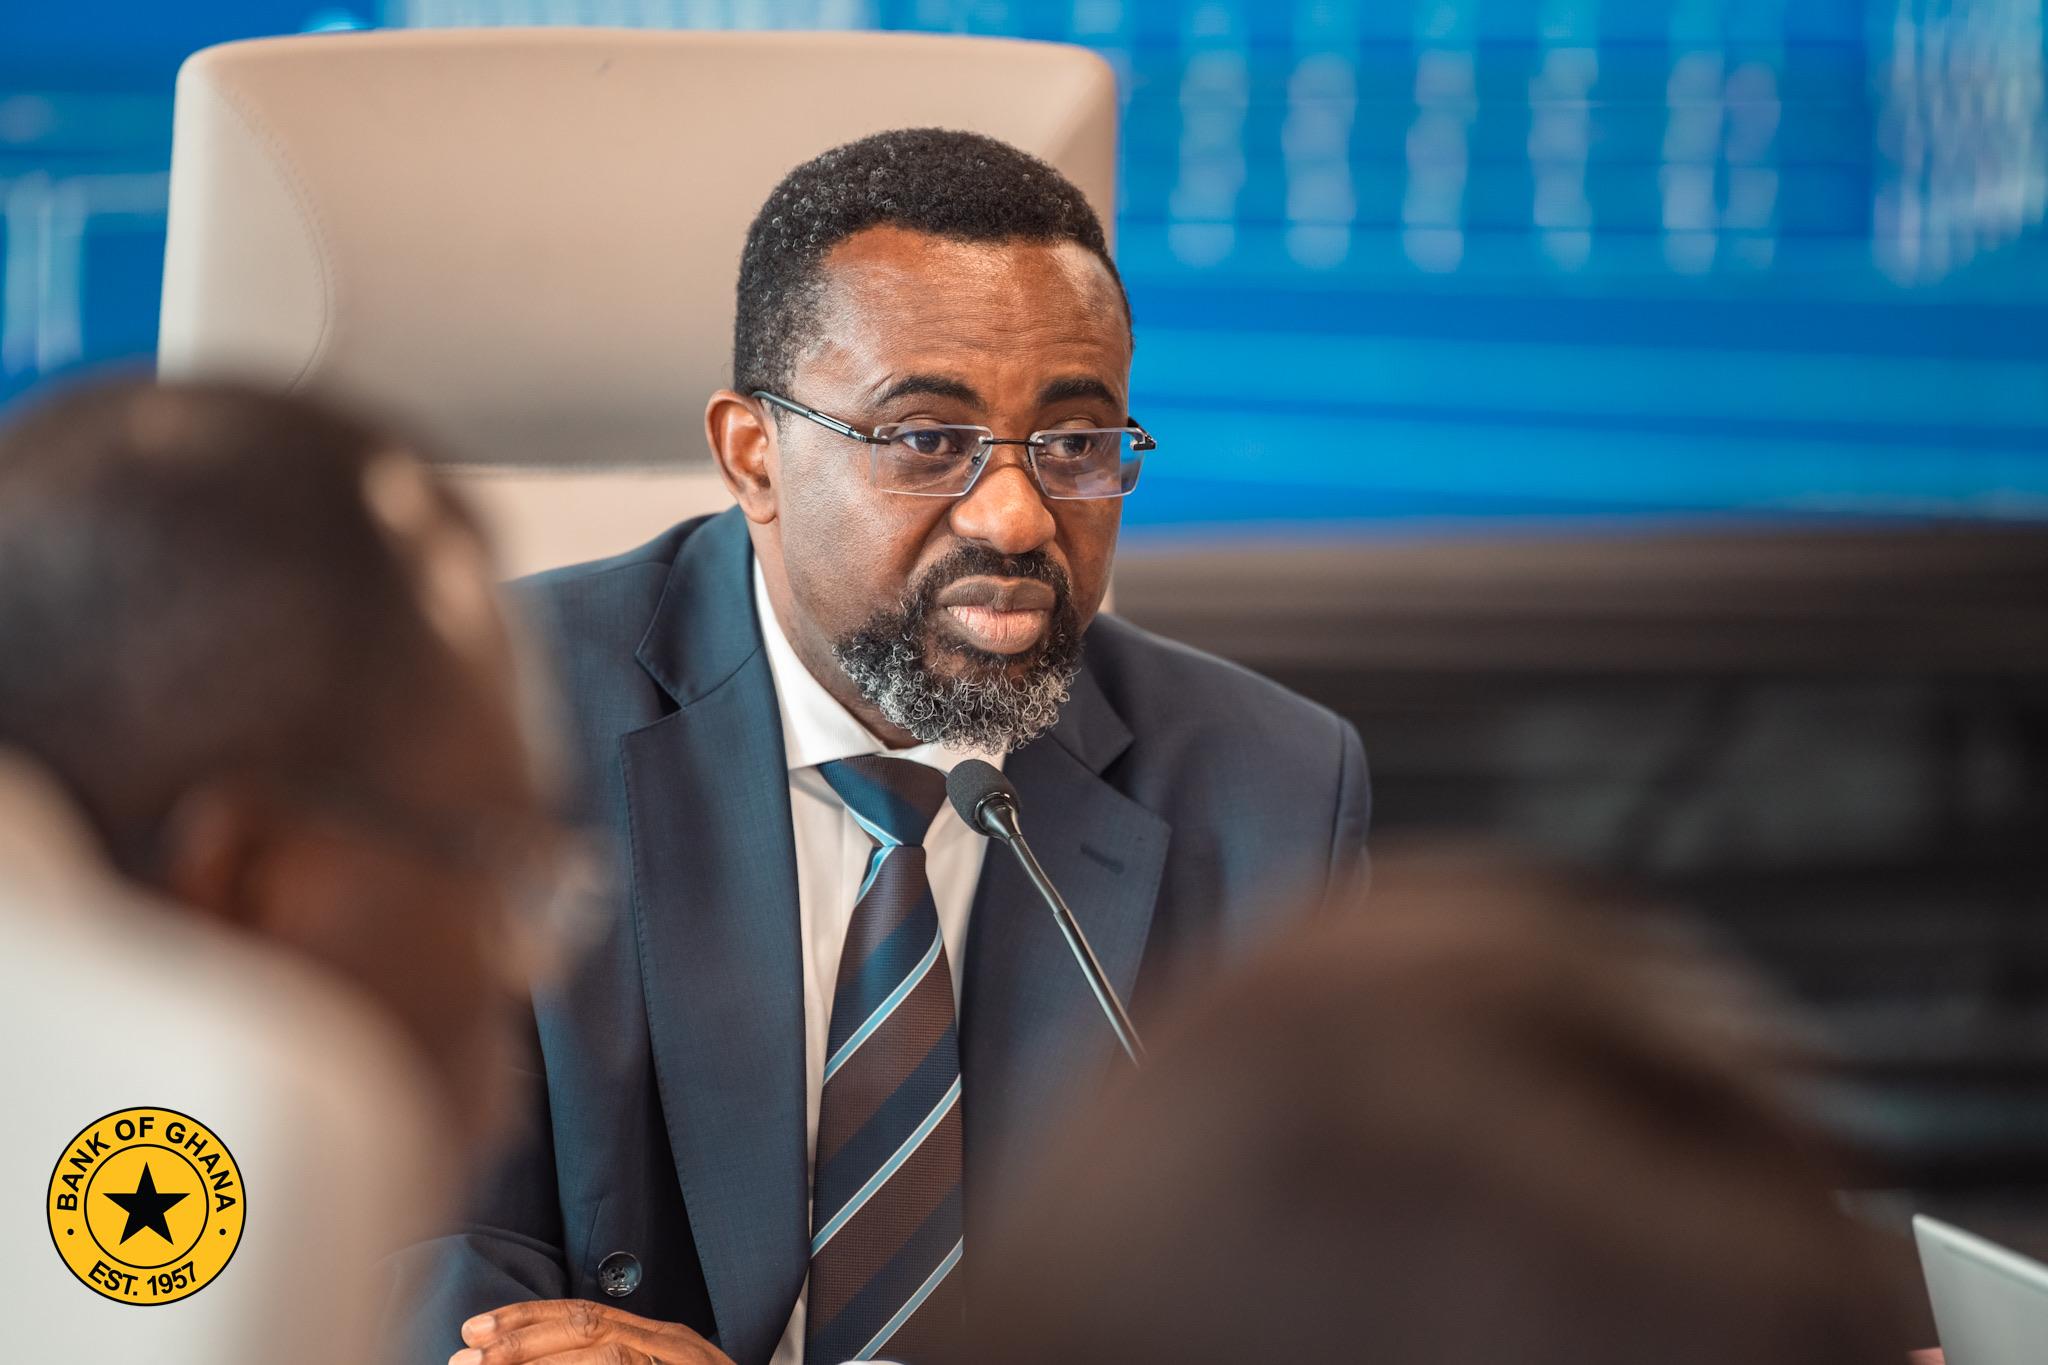

Policy Sequencing, Upcoming IMF Review, FX Stability and Gold Purchase Programme on the Table for Discussions at Ongoing 128th MPC Meeting
Deliberations at the ongoing 128th Monetary Policy Committee (MPC) meeting centre on four critical policy considerations as the Central Bank assesses how to consolidate recent macroeconomic gains.
The first area of focus for the MPC is the pace and sequencing of any future policy adjustments, including whether monetary easing should proceed gradually with pauses to reassess evolving conditions and how such decisions are clearly communicated to the market.
The second consideration relates to foreign exchange stability and expectations. Governor of the Bank of Ghana, Dr Johnson Asiama, speaking at the opening of the 128th MPC meeting, notes the cedi remained remarkably stable throughout 2025, reflecting improved confidence and a strong external position. However, he cautioned that while recent exchange rate pressures appeared largely seasonal, expectations will now be critical in sustaining stability going forward.
The third key issue before the Committee is the role of the Domestic Gold Purchase Programme in supporting macroeconomic stability. He acknowledged that the programme has played a deliberate role in strengthening external buffers but stressed that its timing, sustainability and balance sheet implications must inform ongoing policy calibration and reserve accumulation efforts.
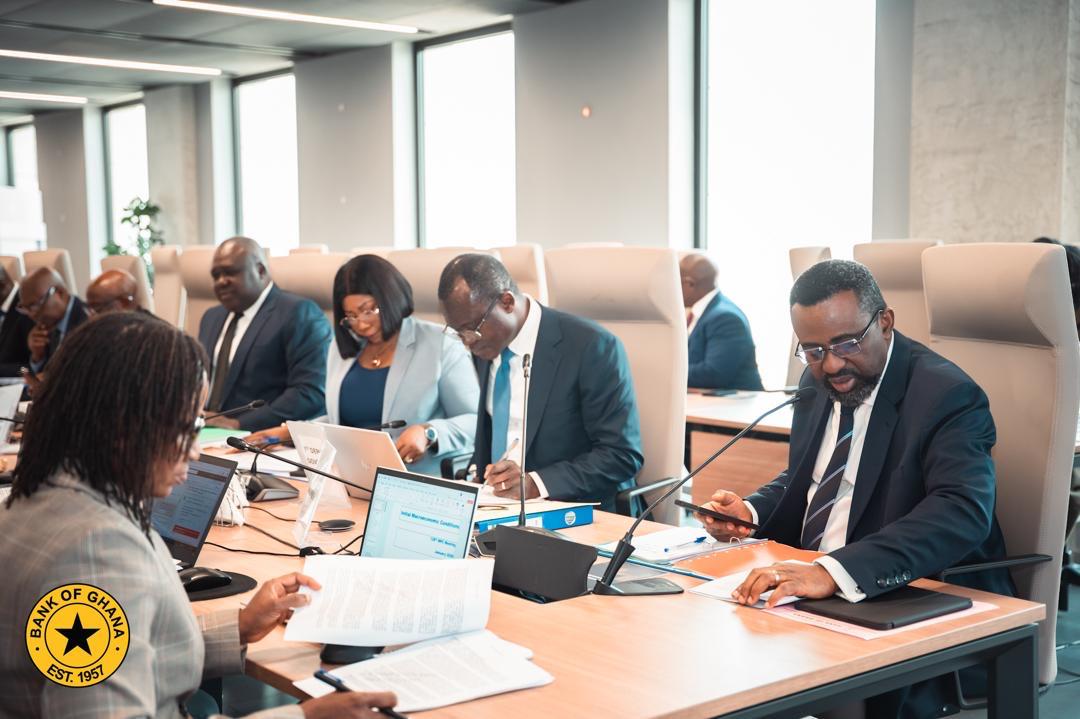
The fourth and final consideration by the Committee concerns external scrutiny and data integrity, particularly ahead of the International Monetary Fund (IMF) programme review scheduled for April 2026. The Governor notes that the review will be based on end-December 2025 data, making the MPC one of the first bodies to rigorously assess indicators central to programme performance, including inflation, reserve accumulation and strict adherence to zero central bank financing, alongside the transparent recognition of legacy and policy-mandated quasi-fiscal activities.
The 128th MPC meeting, the first for the 2026 fiscal year, follows improved macroeconomic conditions underpinned by strong policy outcomes.
Inflation has declined sharply to 5.4% at the end of 2025, coming in well below expectations, with external buffers strengthened significantly. Gross international reserves have hit over $13.8 billion, equivalent to 5.7 months of import cover, supported by a current account surplus of 8.1% of GDP.
Economic growth remained strong through the third quarter of 2025, with leading indicators pointing to further expansion in the economy, helping to rebuild confidence among both consumers and businesses.
The 128th MPC meeting is expected to end on Wednesday, January 28, 2026, with the announcement of a new monetary policy rate by the Bank of Ghana.

