

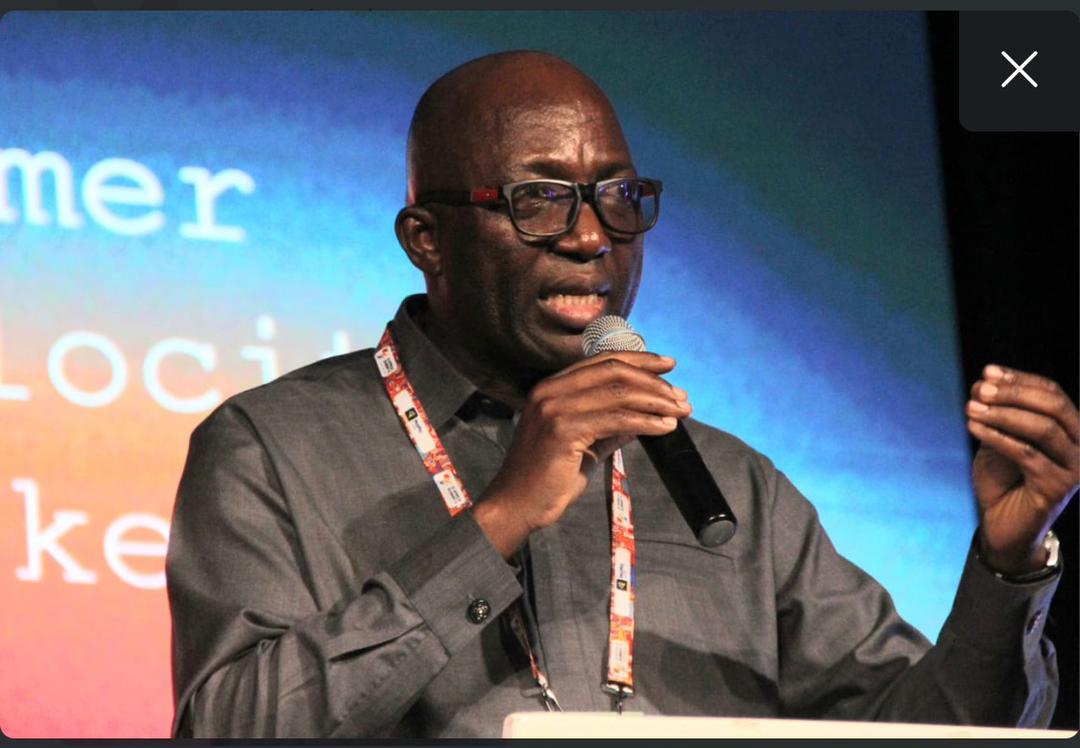

MoMo CEO calls for stronger consumer protection as digital lending surges
The Chief Executive Officer of MobileMoney Fintech Ltd, Shaibu Haruna, has called for stronger consumer protection frameworks to keep pace with the rapid growth of digital lending and mobile financial services across Africa.
Speaking at the 3i Africa Summit which stands for Innovation, Investment and Impact Haruna said the continent’s transition from basic mobile money services to a broader digital finance ecosystem presents major opportunities for financial inclusion, but also introduces significant consumer risks.
He noted that digital lending platforms have dramatically expanded access to credit for millions of previously underserved users by delivering loans at unprecedented speed and scale.
“Digital lending has been a game changer. Millions of people who were previously excluded now have access to credit at unprecedented speed,” Haruna said.
However, he warned that the rapid expansion of digital finance could expose consumers to harmful debt cycles if adequate safeguards are not established.
“Without protection, there is no inclusion and inclusion without protection becomes a trap,” he stated.
Haruna identified transparency, fair pricing and effective complaint resolution systems as critical foundations for sustaining trust in digital financial ecosystems. According to him, consumers must be able to clearly understand interest rates, penalties and repayment obligations through simple and accessible loan disclosures.
The MoMo chief executive also expressed concern about the increasing use of data-driven credit scoring systems, cautioning that algorithmic bias could unintentionally exclude vulnerable groups based on income levels, geographical location or behavioural patterns.
“As we process large data sets, we must be mindful of biases that may exclude customers based on income levels, location, or behavioural patterns,” he said.
He further urged regulators to adopt more adaptive supervisory approaches rather than relying solely on heavier regulation, proposing measures including risk-based lending rules, real-time data sharing frameworks and outcome-based supervision models.
At the industry level, Haruna encouraged fintech firms to implement responsible lending mechanisms such as cooling-off periods between loans, simplified terms and conditions, and stronger ethical standards around customer engagement.
“Speed may be our competitive advantage, but trust must be our licence to operate,” he concluded.
The summit brought together policymakers, regulators, fintech executives and investors to discuss strategies for building inclusive, resilient and innovation-driven financial systems across Africa’s emerging digital economies.

