


Bank of Ghana Keeps November Rate Decision Options Open as Global Uncertainty Confronts Ghana
The Bank of Ghana’s November monetary policy decision is shaping up as a test of how much room the central bank has to support growth without exposing Ghana’s improving economy to another round of inflation and currency instability.
Governor Dr Johnson Pandit Asiama has signalled that tensions in the Middle East, uncertainty across the global economy and movements in key international markets will weigh heavily on the Monetary Policy Committee’s next decision. His comments suggest that domestic progress alone may not be enough to justify an immediate reduction in the policy rate from 14 per cent.
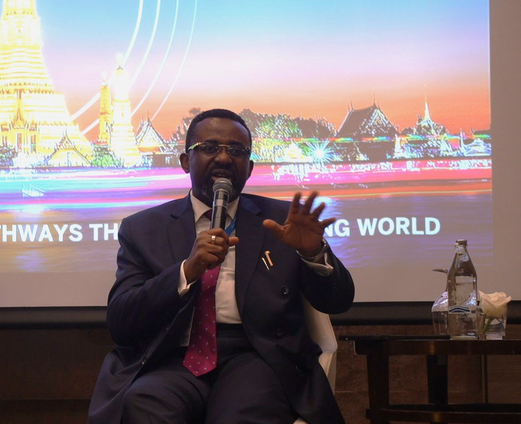
Speaking to institutional investors, brokers and fund managers in Bangkok on the sidelines of the IMF and World Bank Annual Meetings, Dr Asiama identified movements in the United States dollar and gold prices, tighter financing conditions and the anticipated effects of El Niño among the principal risks confronting Ghana.
The Governor said the same external pressures influenced the committee’s unanimous decision in September to maintain the policy rate at 14 per cent. That meeting marked the third consecutive hold, reflecting concern that easing too quickly could weaken the progress made in bringing inflation down and stabilising financial conditions.
The caution is understandable. Ghana’s inflation performance has improved substantially from crisis levels, giving households and businesses greater visibility over costs. Yet the balance of risks has become more complicated. A disruption to oil supplies from the Middle East could raise global crude and refined-product prices, increasing Ghana’s import bill and feeding into transport, production and consumer prices.
For a country that imports significant volumes of petroleum products, higher energy prices operate through several channels. They raise demand for foreign exchange, put pressure on the cedi, increase the cost of electricity and transportation, and eventually lift prices across the wider economy. That combination could slow disinflation even when domestic demand remains contained.
The central bank must therefore distinguish between temporary price shocks and pressures capable of becoming embedded in expectations. If businesses begin pricing goods on the assumption that fuel costs and the exchange rate will continue rising, a short-lived external disturbance can become a broader inflation problem. Holding rates higher for longer may then be necessary to preserve credibility.
Gold presents another complication. Strong gold prices can support export receipts, foreign-exchange supply and reserve accumulation. A significant reversal would weaken an important source of external support just as petroleum-related dollar demand rises. Ghana’s growing reliance on gold-linked foreign-exchange inflows makes the direction of the metal increasingly relevant to monetary policy.
Dr Asiama also pointed to the United States midterm elections in November. He said that after a recent meeting, he asked Bank of Ghana staff to assess what could happen after the polls. The concern is not the election itself, but its potential consequences for fiscal policy, trade, interest-rate expectations and the dollar.
A stronger dollar or prolonged period of high global interest rates would make financing more expensive for emerging and frontier economies. It could also encourage investors to favour dollar assets, increasing pressure on African currencies. For Ghana, which is rebuilding access to international capital after debt restructuring, global risk appetite remains an important constraint.
El Niño adds a different form of uncertainty. Adverse weather could disrupt agricultural production, raise food prices and weaken rural incomes. Food carries considerable weight in Ghana’s inflation basket, meaning climate-related shortages can quickly complicate the central bank’s forecast. Monetary policy cannot produce food, but it must prevent an initial supply shock from spreading into generalised price increases.
A rate cut could lower borrowing costs, support investment and reinforce the recovery in credit. Businesses have argued that expensive finance limits expansion and job creation.
An ill-timed cut could also weaken demand for cedi assets and intensify foreign-exchange pressure. If that translated into renewed depreciation, the inflationary impact could erase part of the benefit that lower rates were intended to provide. The central bank’s challenge is therefore to ease only when the gains can be sustained.
The condition of the banking sector will matter. Dr Asiama told investors that the industry remained sound and that asset quality was improving. He attributed the progress to regulatory measures, including liquidity directives and actions intended to reduce the non-performing loan ratio by year-end.
A healthier banking system gives monetary policy a stronger transmission channel. Banks with adequate capital, liquidity and improving loan books are better positioned to extend credit when rates eventually decline. Conversely, easing policy before balance-sheet weaknesses are addressed may add liquidity without producing productive lending.
The Governor also defended the Bank of Ghana’s 2025 financial results, arguing that its losses reflected the cost of stabilising the economy. He pointed specifically to open-market operations used to absorb liquidity and help reduce inflation. Dr Asiama described the loss as a one-off and said he did not expect it to recur this year.
He projected an improved financial position in 2027 and suggested the central bank could return to surplus by 2032. The government has also agreed to recapitalise the Bank through bond issuance, with an agreement potentially being signed next month.
Recapitalisation matters because an independent and adequately capitalised central bank is better able to pursue price stability without fiscal pressure shaping its decisions. But issuing government bonds to rebuild the Bank’s capital also places an obligation on the state, making sustained fiscal discipline essential.
November’s decision will consequently reflect more than the latest inflation number. The committee must examine the cedi, oil and gold prices, reserve buffers, food risks, global yields, domestic liquidity and the credibility of fiscal policy. Each variable can reinforce or offset another.
The most defensible approach is a genuinely data-dependent one. If inflation remains contained, the cedi stabilises and external conditions improve, cautious easing may become possible. If oil prices, dollar strength or weather shocks worsen, another hold would protect the recovery.
Ghana has earned greater monetary flexibility through painful stabilisation. The November test is whether policymakers use that flexibility patiently enough to ensure that today’s recovery becomes durable rather than another brief pause between crises.

