

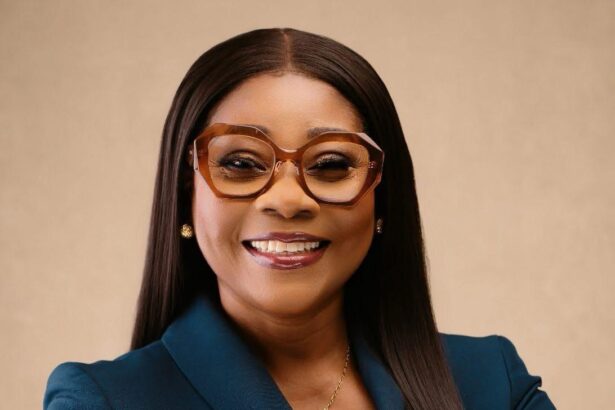

- Banks must Match Digital Innovation with Stronger Cybersecurity Controls – Deputy Governor
The Bank of Ghana has warned financial institutions that the rapid expansion of digital banking must be accompanied by stronger cybersecurity, data protection and operational safeguards to prevent innovation from weakening public confidence in the financial system.
Matilda Asante-Asiedu, Second Deputy Governor of the central bank, said digital platforms, new payment systems and greater interconnectedness were changing how financial services were designed, delivered and consumed.
While those developments offered opportunities to broaden access and improve efficiency, she said they also created risks that banks must identify and manage effectively.
“Innovation must be matched by strong controls and appropriate safeguards, so that confidence in the financial system is protected, not put at risk,” Mrs Asante-Asiedu said.
She was speaking at the commissioning of Absa Place, the new head office of Absa Bank Ghana, at Ridge in Accra.
The facility represents a significant investment by a bank whose institutional history in Ghana stretches back more than a century. But the Deputy Governor argued that the true value of the building would depend on whether it strengthened the bank’s governance, resilience and service to customers.
“For a bank, however, the value of such an investment must extend beyond the physical structure,” she said.
“It should be matched by the strength of its governance, the resilience of its operations, the soundness of its decisions, and the trust it earns and sustains among its customers and the wider public.”
The remarks signal that the Bank of Ghana views investment in modern banking infrastructure as inseparable from the quality of the institution operating within it.
A new headquarters can bring employees, technology and decision-making systems together. It can also improve business continuity and service delivery. But physical investment does not, by itself, protect depositors from cyberattacks, weak governance, liquidity problems or imprudent lending.
“Ultimately, the significance of Absa Place will be measured not by its architecture, but by how effectively it supports these institutional responsibilities,” Mrs Asante-Asiedu said.
The Deputy Governor described Absa Bank Ghana as a systemically important institution whose financial and operational health affects more than its shareholders.
Its decisions influence depositors, businesses, employees, counterparties and confidence in the wider banking system.
“As a systemically important bank in Ghana’s financial sector, Absa Bank Ghana carries responsibilities that extend well beyond its commercial interests,” she said.
“This demands prudent risk management, adequate capital, strong liquidity, regulatory compliance and responsible conduct, consistently applied.”
Systemically important banks occupy a sensitive position because disruption at one institution can spread through payment systems, interbank relationships and public sentiment.
A significant operational failure may prevent customers from accessing funds or businesses from completing transactions. A cyber breach can compromise sensitive customer data, while liquidity or capital weaknesses can undermine confidence beyond the affected bank.
The central bank is therefore demanding that innovation receive the same level of board and management attention as traditional financial risks.
“The Bank of Ghana will continue to support innovation that improves access and efficiency, while maintaining the safeguards required to protect customers and preserve financial stability,” Mrs Asante-Asiedu said.
“We expect Absa Bank Ghana Ltd, and the banking industry more broadly, to approach innovation with the same seriousness it applies to capital conservation, liquidity and credit-risk management.”
That comparison is significant. Banks have historically treated capital, liquidity and credit quality as their principal prudential obligations. Digitalisation means operational resilience and cybersecurity can no longer be considered secondary technology issues delegated exclusively to information-technology departments.
They have become core financial-stability concerns requiring board oversight, investment, testing and accountability.
Mrs Asante-Asiedu said Absa Place should provide the bank with a more resilient operating environment that supports collaboration, dependable operations and secure customer service.
But she framed the commissioning as the beginning of a responsibility rather than the conclusion of a construction project.
“The commissioning of Absa Place marks not only the completion of a corporate building, but the beginning of a responsibility: to use this investment to strengthen the institution and enhance the experience of the customers and businesses it serves,” she said.
The distinction reflects the changing nature of competition within Ghana’s banking sector.
Banks are increasingly assessed not only by the size of their branch networks or corporate buildings, but also by the reliability of mobile applications, speed of payments, security of customer data and their ability to maintain services during technology failures.
Customers may rarely visit a bank’s headquarters, but they experience the quality of its underlying infrastructure whenever they make a transfer, access a digital platform or seek help after a transaction fails.
The benefits of Absa Place will therefore be judged through outcomes: fewer service disruptions, stronger cybersecurity, faster decisions and more consistent customer protection.
Mrs Asante-Asiedu said the facility should reinforce “a culture in which innovation is responsible, growth is sustainable, and trust is earned through consistent conduct”.
The Deputy Governor’s speech also carried a broader message for Ghana’s financial sector.
Technology can widen financial inclusion and reduce the cost of serving customers. Greater interconnectedness can make payments faster and allow banks to develop more responsive products.
But interconnected systems also transmit failures more quickly. A weakness within one bank, payment provider or technology partner may affect several institutions simultaneously.
The central bank’s challenge is to permit innovation without allowing competitive pressure to push banks into deploying systems before adequate controls are in place.
For banks, the test is whether digital growth strengthens the customer relationship rather than merely lowering operating costs or increasing transaction volumes.
Absa Place reflects confidence in the bank’s future and in Ghana’s financial sector. Its longer-term significance, however, will depend on what occurs inside the building: how risks are discussed, how systems are protected, how customers are treated and how management responds when controls fail.
A modern banking headquarters can represent institutional ambition. But as the Bank of Ghana has made clear, the enduring measure of a bank is not its architecture. It is the resilience, judgement and trust that the institution demonstrates when customers place their money in its care.

