

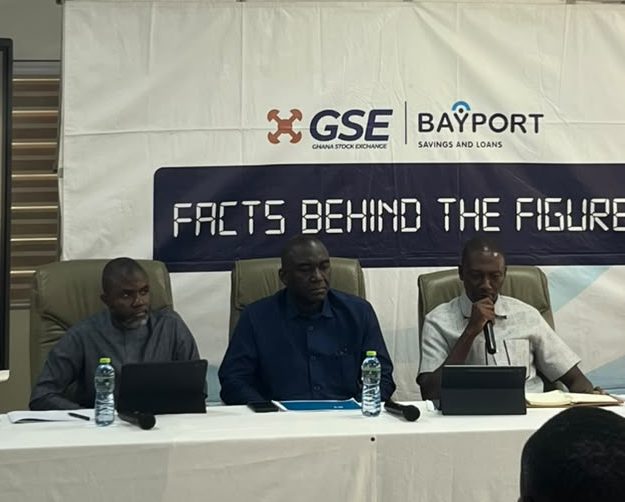

- Bayport Eyes Half of Ghana’s Payroll Lending Market as 2026 Profit Target Hits GH¢240 million
Bayport Savings and Loans PLC is targeting at least 50% of Ghana’s government payroll lending market by the end of 2029, as the lender seeks to combine falling interest rates, stronger risk controls and digitally enabled distribution to accelerate growth among public-sector workers.
Akwasi Aboagye, Chief Executive Officer and Managing Director of Bayport Ghana, said the company currently controls about 33% of the market and believes it can substantially expand that position over the next three years.
“Today we control a third of the market, 33% market share, and we want to be able to continue helping the teachers a lot more, helping the average civil servant to be able to come into the financial net, and that is what we stand for,” Mr Aboagye said.
“I think in the next two to three years, we should control half of the market. So that’s my desire for the team, and that’s what we are working towards. By end of 2029, we should control minimum 50% of the government payroll market share.”
The target is ambitious because payroll lending is one of the more competitive segments of Ghana’s consumer-credit market. The attraction for lenders lies in the relative predictability of repayments through salary deductions, while the challenge is maintaining pricing discipline and credit quality as institutions compete aggressively for the same pool of borrowers.
Bayport believes the current macroeconomic environment gives it more room to grow. Mr Aboagye said declining interest rates have allowed the lender to reduce loan pricing, helping bring more civil servants into the formal credit market.
“Although we have grown, we’ve grown at a time where interest rates have come down and it has allowed us to drop our interest rates so that more civil servants can take loans with us,” he said.
“There’s a need for credit, there’s a need for loans to meet very basic needs. I think in the past, the cost of it was a challenge, and us being able to reduce our price, it has meant that we’re able to serve a lot more customers.”
That relationship between market rates and consumer lending is important. Lower funding costs can give lenders greater flexibility to reduce loan prices, but the extent to which that translates into sustainable credit growth depends on whether institutions maintain underwriting standards while expanding volumes.
Bayport’s strategy is also increasingly focused on geographic reach. The lender sees public-sector workers in rural and peri-urban communities as an important growth market, particularly in locations where conventional banking infrastructure remains limited.
“If you go to the villages, you know, there’s no financial institution there. So the teachers are working there, the nurses are working there, and they don’t have access to credit,” Mr Aboagye said.
“What we are doing is that we are taking credit to the doorstep of the government employees.”
The model relies less on traditional branches and more on technology-enabled agents.
Bayport plans to deploy field representatives equipped with tablets to identify and onboard eligible customers in underserved areas, allowing it to expand distribution without incurring the full cost of establishing physical branches in every community.
“So we send agents, who we have given tablets, to go and meet with the teachers and onboard them,” Mr Aboagye said.
That approach reflects a broader shift in financial services, where customer acquisition and account origination are increasingly being separated from brick-and-mortar networks.
For Bayport, the economics are particularly relevant. Moving from a 33.00% market share to 50.00% would require rapid customer growth, and a low-cost digital distribution model could allow that expansion to happen without a comparable increase in operating expenses.
The strategy is already feeding into stronger profit expectations. Mr Aboagye said Bayport recorded GH¢118 million in profit at half-year and is targeting approximately GH¢240 million for the full year.
“My expectation for this year is that we should end the year double the profits that we reported at half year. So in half year, 118 million cedis. I believe that on the path that we are on, we should be able to end the year around 240 million cedis,” he said.
If achieved, the target would represent a significant earnings milestone for the lender and reinforce management’s argument that growth is being accompanied by stronger operating performance.
The more important test, however, will be asset quality. Rapid loan-book expansion can boost income in the short term, but it can also create future losses if underwriting standards deteriorate or collections weaken.
Bayport’s non-performing loan ratio stood at 8.10% at half-year, according to Mr Aboagye, below the 10.00% level he referenced for the Bank of Ghana. He said management wants to reduce the ratio into the 7.00% range before the end of 2026.
“In terms of NPLs, we are below the Bank of Ghana 10%. We are 8.1% at half year. My goal is that we should be in the 7% before the end of the year,” he said.
He attributed the improvement to stronger risk-management processes and better customer selection.
“Today we know how to originate better, we know how to lend better, we know how to find good customers, we know the kind of customers we should be giving loans to.”
That is central to Bayport’s 2029 ambition. A larger market share will only create durable value if growth is accompanied by disciplined credit assessment, effective collections and sufficient capital to absorb unexpected losses.
The company also sees macroeconomic stability as an important enabler of investment.
Mr Aboagye said a more stable currency has reduced uncertainty around technology expenditure and made it easier to work with external IT partners.
“So currency stability has helped us invest a lot more in technology, because if the dollar is fairly stable, we are able to work with a lot more IT partners, and that’s why we’ve been able to invest a lot more,” he said.
That matters because much of Bayport’s planned scale-up depends on technology. Agent onboarding, loan origination, customer verification and collections all become more efficient when systems are integrated and digital. A stable exchange rate also reduces the local-currency cost volatility associated with imported software, licences and technical services.
The lender is simultaneously trying to strengthen depositor and investor confidence. Mr Aboagye said the company’s growth has benefited from customers feeling more comfortable placing funds with Bayport because they understand how those resources are deployed.
“People feel a lot more secure bringing money because they know that when the money comes to Bayport, we are going to serve the teacher, the nurse, the doctor. And that has really, really allowed us to grow.”
The positioning is important because payroll lending can generate relatively predictable cash flows, but it also requires stable funding.
A lender that grows its loan book faster than its funding base can create liquidity pressure, while one that expands too slowly risks losing market share. Bayport’s challenge is therefore to manage the pace of growth across both sides of its balance sheet.
Its 2029 target also raises a broader question about financial inclusion. Payroll lending can help public-sector workers meet education, housing, healthcare and other household financing needs. But access alone is not enough; affordability and responsible lending standards matter just as much.
Lower interest rates may improve that equation if savings in funding costs are passed through to borrowers.
For Bayport, the opportunity lies in combining that affordability with distribution.
The company believes digital onboarding can extend formal credit deeper into rural Ghana without depending on conventional branch economics, while improved risk analytics can help preserve loan quality as the customer base expands.
“This business will continue to grow without compromise on NPL ratio, and also without compromise on credit quality,” Mr Aboagye said.
That statement will ultimately define the credibility of Bayport’s growth plan. Reaching 50.00% of the government payroll lending market would significantly increase the lender’s scale. But the more important question is whether it can achieve that expansion while simultaneously lifting profit towards GH¢240 million, reducing NPLs and maintaining disciplined credit standards.
If it can, Bayport’s strategy would amount to more than a market-share grab. It would demonstrate how lower interest rates, digital distribution and better risk management can be combined to deepen consumer credit without allowing growth to undermine asset quality.

