


- Domestic Investors Now Hold 70% Of Ghana’s Government Securities as Confidence Recovers
Domestic investors now account for about 70 per cent of holdings in Ghanaian government securities, marking a decisive shift towards local financing as the country rebuilds confidence following the 2022 Domestic Debt Exchange Programme.
Foreign investors hold the remaining 30 per cent, according to Elizabeth Owiredu, Head of the Debt Market Division at the Ministry of Finance.
The changing ownership structure could reduce Ghana’s vulnerability to abrupt reversals in foreign portfolio flows while creating a more dependable domestic pool of capital for government and corporate financing.
But it also increases the potential economic cost of investment fraud, weak market conduct or another breakdown in public confidence. With Ghanaian households, pension funds, banks and institutional investors holding a larger share of domestic securities, damage to the market would increasingly be absorbed within the country.
“Ghana’s capital market has come a long way since the difficult period of the domestic debt exchange programme in 2022,” Ms Owiredu said.
“Activity on both the fixed-income market and equity markets has improved significantly, and many more Ghanaians are taking an interest in investing.”
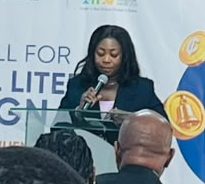
She was speaking at the Ghana Stock Exchange’s Ring the Bell for Financial Literacy Campaign 2026 at Cedi House in Accra.
The event was held under the theme “Investor Resilience, Digital Deception and Scam Alert” as Ghana attempts to deepen its investment culture while responding to increasingly sophisticated digital fraud.
“Government welcomes this renewed confidence and we are determined to protect it,” Ms Owiredu said.
A stronger domestic investor base can provide greater stability to Ghana’s financial markets.
Foreign portfolio capital often responds quickly to changes in international interest rates, exchange-rate expectations and political risk. When external investors withdraw simultaneously, emerging economies can experience currency depreciation, falling bond prices and higher borrowing costs.
Domestic investors are generally less likely to exit the country’s financial system entirely, even when they change the composition of their portfolios.
Greater local participation could therefore help Ghana build a more stable financing base, support secondary-market liquidity and channel domestic savings into infrastructure and private-sector investment.
However, the legacy of the debt exchange remains relevant. Domestic investors bore substantial costs when the government restructured local bonds, affecting confidence in sovereign securities and the wider capital market.
The recovery in market activity suggests that confidence is returning. Preserving it will require consistent fiscal policy, transparent debt management and credible protection for investors.
It will also require policymakers to avoid treating domestic savings as an unlimited source of government financing. Excessive sovereign borrowing could crowd out businesses and concentrate financial-sector assets in government securities.
The government’s capital-market ambitions are developing alongside rapid growth in digital-asset activity.
Ms Owiredu cited an International Monetary Fund estimate placing Ghana-related cryptocurrency transactions at about US$21bn annually, with between 8 and 17 per cent of the population estimated to have bought or sold crypto assets.
She also referred to Securities and Exchange Commission estimates showing transactions of about GH¢113bn, equivalent to roughly US$10bn, by November 2025.
“This reflects real innovation and appetite,” she said. “It also shows how Ghanaians could be exposed to unregulated platforms and outright scams.”
The figures illustrate the scale of investment activity taking place outside traditional capital-market institutions.
Digital assets and online investment platforms can lower transaction costs and extend financial services to people who might not open conventional brokerage accounts.
But the same technology allows unlicensed operators to approach thousands of potential investors through social media, messaging applications and mobile platforms.
“A single fraudulent scheme can wipe out a family’s life savings, disrupt market stability and undo years of work in building trust in our financial system,” Ms Owiredu warned.
The risk is no longer confined to obviously suspicious schemes. Artificial intelligence can be used to manufacture endorsements, imitate trusted public figures and create professional-looking promotional materials for platforms with no regulatory approval.
This means financial literacy must evolve beyond explaining interest rates, equities and diversification. Investors must also learn to verify licences, identify digital impersonation and question promises of guaranteed or unusually high returns.
The Ministry of Finance intends to deepen its collaboration with the Ghana Stock Exchange and financial regulators in 2027.
The reforms will seek to improve market liquidity, attract additional listings, introduce innovative financial products and broaden participation among ordinary Ghanaians.
“We hope to develop a clear framework to guide investment and savings by Ghanaians,” Ms Owiredu said.
The government also wants to support “well-regulated platforms through which ordinary Ghanaians can safely invest”.
The policy challenge will be to regulate digital investment without suppressing legitimate innovation.
Rules that are too weak could expose households to fraudulent platforms, while overly restrictive requirements could prevent credible fintech companies from developing lower-cost investment products.
Clear licensing categories, disclosure standards, customer-fund safeguards and complaints procedures will be necessary if digital platforms are to contribute to capital-market development.
The government is calling for stronger co-operation among the Securities and Exchange Commission, National Insurance Commission, National Pensions Regulatory Authority, Cyber Security Authority, Financial Intelligence Centre, Economic and Organised Crime Office and Ghana Police Service.
The objective is to ensure that investment scams are “detected, disrupted and prosecuted quickly”.
Such co-operation is necessary because digital investment fraud rarely falls within the mandate of a single institution.
A scheme may involve an unlicensed investment product, cyber impersonation, suspicious financial transactions, mobile-money transfers and possible money laundering. A fragmented regulatory response can allow operators to exploit the gaps between agencies.
Financial education will also have to move beyond regulators and market institutions.
Ms Owiredu called on schools, the media, faith-based organisations and community leaders to help spread investor-protection messages. She also highlighted the GSE’s National Investment Quiz as an avenue for introducing financial knowledge to younger Ghanaians.
Ghana’s emerging domestic investor base is potentially one of its most important financial assets.
It could reduce reliance on volatile foreign capital and provide long-term financing for government, infrastructure and private businesses.
But the strength of that investor base will depend on trust. After the disruption caused by the debt exchange, households are returning to financial markets at the same time that digital deception is becoming more sophisticated.
The government’s task is therefore not merely to persuade more Ghanaians to invest. It must ensure that the institutions, platforms and products receiving their savings are credible enough to retain that confidence.
“Let us continue to work together to deepen financial literacy, strengthen investor protection and build a resilient, inclusive and vibrant capital market capable of mobilising the long-term finance required for Ghana’s development,” Ms Owiredu said.

