
- Ghana Targets African Tokenisation Hub as SEC Pushes Common Regulatory Standards
Ghana is seeking to establish itself as Africa’s centre for tokenised assets, but the Securities and Exchange Commission says the ambition will depend on regulators across the continent building compatible rules for a market that does not recognise national borders.
Mensah Thompson, Deputy Director-General of the SEC, said differences in how African countries regulate virtual assets, stablecoins and tokenised real-world assets could undermine investor confidence and restrict cross-border investment.
“We are going to discuss regulatory alignment and policy coordination to ensure that the rules around virtual assets are not different from jurisdiction to jurisdiction,” he said.
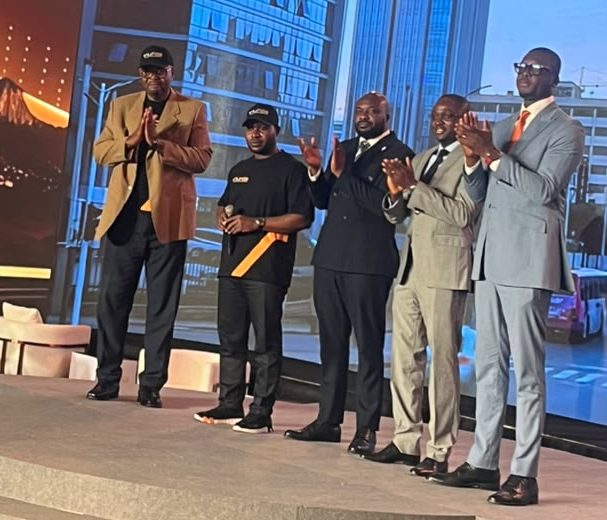
Speaking in an interview on the sidelines of the launch of the Africa Virtual Assets Summit 2026, Mr Thompson said Ghana wanted regulators to move towards comparable standards covering licensing, custody, disclosure, investor protection and financial-crime controls.
The challenge is fundamental. Digital assets can move between countries within seconds, while the laws governing their issuance, distribution and custody remain largely national.
A token issued in Nigeria could theoretically be purchased immediately by an investor in Accra. But the transaction becomes more complicated when the two countries apply different requirements for asset backing, consumer protection, cybersecurity, anti-money laundering controls and the segregation of client funds.
Mr Thompson said regulatory alignment could give investors greater confidence that a digital asset issued elsewhere in Africa had been subjected to standards comparable to those applied at home.
“A token that is issued in Nigeria, a Ghanaian can feel confident to participate in that token because they know that the same stringent supervisory regulations that it would have been subjected to in Ghana have been subjected to in Nigeria,” he said.
Such confidence will be essential if tokenisation is to move beyond domestic pilots and develop into a continent-wide financing market.
Ghana has begun establishing the regulatory infrastructure needed to support the sector.
The SEC’s virtual-asset sandbox, launched in March, includes pilots covering the tokenisation of gold, securities, Treasury bills, bonds and trade-finance assets.
The controlled environment allows regulators to observe how the products are structured, marketed, traded and settled before approving their wider distribution. Information generated from the pilots is expected to inform activity-specific licences and regulatory guidelines under the Virtual Asset Service Providers Act, 2025.
The SEC, Bank of Ghana and Financial Intelligence Centre have also stated that virtual assets can no longer operate outside the country’s regulatory perimeter.
This represents a shift from viewing virtual assets primarily as speculative cryptocurrencies towards treating the underlying technology as financial infrastructure.
For Ghana, the larger opportunity lies in using tokenisation to divide conventional assets into smaller digital units that can be distributed to a wider pool of investors.
Government securities, gold, property, commodities and infrastructure interests could potentially be offered in fractional amounts, reducing the minimum capital required for participation.
But the technology alone cannot create a credible market. Each token must represent a clearly defined and legally enforceable right to an underlying asset. Investors must also know who holds that asset, how it is valued and what happens if an issuer, custodian or trading platform fails.
The Africa Virtual Assets Summit is intended to broaden the regulatory discussion beyond Ghana.
Regulators, policymakers, banks, capital-market institutions and technology companies are expected to focus on three principal objectives: “policy coordination, regulatory alignment and industry integration”.
The summit is also expected to produce an Accra Declaration setting out shared principles and recommendations for Africa’s emerging virtual-asset industry.
“What is Africa’s position on stablecoin? What is Africa’s position on tokenization of real estate, tokenization of gold? What is Africa’s position on integration of virtual assets in traditional financial systems?” Mr Thompson asked.
Those questions go beyond technology. They concern monetary sovereignty, financial stability, capital-market regulation and the extent to which privately issued digital instruments should interact with national payment systems.
Stablecoins, for example, could make cross-border payments faster and cheaper. But widespread use of foreign-currency-backed tokens could also weaken demand for domestic currencies and complicate central-bank control over liquidity.
Tokenised securities could expand investment access, but poorly designed products could distribute complicated risks to retail investors who may not understand the underlying assets.
An African regulatory framework will therefore have to encourage innovation without allowing financial risks to migrate into less regulated jurisdictions.
The greater challenge will come after the declaration. Shared principles have value, but meaningful alignment requires individual countries to translate them into compatible laws, licensing conditions and enforcement practices.
Africa’s markets differ widely in legal tradition, financial depth, supervisory capacity and technological infrastructure. A common regulatory objective will not automatically produce identical rules.
The more realistic goal may be mutual recognition: each country maintaining its own regulations while agreeing on minimum standards that allow approved products and service providers to operate across participating markets.
Mr Thompson also urged traditional financial institutions to treat virtual assets as an opportunity to expand distribution rather than a threat to their existing business models.
“Virtual assets is not a competition. It is an infrastructure on which you can achieve wider coverage, financial inclusion and broader retail participation,” he said.
Banks could provide custody, settlement, payment, compliance and asset-servicing functions within the emerging market. They could also use tokenisation to offer conventional investment products in smaller denominations through mobile and digital channels.
The opportunity is particularly relevant in African capital markets, where retail participation remains shallow and many households hold their savings outside formal investment products.
Yet wider access could also expose inexperienced investors to products whose risks are difficult to assess. Financial inclusion would be undermined if tokenisation merely made speculative or poorly backed assets easier to distribute.
Mr Thompson warned that consumer behaviour was already moving decisively towards digital channels.
“In the next five years nobody will walk to a bank to do a transaction or to do a deposit. Everything will happen on the comfort of your phone,” he said.
“And so if you’re a bank, it’s time for you to think: what do you have to do now so you don’t miss out on tomorrow?”
His prediction may be deliberately forceful, but the direction of travel is evident. Financial institutions that fail to integrate digital distribution, programmable assets and real-time settlement could lose relevance as customer expectations change.
Ghana’s strategy extends beyond supervising cryptocurrency exchanges. The country wants to become a jurisdiction where African assets can be structured, tokenised and distributed under a trusted regulatory framework.
“By essence, we want to make Ghana the hub of tokenization of Africa,” Mr Thompson said. “And this will propel us to be the financial hub of Africa.”
That ambition will place Ghana in competition with other African financial centres seeking to attract technology companies, asset issuers and cross-border capital.
Accra’s advantage will not be determined solely by how quickly it licences platforms or approves new products. It will depend on regulatory credibility, judicial enforceability, cybersecurity, market liquidity and the protection afforded to investors when transactions fail.
Tokenisation can make an asset easier to divide and distribute. It cannot make an unclear title valid, a weak issuer solvent or an illiquid project commercially viable.
Ghana’s opportunity is therefore to build something more valuable than a permissive digital-asset market: a trusted jurisdiction in which investors know what they own and can enforce their rights.
If African regulators can establish compatible standards, a token issued in one country could attract capital from across the continent. If they cannot, Africa risks recreating its existing financial fragmentation in digital form.