


- Ghana’s Agricultural Recovery Masks Industrial Weakness and Uneven Growth – ISSER
Ghana’s agricultural sector staged an encouraging recovery in 2025, but uneven performance across commodities and a sharp slowdown in industrial growth exposed persistent weaknesses in the country’s development model, according to the Institute of Statistical, Social and Economic Research.
In its 2025 State of the Ghanaian Economy Report, ISSER said agriculture expanded by 6.80% in 2025, compared with 2.70% in 2024. Industry, however, slowed markedly to 2.30% from 7.20% over the same period.
The contrast shows an economy returning to stronger headline growth without yet achieving the broad productive transformation required to create sufficient jobs, improve food security and reduce dependence on primary commodity exports.
Ghana’s overall economy grew by 6.00% in 2025, marginally higher than the 5.80% recorded in 2024. Services led the expansion with growth of 8.10%, while agriculture recovered strongly and industry lost momentum.
Agriculture accounted for 22.80% of economic output during the year, making its performance important not only to national growth but also to rural incomes, food availability and inflation.
ISSER described the recovery as encouraging but cautioned that aggregate sectoral growth could conceal weakness in particular commodities. A strong overall figure does not necessarily mean that every farmer, crop or agricultural community experienced improved conditions.
Agricultural output in 2025 was led by crop production, including a recovery in cocoa, while fishing and livestock also expanded. Forestry and logging remained weak.
Crops grew by 7.30%, supported partly by a 14.35% recovery in cocoa. Fishing expanded by 9.45% and livestock grew by 5.60%, while forestry and logging contracted by 2.45%.
The differences matter because Ghana’s food system does not operate as a single market. Strong cocoa production may support exports and rural incomes in producing regions without resolving shortages of maize, rice, vegetables or other staples consumed locally.
Consequently, agricultural growth can rise while households continue to experience high prices or periodic shortages of particular food items. Regional disparities, rainfall patterns, input costs and limited access to storage and markets can also mean that the benefits of recovery are distributed unevenly.
ISSER said sustaining agricultural growth would require improvements in irrigation, mechanisation, extension services and crop yields.
Its recommendations go beyond increasing cultivated land. Ghana’s long-term agricultural challenge is largely one of productivity: how much output farmers can produce from each hectare of land, each unit of labour and each cedi invested.
Effective irrigation would reduce dependence on rainfall and make year-round production more practical. Mechanisation could raise output and reduce the physical limitations facing smallholder farmers, while better extension services would help producers adopt improved seeds, soil-management techniques and climate-resilient farming methods.
However, higher production alone would not be enough. ISSER called for improvements in storage, processing, transport and access to markets to reduce post-harvest losses and strengthen producer returns.
This is critical because farmers can record a successful harvest and still suffer financial losses if they cannot store produce, reach reliable buyers or obtain reasonable prices. Weak logistics frequently create the paradox of produce going to waste in farming communities while food prices remain high in urban centres.
Processing capacity is equally important. Converting agricultural produce into finished or semi-finished goods extends shelf life, creates industrial employment and allows Ghana to retain more value from what it produces.
The weakness of the industrial sector therefore carries direct implications for agriculture. Without competitive agro-processing and manufacturing, improvements in farm production may not generate the wider economic transformation the country needs.
Industry contributed 31.30% of Ghana’s economy in 2025 but grew by only 2.30%. The slowdown was driven principally by an estimated 23.00% contraction in oil and gas production.
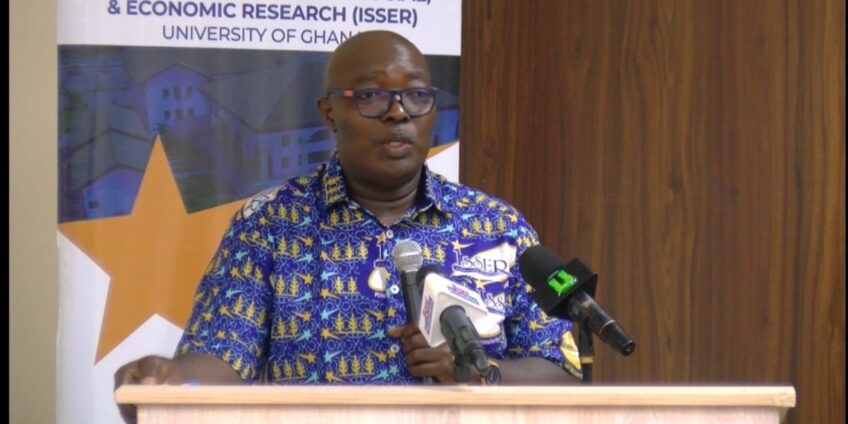
Professor Robert Darko Osei, Director of ISSER, said gold production cushioned the industrial sector from an even worse outcome.
“Industry slowed to about 2.3% from 7.2% in 2024 as oil and gas contracted by roughly 23%, with gold cushioning the fall. Without it, industry would have shrunk,” he said.
That assessment highlights Ghana’s continued dependence on extractive commodities. Gold can support exports, foreign-exchange reserves, fiscal revenue and headline industrial growth, but mining alone cannot provide the scale of employment associated with competitive manufacturing.
The strength of gold therefore risks masking weakness elsewhere in industry. If mineral output accounts for a large proportion of industrial expansion, the economy may record growth without developing the manufacturing ecosystem required to absorb large numbers of workers.
ISSER said Ghana must translate the strength of its mineral sector into broader industrial development through increased domestic value addition and more competitive manufacturing.
This means mineral wealth must do more than generate export receipts. It should support local refining, engineering services, equipment production, research, skills development and domestic supply chains.
The same principle applies to agriculture. Exporting cocoa beans, raw cashew nuts, unprocessed shea and other commodities provides foreign exchange, but processing them locally can generate substantially more income and employment.
The relationship between agriculture and industry should consequently form the centre of Ghana’s structural transformation strategy. Agriculture supplies raw materials to factories; industry provides fertiliser, machinery, packaging and processing capacity to agriculture. When either side is weak, the entire value chain underperforms.
The 2025 data also present a concern for employment. Services accounted for 45.90% of economic output and generated most of the year’s growth. Digital and knowledge-based services can raise productivity, but access to those opportunities is often concentrated among workers with particular skills, education and connectivity.
Agriculture and manufacturing remain more capable of absorbing labour across a wider range of skill levels. Weakness in these sectors can therefore produce an economy that grows without creating enough secure and productive jobs.
ISSER’s analysis suggests that Ghana’s next development challenge is not simply to maintain economic growth but to improve its composition. A recovery dominated by services, gold and selected crops may strengthen national accounts while leaving the economy vulnerable to commodity cycles, food-system disruptions and limited job creation.
The government’s policy response must connect irrigation, agricultural research and extension services with storage, transport, processing and industrial financing. Investments should be assessed not only by their size but by whether they raise productivity, connect farmers to markets and build domestic manufacturing capacity.
Ghana’s agricultural recovery in 2025 offers a useful foundation. But unless stronger farm output feeds into processing, manufacturing and exports, it may remain a cyclical improvement rather than a structural breakthrough.
The warning from ISSER is therefore straightforward: the country must convert its agricultural rebound and mineral earnings into a more diversified productive economy. Otherwise, impressive headline growth may continue to conceal the deeper problem of an economy expanding faster than its capacity to create durable jobs and broadly shared prosperity.

