


Ghana’s Digital Tax Collection Overhaul Could Raise Subscription Costs — Timore Boi
Ghana’s new mechanism for collecting taxes on cross-border digital services could increase subscription costs for consumers and businesses, even though the reform does not introduce a new tax, according to tax analyst Francis Timore Boi.
The system, scheduled to take effect on October 15, will require participating commercial banks and payment service providers to collect applicable taxes on qualifying payments made to foreign digital platforms.
It represents a change in tax administration. Instead of relying mainly on non-resident service providers to register voluntarily, declare their Ghanaian revenues and remit the taxes due, the Ghana Revenue Authority will gain a collection channel closer to the point at which customers make payments.
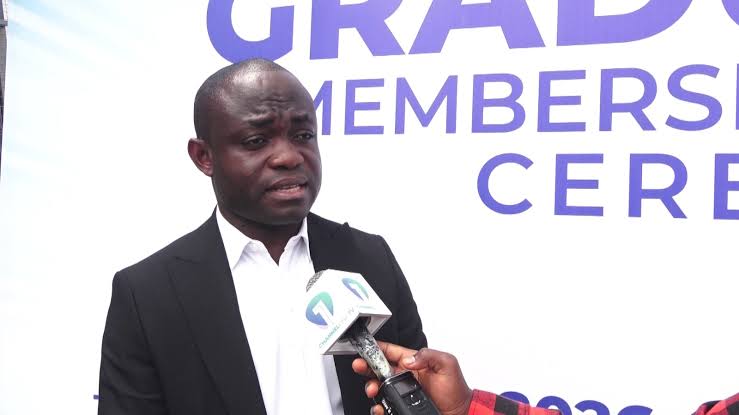
“It’s not a new tax, it’s a new way of collection,” Mr Boi said during an interview on Citi FM’s Eyewitness News.
The distinction is legally important but may offer limited comfort to customers who previously purchased subscriptions from unregistered providers without paying the full statutory charge. For those users, stronger enforcement could make the tax burden visible for the first time.
The applicable charge remains 20 percent, comprising 15 percent Value Added Tax, a 2.5 percent National Health Insurance Levy and a 2.5 percent Ghana Education Trust Fund Levy.
A qualifying subscription costing GH¢100 before tax could consequently rise to GH¢120 if the overseas provider or collecting institution passes the entire statutory charge to the customer. Subscribers using platforms that already include Ghanaian taxes in their prices should not face another deduction.
“Trust me, about 92 providers are already charging. We still have more who are outside, and they are not charging,” Mr Boi said.
He warned that subscribers to currently non-compliant platforms were “likely to see some jump” in the amounts they pay once implementation begins.
The GRA says approximately 92 non-resident digital service providers have registered and are remitting taxes, while about 100 additional operators have been identified for compliance. The figures suggest that the reform could almost double the number of foreign platforms brought within the effective collection net.
For the government, the attraction is clear. Ghana can widen its effective tax base and reduce revenue leakage without announcing a higher rate. At a time when fiscal consolidation requires stronger domestic revenue mobilisation, improving compliance may be preferable to imposing new taxes on businesses already operating formally.
But better enforcement does not eliminate the economic consequences of taxation. It changes who pays, when the payment occurs and how visible the cost becomes.
Foreign digital services are no longer limited to entertainment. Ghanaian households use streaming, gaming, education and communication platforms, while businesses depend increasingly on imported cloud storage, artificial intelligence, cybersecurity, digital advertising, accounting software and productivity applications.
For large companies, a 20 percent charge may be absorbed within technology budgets or recovered through business pricing. For start-ups, freelancers and small enterprises operating on narrow margins, the same increase could influence whether they maintain subscriptions, downgrade services or abandon certain tools.
That creates a policy tension. Ghana wants to mobilise more revenue from an expanding digital economy, but it also wants businesses to adopt the technologies needed to improve productivity, compete internationally and create skilled employment.
If essential digital tools become substantially more expensive, stronger tax collection could unintentionally slow the digital transformation that government policy is seeking to encourage. The answer, however, cannot be permanent non-compliance by foreign suppliers, because that would disadvantage domestic companies that already collect and remit Ghanaian taxes.
Mr Boi defended the reform on precisely those fairness grounds. He argued that international digital operators should carry obligations comparable to businesses serving customers from within Ghana.
“For parity and fairness, you need to extend the administration to the service providers,” he said, citing the treatment of domestic pay-television provider DStv and international streaming platform Netflix.
The principle is difficult to dispute. A company should not enjoy a tax advantage merely because its servers, headquarters or billing systems are located outside Ghana while it earns revenue from Ghanaian customers.
The more difficult question is implementation. Banks and payment service providers must correctly determine which payments qualify, whether a platform has already collected the tax and whether the transaction is genuinely for a taxable digital service.
If collection rules are unclear, customers could face duplicate deductions, inconsistent treatment across banks or delays in resolving complaints. A provider may have included the tax in its advertised price while the payment intermediary, lacking visibility over that arrangement, applies another charge.
The GRA has said the mechanism will not impose additional taxes where the applicable amount has already been collected. That assurance must be supported by a reliable system for identifying compliant providers and updating banks and payment companies promptly.
Mr Boi criticised the limited public education preceding implementation, noting that some consumers did not realise taxes were already incorporated into payments made to certain foreign platforms.
That communication gap risks turning an administrative change into the appearance of a new tax. Customers judge policy by the amount leaving their accounts, not by technical distinctions within tax legislation.
The GRA should therefore publish a clear list of affected services, registered providers, collection responsibilities and complaint procedures. Banks and payment providers should disclose taxes separately on transaction records so customers can identify what was charged and why.
Authorities should also monitor the reform’s effect on small businesses. Better compliance must remain the objective, but evidence of reduced access to essential software could justify targeted support through business deductions, innovation incentives or other transparent measures rather than informal exemptions.
The success of the initiative will be measured by more than revenue collected. It must deliver equal treatment between domestic and foreign suppliers, prevent duplicate taxation, protect consumers and preserve Ghana’s access to the digital tools increasingly required for commerce.
Ghana is right to insist that economic activity conducted digitally should not sit outside the tax system. But efficient collection must be matched by careful, transparent implementation. Otherwise, a reform designed to close revenue gaps could create new costs, confusion and barriers within the economy it is meant to formalise.

