


- Government Ends Delays and Capping In GH¢24.8 billion Statutory Fund Releases — Ato Forson
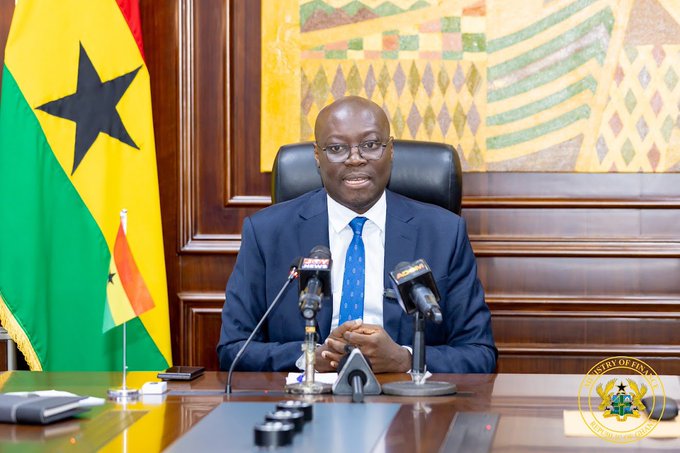
Ghana’s government has released GH¢24.8 billion to statutory funds since January 2026, with Finance Minister Dr Cassiel Ato Forson presenting the payments as evidence that fiscal discipline is beginning to reach institutions responsible for education, healthcare, roads and local development.
The transfers cover the Ghana Education Trust Fund, Free Senior High School Programme, District Assemblies Common Fund, National Health Insurance Fund and Ghana Medical Trust Fund. They also include the Road Maintenance Trust Fund, Mineral Development Fund and Mineral Income Investment Fund.
Dr Forson said the payments had been made on time and in full, contrasting the government’s approach with earlier periods when statutory transfers were affected by delays, expenditure capping and accumulated arrears.
“Unlike in the past, when payments were marked by delays, capping and arrears, we now release these funds on time and in full,” the Finance Minister said following the release of third-quarter allocations.
“This ensures statutory funds have the money they need to provide the essential services required by law.”
The announcement is important not merely because GH¢24.8 billion has moved from the central government to designated funds. Its greater significance lies in predictability. Public institutions cannot plan effectively when legally assigned resources arrive late, arrive partially or are diverted to meet competing short-term pressures.
A district assembly may have an approved development programme, but contractors cannot be paid and projects cannot proceed if transfers remain uncertain. Health insurance claims can accumulate when funding is delayed, placing pressure on hospitals, pharmacies and patients. Schools can receive policy directives without the cash required to implement them.
Timely releases therefore convert budgetary promises into operational capacity. They allow statutory institutions to schedule procurement, manage commitments and reduce the likelihood that suppliers price uncertainty into public contracts.
The payments also carry political and institutional significance. Statutory funds are created by law to protect priority services from the volatility of annual discretionary spending. When their resources are capped or withheld, the legal earmark may remain intact on paper while the intended beneficiaries experience a different reality.
That accountability is useful. Ghana’s fiscal debates frequently focus on headline deficits, debt ratios and revenue performance. Those indicators matter, but they do not always reveal whether individual institutions receive the cash Parliament authorised or whether public services can execute their mandates without accumulating fresh liabilities.
Regular and complete statutory payments offer one way of testing the quality of fiscal management beneath the aggregates. A government may report an improving deficit partly by postponing transfers or allowing obligations to build outside the central budget. Such an approach can make the immediate numbers appear stronger while shifting financial stress to hospitals, road agencies, schools and local authorities.
Avoiding that practice strengthens the credibility of fiscal consolidation. If Ghana can meet statutory obligations while controlling the overall deficit, the adjustment becomes more transparent and less dependent on pushing costs into arrears.
Yet the GH¢24.8 billion figure requires continued public disclosure. The government has identified the funds covered, but citizens would benefit from a detailed breakdown showing how much each institution was due, how much it received and when each payment was made.
Such reporting would allow Parliament, civil society and beneficiaries to verify the claim of full and timely payment. It would also distinguish the release of current allocations from the clearance of any historical arrears.
The distinction matters because paying the current year’s obligations does not automatically resolve liabilities inherited from previous periods. Institutions may receive their 2026 allocation on schedule while still carrying unpaid claims, contractor certificates or commitments accumulated earlier.
Transparency should therefore extend beyond transfers from the Ministry of Finance. Each statutory fund should publish how the money was used, what obligations were settled and which measurable services were delivered.
For the National Health Insurance Fund, the relevant question is not only whether money was released but whether healthcare providers were paid promptly and patients obtained covered services. For GETFund, the test is whether allocations translated into completed classrooms, laboratories and educational facilities rather than a growing list of commitments.
For the District Assemblies Common Fund, predictable transfers should help assemblies move from emergency cash management towards structured local development. But that benefit will depend on procurement discipline, project selection and the capacity of assemblies to execute budgets efficiently.
Road financing presents a similar challenge. Timely transfers to the Road Maintenance Trust Fund can reduce deterioration and lower the eventual cost of rehabilitation, but only if maintenance is prioritised, contracts are monitored and resources are protected from inefficient allocation.
The inclusion of the Mineral Development Fund and Mineral Income Investment Fund also highlights the responsibility to turn resource revenues into lasting public value. Communities affected by mining will measure success through visible development, environmental protection and economic opportunity, not simply through transfers recorded in government accounts.
The broader fiscal challenge is sustaining these payments when revenue performance weakens or unexpected expenditure demands emerge. Statutory obligations compete with wages, interest payments, energy-sector liabilities, social programmes and capital expenditure. Maintaining timely releases during difficult months will provide a stronger test than doing so when cash conditions are favourable.
There is also a balance to strike between earmarking revenue and preserving budget flexibility. Statutory funds protect essential priorities, but excessive earmarking can leave finance ministries with limited room to respond to shocks. The answer is not arbitrary capping. It is transparent budgeting, realistic allocations and parliamentary approval for material changes.
Dr Forson’s announcement should therefore be viewed as an encouraging operational milestone rather than the completion of fiscal reform. The GH¢24.8 billion release indicates that government is attempting to align cash management with legal obligations and service-delivery priorities.
Its lasting value will depend on whether timeliness becomes routine, disclosures become more detailed and recipient institutions convert funding into measurable outcomes. The real achievement will not be the amount transferred from one public account to another. It will be whether schools function better, health claims are paid, roads are maintained and communities can see what the money accomplished.

