


Mobile Money Payments Gain Dominance as ATM Usage Falls Sharply
Ghana’s financial services industry is witnessing a fundamental transformation as customers steadily shift away from cash-driven banking towards mobile-based payment solutions, according to the 2025 KPMG West Africa Banking Industry Customer Experience Survey.
Data from the survey shows a pronounced fall in the use of automated teller machines (ATMs), with patronage dropping to 16 per cent in 2025 from 34 per cent recorded a year earlier. The decline reflects a broader change in consumer behaviour, as Ghanaians increasingly favour digital channels for everyday financial transactions.
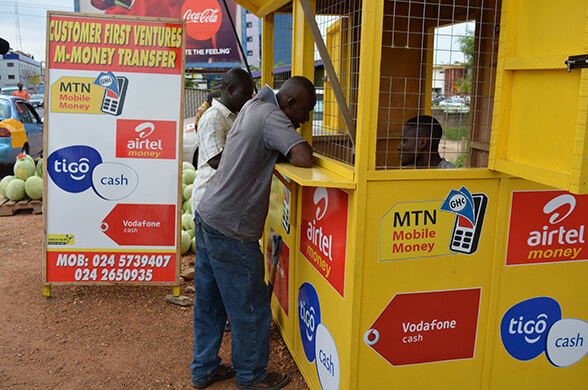
At the same time, mobile money continues to strengthen its position as the dominant payment platform. Usage surged to 80 per cent in 2025, marking its highest level since 2022 and representing a seven-percentage-point increase over 2024. The trend underscores growing customer demand for fast, convenient and reliable financial services.
While digital payments are expanding, bank-controlled digital platforms are facing mounting pressure. Mobile banking applications remained the second most widely used channel, with 44 per cent of customers accessing them weekly, compared to 50 per cent in the previous year. This second consecutive annual decline is raising concerns among banks that rely on mobile apps as a key point of customer engagement.
Interestingly, the reduction in usage has not translated into weaker customer experience. Satisfaction scores for mobile banking apps improved, with ratings for ease of use and system availability rising to 81.4 per cent and 80.7 per cent respectively, suggesting enhanced performance for active users.
USSD platforms continue to provide an important alternative, particularly for basic services such as balance enquiries, airtime purchases and fund transfers. About 26 per cent of respondents reported using USSD services on a weekly basis, highlighting the continued relevance of simple, low-data solutions in Ghana’s financial ecosystem.
KPMG observed that ATMs, once central to banks’ physical presence and customer access strategies, are gradually losing relevance as digital channels become more efficient. However, ATMs have not disappeared entirely and still serve a purpose for occasional cash withdrawals, especially among Millennial customers, where they remain among the most frequently used monthly channels.
Overall, the survey conveys a clear message from customers: digital banking success is no longer about offering multiple channels, but about ensuring a limited number function exceptionally well. Dependability, simplicity, security and transparency are increasingly determining customer loyalty.
For banks and payment service providers, attention is shifting from promoting digital adoption to sustaining relevance in a rapidly changing market. As Ghana’s economy stabilises and digital usage deepens, customers are making their expectations clear—financial services must be seamless, secure and firmly mobile-first.

