

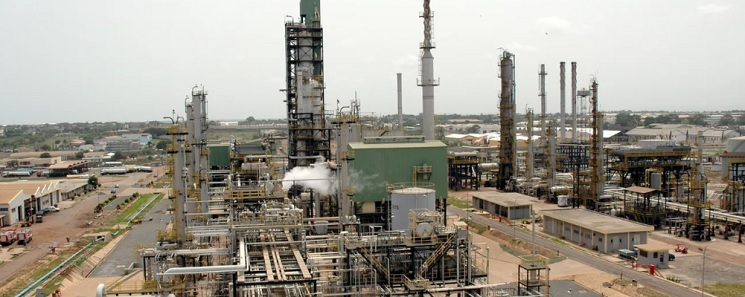

- We Risk Wasting TOR Turnaround Without Mandatory Domestic Crude Supply — IES
Ghana should immediately enforce its existing Domestic Market Obligation framework to guarantee predictable crude supply to local refineries, particularly the Tema Oil Refinery, rather than continue relying on discretionary or politically driven allocations, according to a new policy paper by the Institute for Energy Security.
The IES argues that Ghana already possesses the legal architecture required to compel upstream petroleum contractors to supply part of their crude entitlement to the domestic market, but that the framework has seen limited practical enforcement. The paper says the recent rehabilitation and resumption of operations at TOR removes one of the strongest practical objections to enforcement because Ghana once again has a domestic refinery capable of absorbing crude at meaningful scale.
At the centre of the argument is Section 71 of the Petroleum (Exploration and Production) Act, 2016, Act 919, which permits the Minister responsible for the sector to require contractors to sell a determined share of their petroleum entitlement to meet domestic supply requirements.
Regulation 32 of L.I. 2359, as amended by L.I. 2390, provides the operational framework covering the calculation of required volumes, delivery arrangements, market-based pricing and dispute resolution.
The IES says the problem is therefore not the absence of legislation, but the gap between legislation and implementation. Public evidence of the 90-day notices contemplated under Regulation 32, annual domestic supply calculations or formal price disputes moving through the independent-expert mechanism remains limited, leaving domestic crude supply dependent largely on ad hoc arrangements rather than a standing and predictable obligation.
That distinction has become more important following TOR’s turnaround maintenance programme, which the paper says ran between August and October 2025, with refining operations subsequently resuming in December.
IES reports TOR as operating at about 28,000 barrels per stream day, below its 45,000-barrel nameplate capacity, while plans exist to expand towards 100,000 barrels per day as additional equipment is commissioned.
The policy argument is straightforward: restoring physical refining capacity without securing reliable feedstock risks leaving the refinery exposed to the same operational uncertainty that contributed to years of underperformance.
“A restored refinery does not by itself guarantee restored refining output; it guarantees only the physical capacity to process crude, provided that crude is actually delivered,” the paper states in substance, arguing that predictable supply is now the binding constraint.
IES points to Ghana’s reported one-million-barrel Jubilee crude allocations to TOR as evidence that government is already pursuing domestic supply in practice, but argues that such arrangements should be formalised under Regulation 32.
Its concern is that occasional allocations do not give TOR the certainty required for refinery planning, financing, crude scheduling and sustained throughput.
The paper draws heavily on the experience of Nigeria and Indonesia to make its case. Nigeria’s Domestic Crude Oil Supply Obligation offers a warning about what can happen when a legally sound framework fails to deliver adequate and predictable volumes, while Indonesia’s model demonstrates the benefits of embedding domestic supply requirements more firmly into contractual arrangements.
Nigeria’s experience is particularly relevant because the Dangote Refinery has faced periods in which domestic crude allocations fell short of its estimated feedstock requirements, forcing it to purchase additional crude internationally in dollars.
According to the IES analysis, the combination of dollar-denominated crude purchases and local-currency refined-product sales helped recreate the foreign-exchange exposure that the domestic supply arrangement was intended to reduce.
Indonesia provides the contrasting example. Its domestic market obligation historically required contractors to allocate a defined share of petroleum entitlement to domestic needs, with the obligation embedded directly into production-sharing contracts rather than depending principally on discretionary ministerial intervention, thereby giving refiners and government greater certainty over future feedstock access.
For Ghana, the significance goes beyond keeping TOR operational. IES argues that greater domestic refining could reduce the economy’s exposure to imported petroleum products, international freight disruptions and foreign-exchange demand associated with financing refined-product imports, while also providing greater stability in domestic fuel availability.
The cedi argument is particularly important because petroleum imports remain a recurring source of dollar demand. If locally produced crude is supplied predictably to domestic refineries and settlement arrangements are structured appropriately, a larger share of Ghana’s fuel requirement could theoretically be met without generating the same foreign-exchange demand associated with importing finished petroleum products.
IES nevertheless cautions that simply enforcing the obligation will not automatically deliver those benefits. Domestic allocations must be large enough to match actual refinery throughput, pricing must remain commercially credible to upstream producers, and any cedi-based settlement arrangement must include clear exchange-rate adjustment mechanisms to avoid recreating the currency mismatch experienced in Nigeria.
The institute also argues that enforcement should cover Ghana’s wider refining system rather than TOR in isolation, including other domestic facilities where appropriate. That would require stronger coordination among the Ministry responsible for energy, GNPC, TOR and other refiners so that annual domestic crude requirements reflect actual national refining capacity and demand rather than the needs of a single state-owned facility.
IES recommends that the Minister formally begin issuing the 90-day notices required under Regulation 32 and move domestic supply allocations onto a recurring calendar-year basis. It also calls for publication of annual and monthly domestic supply calculations, transparent application of the weighted-average pricing formula and advance establishment of the independent-expert mechanism used to resolve pricing disputes.
The paper further proposes that future Public Interest and Accountability Committee reporting include specific disclosure of Domestic Market Obligation volumes, notices issued and any pricing disputes, extending transparency beyond petroleum revenues to the enforcement of domestic crude supply policy.
The wider policy challenge is one of balancing resource sovereignty with commercial certainty. Upstream producers must retain confidence that domestic supply obligations will be priced transparently and administered predictably, while the state must ensure that crude produced within Ghana can support domestic energy security when the legal framework already provides for such intervention.
IES therefore frames enforcement not as a new policy invention but as activation of an existing statutory instrument whose relevance has increased following TOR’s return to operation.
Its conclusion is that Ghana now has both the legal authority and a stronger operational justification to replace discretionary crude allocations with a predictable, rules-based domestic supply regime.
For Ghana, the real test will be whether TOR’s turnaround becomes the beginning of a sustainable refining revival or another temporary recovery constrained by uncertain feedstock.
The IES position is that the refinery’s future should no longer depend on occasional crude allocations when the country already has a legal mechanism capable of turning domestic supply into a recurring and enforceable obligation.

