


- World Bank Puts 800 million Jobs Gap at Centre of Development Strategy
The World Bank Group has placed an estimated 800 million-job deficit at the centre of its development strategy, warning that the next generation’s prospects will depend on whether scarce public resources can unlock private investment, infrastructure and productive employment at unprecedented scale.
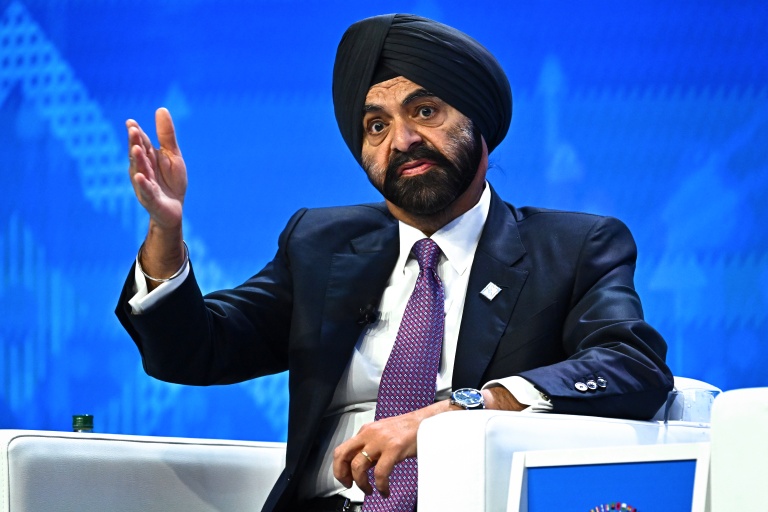
World Bank Group President Ajay Banga told the 2026 Annual Meetings Plenary in Bangkok that 1.2 billion young people would enter labour markets over the next 10 to 15 years, while only about 400 million jobs were expected to be available.
The arithmetic is stark, but its consequences extend beyond unemployment statistics. It raises a more fundamental question about whether development institutions and governments are building economies capable of converting education, technology and demographic growth into opportunity.
“A job is not a statistic. A job is dignity,” Mr Banga said, describing employment as the difference between young people building their futures and merely waiting for them.
His remarks presented a World Bank attempting to redefine its usefulness around that challenge. The institution’s emerging model combines concessional funding where commercial finance cannot operate, private capital where projects can generate returns, philanthropy for early-stage risks and technology to improve productivity.
The argument is that no single source of finance can meet today’s development needs. Conflicts persist, debt burdens have risen, fiscal space has narrowed and essential inputs, including energy and fertiliser, remain expensive. Governments facing those pressures cannot finance every power plant, water system, transport corridor, clinic or school from their budgets.
Yet private capital will not enter simply because governments need it. Investors require reliable infrastructure, predictable regulation and mechanisms that reduce risks they cannot reasonably absorb. The Bank’s jobs strategy therefore rests on three connected pillars: physical and human infrastructure, policy certainty and financial tools capable of bringing projects to scale.
Last year, the institution committed $40 billion, almost one-third of its financing, to foundations including electricity, water, transport, digital connectivity, health, education and skills. Thirty percent of its public-sector financing supported policy and institutional reforms intended to create clearer rules and stronger governance.
The third pillar addresses barriers such as currency risk and limited access to finance through guarantees, equity and local-currency funding. These instruments matter because a commercially sound project can remain unfinanceable if exchange-rate volatility or political uncertainty overwhelms its prospective return.
There is evidence that the strategy is mobilising more money. Private capital raised alongside World Bank operations increased from roughly $35 billion in the 2022 financial year to $112 billion last year. Combined with the institution’s own commitments, total financing exceeded $230 billion.
Mobilisation nearly tripled in lower-middle-income countries, quadrupled in upper-middle-income economies and more than doubled across Africa. Nearly 55 percent of financing and mobilised private capital went to infrastructure and energy, agribusiness, health, tourism and value-added manufacturing—sectors capable of improving productivity while generating employment.
The limitation, however, is revealing. Private-capital mobilisation in low-income countries remained at roughly $3 billion. The places with the greatest need and weakest fiscal capacity are still the hardest in which to attract commercial investment. Without deliberate risk-sharing, the new development-finance model could scale fastest where markets already function reasonably well and slowest where deprivation is deepest.
The Bank’s response is to focus more heavily on micro, small and medium-sized enterprises. Such businesses often operate before larger companies are prepared to invest and play an especially important role in fragile and conflict-affected economies. The institution plans to use digital records to make them more visible to lenders, connect them with larger buyers and simplify the rules constraining their growth.
Banga’s emphasis on practical, or “small”, artificial intelligence follows similar reasoning. Frontier models require computing power, specialised skills, data and energy beyond the immediate reach of many developing countries. Smaller applications can nevertheless help farmers improve yields, teachers personalise instruction, health workers make better decisions and entrepreneurs reach customers.
The scale of the Bank’s sector ambitions demonstrates how it intends to connect finance with measurable outcomes. Mission 300, undertaken with the African Development Bank, seeks to provide electricity access to 300 million Africans by 2030. Fifty-nine million people have gained access so far, with annual progress accelerating from 12 million in the 2024 financial year to 28 million last year.
Its water programme aims to improve security for as many as one billion people by 2030, including a World Bank commitment covering 400 million. AgriConnect seeks to move 300 million smallholder farmers from subsistence to surplus, while HealthWorks aims to extend affordable, quality healthcare to 1.5 billion people.
Execution will determine whether these ambitions become transformation or merely larger project pipelines. Faster internal processes offer some grounds for confidence. The Bank has reduced project preparation time from 19 months to nine, replaced 153 scorecard indicators with 22 impact-focused measures and increased results-based financing from roughly one-third to half.
The more radical proposal is to create an emerging-market development asset class. Six multilateral banks are developing common methods to assess, document, package and transfer investments to pension funds, insurers and sovereign wealth funds. Selling seasoned assets could release institutional capital for new projects instead of leaving it committed for decades.
That model could stretch every development dollar further, but standardisation must not obscure differences among countries or transfer risks without transparency. The credibility of the asset class will depend on project quality, reliable data and fair allocation of returns and losses.
Banga’s central proposition is ultimately that development finance should evolve as countries do. Public and concessional funding should dominate where risks are greatest; private markets should assume a larger role as institutions and economies strengthen. Success arrives when countries no longer require the Bank.
The institution has demonstrated greater financial capacity and faster mobilisation. Its harder task is proving that larger numbers produce better livelihoods. The projected jobs deficit is not inevitable, but closing it requires infrastructure, enterprise, skills and capital to converge around employment.
The World Bank’s future will therefore be judged less by how much it lends than by whether young people can find productive places in the economies its financing helps build.

