


- BoG Governor Flags Cedi Risks as Ghana Develops Stablecoin Rules
Ghana’s effort to develop a regulated virtual asset market will need to balance the promise of faster, cheaper financial services with the risk that foreign currency stablecoins could weaken confidence in the cedi, Bank of Ghana Governor Dr Johnson Pandit Asiama has warned.
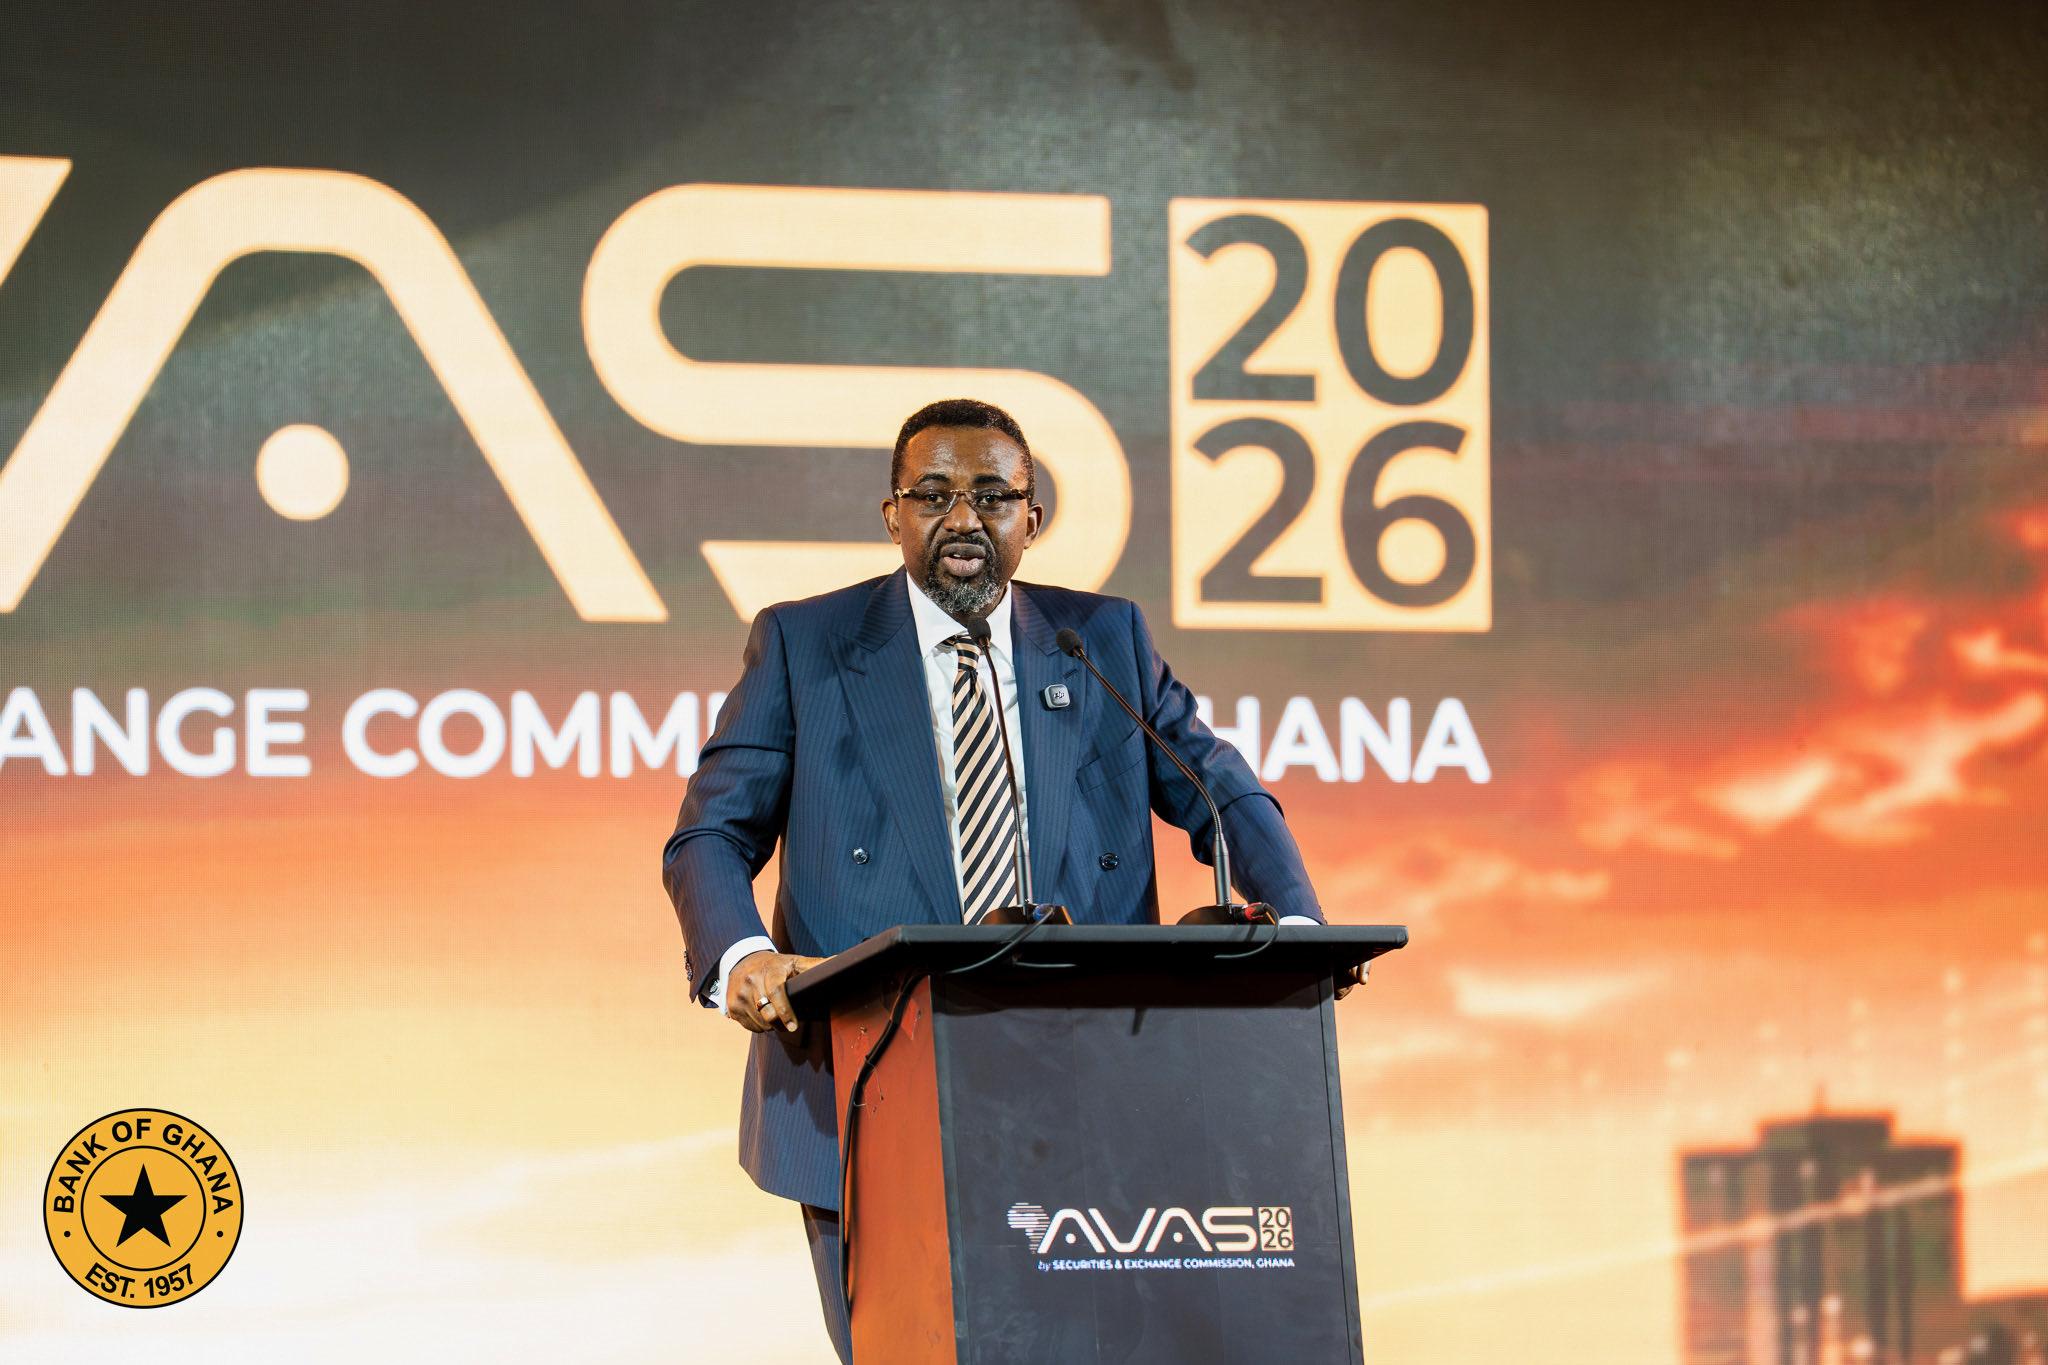
Speaking at the Africa Virtual Assets Summit in Accra on Monday, November 2, Dr Asiama said stablecoins could improve payments and settlement, but their expanding use, particularly those denominated in foreign currencies, could affect monetary sovereignty, capital flows and the effectiveness of monetary policy.
The central bank’s position, as set out in the Governor’s goodwill message, is not to shut out digital finance. It is to ensure that innovation does not undermine the stability and public confidence on which the financial system depends.
“Trust is not the opposite of innovation; it is what allows innovation to grow,” Dr Asiama said.
That balance will shape the next phase of Ghana’s digital finance market. The country already has a large digital payments base: mobile money platforms processed more than one billion transactions worth about GH¢519 billion in August 2026 alone, according to the Governor.
The scale of that activity presents a foundation for new financial services, but virtual assets bring different risks from mobile money, including questions about custody, investor protection and the relationship between digital tokens and national currencies.
Dr Asiama said virtual assets and tokenisation could help address barriers that have long constrained African markets, including limited access to capital, high transaction costs, fragmented financial infrastructure and obstacles to cross-border payments.
He pointed to the possibility of faster and less costly diaspora remittances, as well as digital settlement to support trade under the African Continental Free Trade Area.
Tokenisation could extend those uses by representing ownership of, or rights to, assets such as securities, commodities and trade receivables in digital form.
In principle, that could allow a small exporter to secure financing earlier, reduce settlement times and give smaller enterprises more ways to raise capital.
The potential is significant, but it depends on whether digital systems solve practical economic problems. A tokenised claim on an asset must be legally enforceable and trusted by investors.
Faster settlement is useful only if the parties can verify ownership, recover funds in the event of a dispute and rely on the value represented by the token. Dr Asiama’s emphasis on governance reflects the gap between technological possibility and a functioning market.
Stablecoins bring that tension into sharper focus. These digital tokens are designed to maintain a stable value, often by being linked to a national currency such as the US dollar.
Their use can make digital transfers easier, but a rise in foreign currency stablecoins could encourage people and businesses to hold or transact in dollars rather than cedis.
The Governor said that trend could have implications for “monetary sovereignty, currency substitution, capital flows and the effectiveness of monetary policy.”
The concern is not simply the existence of a new payment channel; it is whether the growing use of privately issued digital money changes how much economic activity is conducted in the national currency and how effectively policy decisions influence financial conditions.
Dr Asiama did not call for heavy-handed regulation. He said virtual asset activities carry different levels of risk and that oversight should reflect their nature, scale and complexity. But he identified consumer and investor protection, safeguarding customer assets, financial integrity and sound connections with the traditional financial system as essential conditions for trust.
Ghana has begun building a legal framework. The Virtual Asset Service Providers Act, 2025 (Act 1154), establishes a dedicated basis for regulating virtual asset activities, with coordinated responsibilities for the Bank of Ghana and the Securities and Exchange Commission.
The law is an important starting point, but the Governor said implementation would determine whether firms and investors receive the certainty needed to operate responsibly.
The Bank of Ghana is developing a Stablecoin Directive to set requirements for stablecoin activities and clarify which activities may be permitted. It is also working with the SEC and the Financial Intelligence Centre on regulatory instruments and supervisory arrangements.
The inauguration of a Virtual Assets Coordinating Committee is intended to support cooperation among public institutions.
This coordination will matter because virtual asset markets cut across financial regulation, securities, payments and financial crime prevention. If rules are unclear or agencies work at cross purposes, firms may face uncertainty while consumers remain exposed to risks. Conversely, clear requirements can help distinguish responsible providers from businesses that do not adequately protect customers or their assets.
The challenge for regulators will be to define what responsible activity looks like without freezing useful innovation. Rules that are too weak could leave customers exposed to losses, fraud or unstable products.
Requirements that are poorly calibrated could make it harder for smaller firms to enter the market, narrowing the potential benefits of digital finance to a handful of established operators.
The Governor’s vision is a financial system that can serve a trader in Kumasi, a cocoa farmer and a developer in Accra with services that are faster, cheaper and safer. Achieving that outcome will require more than authorising new products.
It will depend on whether users understand the risks, whether customer funds are protected and whether digital platforms can work reliably with existing financial institutions.
The regulatory framework is therefore becoming a test of Ghana’s capacity to turn digital finance into an economic tool while preserving confidence in the cedi. The country’s mobile money experience shows that new financial channels can be adopted at scale.
The next stage will require regulators to show that virtual assets can expand access and lower costs without creating vulnerabilities that outweigh those gains.
The law, the proposed Stablecoin Directive and inter-agency coordination provide an initial structure. The harder work lies ahead: translating them into enforceable rules that are clear to firms, credible to investors and protective of users.
As Dr Asiama put it, Ghana’s task is not simply to build a digital asset market, but an ecosystem “safe enough to be trusted, inclusive enough to serve our people, and innovative enough to support Africa’s future.”

