


- CBN–NNPC Deal Targets a Weak Link in Nigeria’s Foreign-Exchange Pipeline
Nigeria’s latest attempt to strengthen the naira begins with a question that has shadowed its economic reforms for years: how reliably does the country turn oil exports into usable foreign exchange?
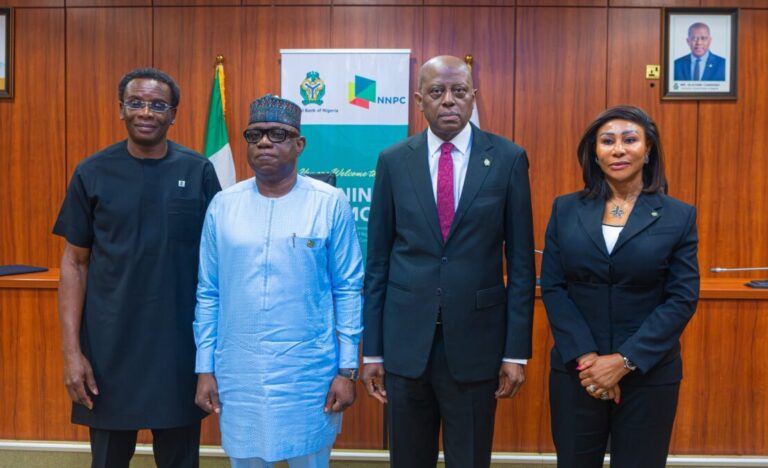
The Central Bank of Nigeria and state oil company NNPC Ltd have signed a memorandum of understanding to coordinate foreign-exchange flows, energy financing and the management of oil and gas proceeds.
The agreement, signed in Abuja on November 18, is intended to formalise cooperation between institutions whose decisions can shape the timing and visibility of the country’s dollar earnings.
That coordination matters. But the agreement should not be mistaken for a new supply of dollars. No specific financing package, foreign-exchange injection or immediate increase in export receipts was announced.
Its value will depend on whether a more structured relationship can improve the way existing and future petroleum earnings are managed, converted, repatriated and reported.
The CBN has identified predictable foreign-exchange inflows and better management of oil revenue as important to economic and currency stability. NNPC’s chief executive, Bayo Ojulari, said the arrangement should strengthen the management and repatriation of proceeds from oil and gas exports.
The institutions also intend to work together on energy project financing and attracting investment into gas projects.
In practice, the pact is an effort to improve the connection between Nigeria’s most important source of export earnings and the financial system responsible for managing foreign exchange. That connection is consequential for the naira, but it is only one part of a much larger problem.
Nigeria’s oil earnings depend not just on global prices, but on production volumes, export performance, costs, payment arrangements and the point at which proceeds become available to the country.
A more predictable flow could help reduce uncertainty in foreign-exchange planning. It could also make it easier for the government and the central bank to distinguish between expected petroleum receipts and dollars that are actually available.
That distinction matters when the country is managing import demand, reserve adequacy and pressure on the exchange rate.
But better coordination cannot compensate for oil that is not produced or revenue that does not arrive.
The agreement’s impact will therefore be measured less by its announcement than by what happens to the flow of receipts afterward: whether export proceeds are captured and repatriated on time, whether transfers are transparent, and whether the resulting foreign exchange reaches the relevant public accounts and markets as expected.
The announced areas of cooperation point to some of the practical obstacles. They include energy financing, how the country earns and manages oil and gas revenue, financial and payment systems, and investment in gas projects.
Further details reported on the proposed framework include operational coordination, payment automation, risk management and closer alignment between the institutions.
These are not peripheral administrative issues. If payments and approvals are slow, or if the records held by public institutions do not reconcile quickly, policymakers may have an incomplete picture of the country’s external cash position.
Better systems could reduce that lag and make the timing of oil receipts easier to track. That would improve information and accountability, although it would not by itself increase production or guarantee more dollars.
The CBN’s account-custody role makes that distinction especially important. A functioning arrangement should clarify how export earnings move through the system, who is responsible at each stage, and how the proceeds are accounted for. The goal is not simply to have more institutional contact, but to make the flow of funds more visible and dependable.
Nigeria’s production ambitions underline the scale of the challenge. NNPC has spoken of increasing crude output from about 1.8 million barrels a day to 3 million barrels a day, while also seeking to unlock the country’s gas potential.
That is a corporate target, not an outcome secured by the new agreement. Reaching it would require sustained investment, reliable infrastructure, operational security and projects that can withstand commercial and regulatory scrutiny.
This is where the foreign-exchange objective meets the energy-sector reality. A framework that improves proceeds management can make existing production more financially useful.
Yet the larger and more durable gains would come from producing and exporting more, while ensuring that the revenue is captured by transparent systems. If output remains constrained, the agreement may improve the handling of a limited pool of dollars without materially changing its size.
The financing ambition also raises questions about risk. Bringing investors and international institutions into gas projects may help close funding gaps, but project finance requires clear commercial terms, credible revenue forecasts and defined responsibilities.
The MoU can create a channel for coordination; it does not settle the financing, governance or execution questions that determine whether a project proceeds.
There is a broader institutional test, too. The more closely the central bank and NNPC coordinate, the more important it becomes to maintain clear reporting lines and public accountability.
Cooperation should make the flow of petroleum earnings easier to scrutinise, not harder to distinguish across agencies and accounts. Regular reporting on expected receipts, actual receipts, repatriation and transfers would help demonstrate whether the agreement is changing practice.
The significance of the pact, then, is neither trivial nor transformative on its own. It addresses a real weakness: the distance between generating export revenue and managing that revenue in a way that supports macroeconomic stability. But a memorandum cannot create the underlying dollars. Production, investment and disciplined revenue handling still have to do that work.
For the naira, the immediate question is whether the new framework can make oil-related foreign-exchange inflows more predictable. For the energy sector, the question is whether it can support credible investment and increase output. For the public, the more fundamental question is whether a country rich in petroleum can make its earnings more transparent and useful to the wider economy.
The agreement has opened a door. Its credibility will rest on what passes through it: measurable improvements in reporting and repatriation, sound energy financing, and eventually more reliable production.
Until those results appear, Nigeria has a new coordination framework but not yet a new stream of foreign exchange.

