


- Central Bank Governor Urges Banks to Strengthen Risk Controls as Sector Recovery Gathers Pace
The Bank of Ghana has urged commercial banks to strengthen their risk-management systems, governance structures and business models, warning that recent improvements in financial stability must not encourage complacency.
Governor Johnson Pandit Asiama said Ghana’s banking sector had recorded progress through stronger capital positions, improved financial stability and a decline in non-performing loans. However, preserving those gains would require banks to build institutions capable of absorbing economic shocks and responding to rapid technological and market changes.
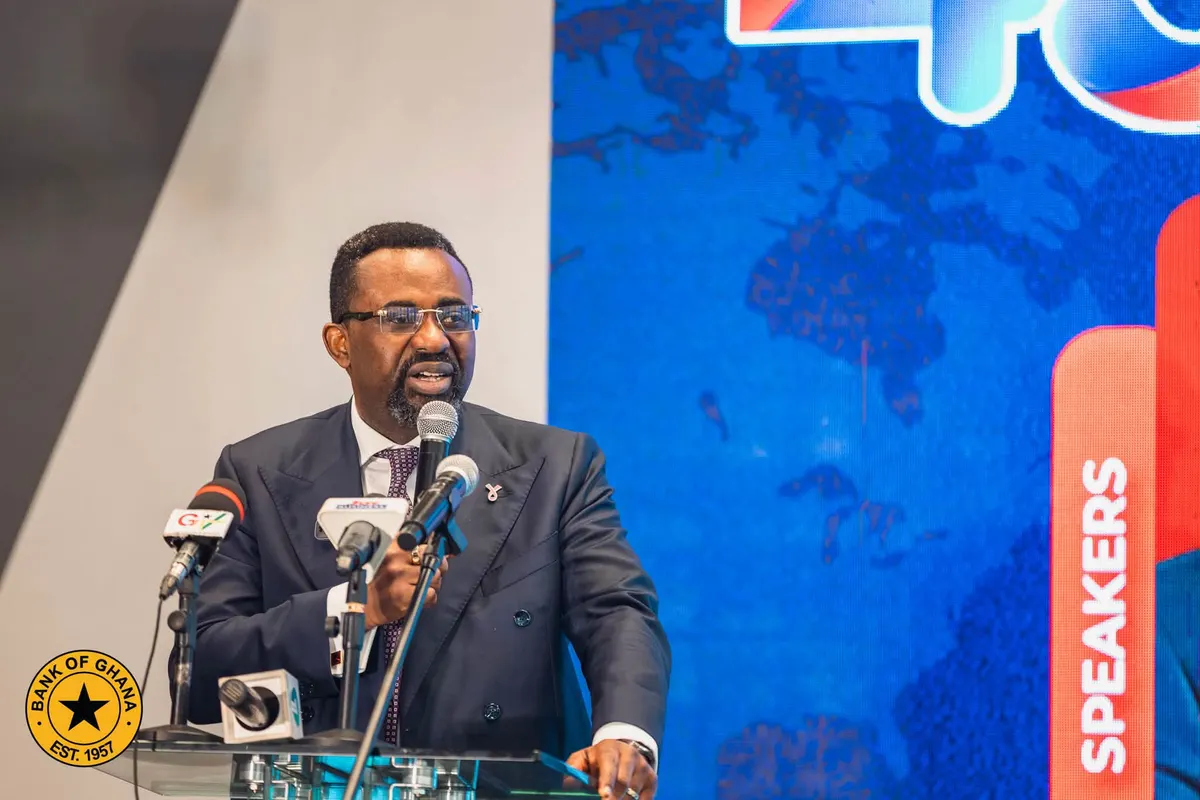
Speaking at the 43rd Annual General Meeting of the Ghana Association of Banks and the launch of the sixth edition of the Ghana Bankers’ Voice Magazine in Accra on October 8, Dr Asiama called for greater attention to prudent risk management, sound governance and innovation.
“Our ambition should be to build a banking sector that is strong enough to absorb shocks, innovative enough to adapt to change, and capable of financing Ghana’s long-term economic transformation,” he said.
The message reflects a difficult balancing act confronting Ghana’s banking industry. Banks are being encouraged to increase lending to businesses and support economic recovery, but faster credit expansion could recreate asset-quality problems if underwriting standards and loan-monitoring systems do not improve at the same pace.
Private-sector credit expanded by 35.5 per cent in August 2026, compared with 13.3 per cent a year earlier. In real terms, credit growth reached 29 per cent, up sharply from 1.7 per cent over the same period in 2025.
The acceleration followed a decline in the average lending rate to 15.9 per cent in August 2026 from 24.2 per cent a year earlier, alongside improving credit demand.
While this represents a potentially important reopening of financing to businesses, it also increases the need for banks to assess borrowers carefully. Rapid balance-sheet growth can boost short-term earnings but create future losses if loans are approved without adequate analysis of cash flows, sector exposure and repayment capacity.
The central bank’s concern is therefore not that lending is increasing, but that the recovery must be supported by disciplined credit origination, administration, monitoring and recovery.
The BoG is preparing a credit-risk management directive that will broaden the framework governing these areas. It is also developing a liquidity coverage ratio directive requiring banks to hold sufficient high-quality liquid assets to withstand a significant 30-day liquidity shock.
These measures suggest that the regulator wants banks to prepare for stress while economic conditions remain relatively favourable. That approach is significant because financial vulnerabilities are often accumulated during periods of optimism, when institutions expand credit and underestimate the possibility of renewed macroeconomic volatility.
The Governor has also asked banks to address weaknesses identified through the BoG’s macroprudential stress tests and strengthen fraud controls, cybersecurity systems and liquidity-management arrangements.
Digitalisation has improved access to financial services and reduced transaction costs, but it has also expanded the banking system’s exposure to cyberattacks, identity theft, payment fraud and operational disruption.
Effective risk management must consequently extend beyond the traditional focus on loan defaults. Banks must now manage interconnected credit, liquidity, technology, fraud, foreign-exchange and reputational risks.
The central bank has already directed financial institutions to ensure that fraud-control units have direct and unrestricted access to managing directors or chief executives. The intention is to protect the independence of fraud investigations and prevent serious cases from being blocked or diluted by middle management.
For bank boards, Dr Asiama’s intervention places responsibility for resilience at the highest level of governance. Risk management cannot remain a compliance exercise handled solely by internal audit and risk departments. It must influence lending targets, technology expenditure, staff incentives and the pace at which institutions expand into new products.
The warning is particularly relevant as banks rebuild following the effects of Ghana’s domestic debt restructuring and seek new sources of earnings. Stronger capital ratios offer an important cushion, but capital by itself cannot compensate indefinitely for weak credit decisions, poor governance or inadequate operational controls.
The BoG said it would continue working with banks and other stakeholders to build a resilient, innovative and sustainable financial system capable of supporting economic development.
The real test will be whether banks can convert improving balance sheets into productive credit without allowing the next generation of non-performing loans to develop beneath the current recovery.

