


- Ethiopia Opens US$50 Million Gold Refinery in Race to Retain Mineral Value
Ethiopia has entered Africa’s intensifying contest to process gold at home, opening its first national precious-metals refinery as governments across the continent seek to replace the export of raw minerals with domestic value addition.
The US$50 million facility, located within the Bole Lemi Special Economic Zone, was developed through a partnership between state-owned Ethiopian Investment Holdings and Sam Precious Metals. Ethiopian Investment Holdings holds 51 per cent, while its private-sector partner controls 49 per cent.
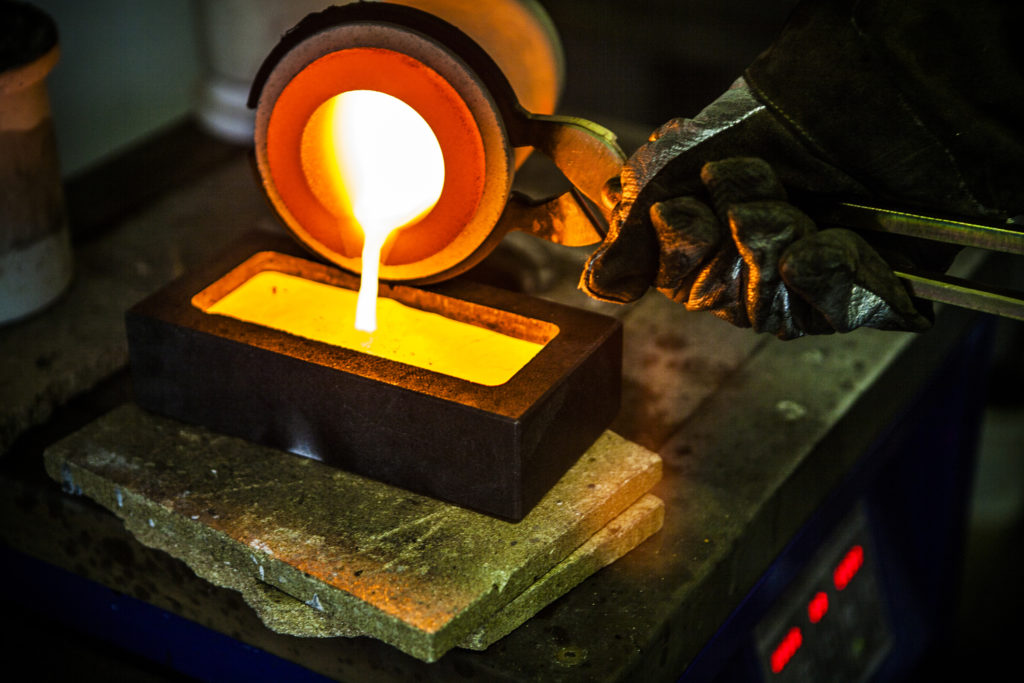
At full capacity, the refinery can process more than 600 tonnes of precious metals annually. Its services include assaying, melting, refining and casting gold, as well as producing export-ready gold and silver bars. This gives Ethiopia the infrastructure to certify purity, standardise bullion and capture activities that previously occurred abroad.
The headline capacity requires careful interpretation. The 600-tonne figure covers precious metals rather than gold alone and represents maximum processing capability, not guaranteed annual throughput. Ethiopia’s achievement will therefore be measured by how much responsibly sourced metal the refinery attracts, how consistently it operates and how much additional income remains within the domestic economy.
Prime Minister Abiy Ahmed presented the project as part of a broader effort to end dependence on exporting unprocessed resources. He said it would allow neighbouring countries and mining businesses to refine, certify and sell their gold in Ethiopia, “eliminating the need to export it outside the continent”.
That regional ambition matters because the refinery is considerably larger than Ethiopia’s current formal gold supply requires. Its commercial model depends not only on domestic mining growth, but on convincing producers elsewhere in Africa that Ethiopia offers credible certification, competitive fees, reliable logistics and rapid settlement.
Gold has become important to Ethiopia’s external position. Official figures place export earnings from the sector at about US$5.5 billion during the 2025/26 financial year. Processing more of that output locally could reduce refining charges paid overseas, improve foreign-exchange capture and provide the government with better information about production, quality and exports.
The refinery may strengthen the jewellery industry, create technical jobs and support services in logistics, security, testing and finance. Yet these gains are not automatic. Refining is a relatively narrow segment of the gold value chain, and the largest benefits will emerge only if Ethiopia develops mining, fabrication, jewellery production, trading and financial products around the facility.
Ethiopia is not pursuing this strategy alone. Burkina Faso inaugurated its RAFFINOR-BF refinery in September, beginning with capacity of 164 tonnes annually and plans to expand to 515 tonnes. President Ibrahim Traoré framed the project as an effort to retain the entire minerals value chain locally instead of merely extracting resources for processing abroad.
Ghana, Mali and Guinea are also pursuing domestic refining ambitions. Ghana has moved to connect GoldBod’s purchasing system with local processing and international technical expertise, while Guinea has positioned its new facility to serve regional producers. The result is a rapidly changing African bullion map in which refining capacity may soon grow faster than the supply of traceable feedstock.
That creates both opportunity and risk. For decades, African gold-producing countries exported doré to established centres outside the continent, surrendering refining fees, market intelligence and some industrial opportunities. Local refineries can reverse part of that leakage, but several large plants competing for the same regional gold could operate below capacity unless mining output and formal purchases expand substantially.
The crucial battle will be over trust. International buyers require confidence that bullion meets exact purity, traceability and responsible-sourcing standards. A refinery may possess modern equipment, but without internationally recognised accreditation, credible audits and strong anti-money-laundering controls, its bars may struggle to command acceptance in major markets.
This challenge is particularly important where artisanal and small-scale mining contributes significantly to supply. Informal gold flows can involve smuggling, environmental damage, unsafe labour and opaque ownership. Ethiopia must therefore combine commercial incentives for miners with stringent due diligence. If formal channels pay competitively and promptly, they can attract supply; if bureaucracy delays payment or official prices are unattractive, metal will continue moving through informal routes.
Regional competition could nevertheless produce benefits. Refineries will have to compete on cost, turnaround time, transparency and access to buyers. Producers may gain better terms, governments may improve export oversight and African bullion could reach global markets with more value already added. The strongest facilities could become anchors for regional trading and manufacturing clusters.
Ethiopia’s location offers strategic advantages. Addis Ababa is a diplomatic and aviation hub, while the Bole Lemi zone provides an industrial setting near transport links. But landlocked geography also raises security and logistics costs. Moving high-value metal across borders requires dependable customs procedures, specialised insurance and close cooperation between regulators, banks and law-enforcement agencies.
Financing will be equally important. Refiners often need substantial working capital to purchase material, pay suppliers quickly and hold inventory during processing. Ethiopia must ensure that foreign-exchange rules and banking arrangements do not undermine the speed and certainty required by regional clients. A refinery designed as a continental hub cannot function efficiently if payments, imports of equipment or exports of bullion face unpredictable administrative delays.
The project should therefore be judged against practical indicators: utilisation rates, volumes sourced transparently, price premiums achieved, foreign exchange retained, skilled jobs created and downstream businesses established. Capacity alone is not industrial policy, and a ribbon-cutting ceremony does not guarantee transformation.
Still, the refinery marks an important shift in Ethiopia’s economic thinking. It treats gold not merely as a commodity to be extracted but as the foundation of a broader industrial, financial and export ecosystem. The state’s majority ownership also gives government influence over strategy, although it increases the need for transparent governance, professional management and public reporting.
Africa’s gold-refining expansion expresses a legitimate demand for greater control over resources. But sovereignty is created by competitive institutions, credible standards and profitable operations, not machinery alone. Ethiopia has built the platform; its next task is to prove that the refinery can attract metal, earn international confidence and convert mineral wealth into durable national value across its wider domestic economy.

