


- GUTA Backs VAT Enforcement but Warns Against Heavy-Handed Treatment of Businesses
Ghana’s renewed push to improve Value Added Tax compliance is exposing a difficult policy balance for the country’s revenue authorities: how to recover billions of cedis in foregone tax revenue without turning enforcement into another source of pressure for businesses already operating in a challenging trading environment.
The Ghana Union of Traders’ Associations has therefore urged the Ghana Revenue Authority to adopt what it describes as a more measured and business-friendly approach as a nationwide VAT compliance campaign gets underway.
GUTA says enforcement should be accompanied by education, cooperation and respectful engagement with traders.
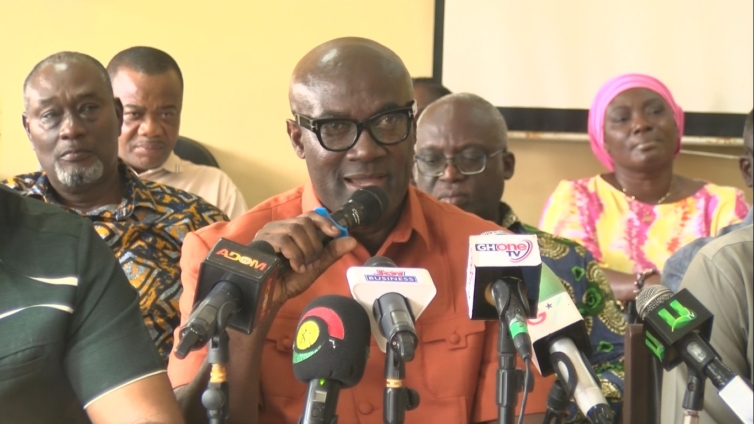
“What I will entreat GRA to do is to attach a human face when the time comes for them to go to the market for the exercise,” GUTA President Clement Boateng said at the launch of the campaign on September 22. He added that officers deployed to markets should be “friendly and accommodative” while carrying out their responsibilities.
The intervention comes as the GRA seeks to close a significant gap between the VAT Ghana could potentially collect and the amount that actually reaches the state.
The authority says Ghana currently has about 60,000 active VAT taxpayers but collects only around 40.00% of potentially recoverable VAT, implying a compliance gap of roughly 60.00%.
That makes the enforcement drive fiscally significant because VAT remains one of the country’s principal sources of domestic revenue and helps finance public expenditure across infrastructure, education, healthcare and security.
The size of the gap also suggests that stronger collections could generate substantial revenue without necessarily introducing a new tax.
GUTA is not opposing the campaign itself. Mr Boateng said the association would encourage its members to cooperate with the exercise and support efforts to improve Ghana’s tax-to-GDP ratio.
“GUTA on our part will also encourage our members to be cooperative so that together we will have a smooth program and improve on our tax to GDP ratio for the betterment of Mother Ghana,” he said.
The distinction is important because tax enforcement can generate immediate compliance when officers visit businesses, but a sustainable revenue system depends on taxpayers complying routinely rather than only when they fear inspection.
That means the effectiveness of the campaign will depend not only on how many businesses are sanctioned but on whether taxpayers understand their obligations and regard the system as predictable and fair. GUTA’s position is therefore that voluntary compliance should remain central even as enforcement becomes more intensive.
The GRA itself says the campaign will combine education, engagement and enforcement. Dr Martin Kolbil Yamborigya, Commissioner of the Domestic Tax Revenue Division, said the authority plans to use compliance visits, risk-based audits, data-driven assessments and expanded taxpayer education, with tougher measures reserved for businesses that deliberately and persistently fail to comply.
“This campaign is not meant to harass businesses and we don’t also intend to disadvantage any business,” he said.
The authority has set an ambitious target of reducing the VAT gap from about 60.00% currently to roughly 30.00% by the end of 2028.
Achieving that would require a substantial increase in tax collected from economic activity already taking place, while also bringing more eligible businesses fully into the system.
The scale of the target makes administration, taxpayer education and technology as important as physical enforcement.
The campaign is being implemented under a substantially revised VAT framework. Under the VAT Act, 2025, which took effect on January 1, 2026, the registration threshold for businesses dealing in goods was raised from GH¢200,000 to GH¢750,000, while the COVID-19 Health Recovery Levy was abolished.
The VAT rate remains 15.00%, with the 2.50% National Health Insurance Levy and 2.50% GETFund Levy producing an effective rate of 20.00%, while the VAT Flat Rate Scheme has also been abolished.
Those reforms were intended partly to simplify the VAT system and encourage voluntary compliance, making the subsequent enforcement drive an important test of whether the redesigned framework can translate into stronger collections.
For traders, the challenge is not simply whether VAT should be paid but whether businesses understand who must register, how VAT invoices should be issued, how returns should be filed and how taxes collected from customers should be accounted for. Confusion around those obligations can itself become a source of non-compliance.
Consumer behaviour is another important part of the compliance equation. Mr Boateng urged the GRA to intensify education around incentives for consumers who demand VAT invoices after purchases, arguing that customers can become part of the enforcement ecosystem.
“I will also urge GRA to include in their education the incentive that will be given to consumers who demand VAT invoices after their purchase,” he said.
If consumers routinely insist on valid VAT invoices, businesses face a stronger incentive to record sales correctly and account for the tax collected.
The GRA is also placing greater emphasis on technology and data analytics to identify businesses operating outside the VAT system and improve registration, filing and payment processes. Over time, a system capable of matching business registrations, invoices and transaction data could allow enforcement to become more targeted rather than relying predominantly on broad physical inspections.
That makes trust an important part of the revenue strategy. Where businesses genuinely misunderstand the rules, education may generate compliance at a lower economic and administrative cost, while deliberate evasion still requires enforcement to protect businesses that pay their taxes from unfair competition.
The “human face” requested by GUTA therefore does not mean abandoning enforcement, but distinguishing between error, incapacity and intentional non-compliance.
For Ghana, the stakes are larger than the immediate VAT campaign. Closing even part of the compliance gap could materially strengthen domestic revenue mobilisation at a time when government needs more internally generated resources to finance development priorities and reduce dependence on additional taxation or borrowing.
But the durability of those gains will depend on making compliance a normal feature of commercial activity rather than an occasional response to enforcement exercises.
The success of the campaign will therefore be measured in more than additional revenue. It will also depend on whether traders and consumers view the system as understandable, predictable and fairly administered, and whether the GRA can increasingly use data rather than confrontation to identify genuine non-compliance.
If that balance is achieved, Ghana could narrow its VAT gap while strengthening rather than weakening the relationship between the state and the businesses from which future revenue must come.

