

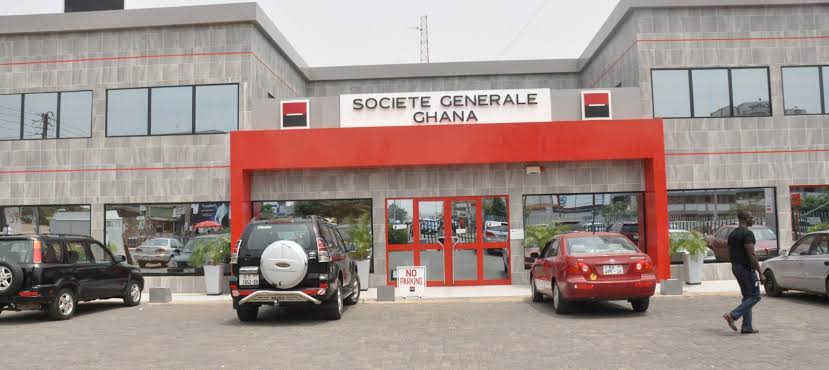

- Societe Generale Exits Ghana as Attijariwafa Takes Control in Landmark Bank Deal
Societe Generale Group has agreed to sell its entire 60.22 per cent interest in Societe Generale Ghana, bringing an end to more than two decades of French control of the locally listed bank and opening the door to one of Morocco’s largest financial groups.
Under the agreement, Attijariwafa Bank will acquire 55.22 per cent of Societe Generale Ghana, while the Social Security and National Insurance Trust will purchase an additional 5 per cent.
The transaction will give Attijariwafa a controlling interest in the Ghanaian bank, subject to regulatory and other required approvals in Ghana and Morocco.
The value of the transaction was not disclosed.
Attijariwafa is expected to take over all the activities of Societe Generale Ghana, including its customer portfolios and employees, according to a statement released through the Ghana Stock Exchange on Thursday.
“This divestment project is subject to the usual conditions precedent and the validation of the relevant financial and regulatory authorities,” Societe Generale Ghana said.
The proposed transaction represents a significant change in Ghana’s banking sector: one multinational institution is withdrawing while another African banking group is using an established local platform to enter one of West Africa’s more competitive financial markets.
Societe Generale Ghana operates a network of 40 branches and outlets and serves retail, small business and corporate customers.
The bank had more than 500 employees and operated in 24 cities at the end of 2025, according to information released in connection with the transaction.
It reported net banking income of GH¢1.36bn, net profit of GH¢397m, total assets of GH¢9.7bn and shareholders’ equity of GH¢2.6bn for 2025.
The bank’s market capitalisation stood at about GH¢3.9bn on September 29, 2026.
At that quoted market value, Societe Generale Group’s full 60.22 per cent stake would have an indicative stock-market value of about GH¢2.35bn. Attijariwafa’s proposed 55.22 per cent interest would be worth approximately GH¢2.15bn, while the additional 5 per cent allocated to SSNIT would have an indicative value of GH¢195mn.
These calculations are not the agreed transaction price, which remains undisclosed. The final consideration could reflect a control premium, negotiations over the bank’s assets and liabilities and other conditions contained in the sale agreement.
Societe Generale Ghana’s shares closed at GH¢5.18 on September 30 after declining by GH¢0.32 during the session. Investors will now be watching how the market prices the change of control and whether further information is released about the agreed valuation.
SSNIT’s participation gives the transaction an important domestic institutional dimension.
The pension fund is already a shareholder in several Ghanaian banks and listed companies. Its acquisition of an additional 5 per cent of Societe Generale Ghana will increase local institutional ownership as the French parent withdraws.
The announcement did not disclose SSNIT’s resulting total shareholding or the price it will pay.
That information will matter to pension contributors and minority shareholders. As the transaction progresses, SSNIT will be expected to explain the commercial rationale, valuation methodology and anticipated return on the investment.
The fund’s participation could provide continuity during the transition and strengthen the new controlling shareholder’s relationship with a significant Ghanaian institutional investor.
It also raises broader governance questions. Where a public pension institution expands its stake alongside a new foreign controlling shareholder, transparency around pricing, board representation and the protection of minority investors becomes particularly important.
The acquisition will give Attijariwafa an immediate banking licence, customer base, branch network, employees and corporate relationships in Ghana.
Created through the merger of Banque Commerciale du Maroc and Wafabank, Attijariwafa is Morocco’s largest bank and ranks among Africa’s biggest financial institutions by assets.
The group said the acquisition formed part of its African expansion strategy and would strengthen its presence in English-speaking markets.
Mohamed El Kettani, chair and chief executive of Attijariwafa Bank, said the agreement reflected the group’s confidence in Ghana’s economic prospects and the quality of Societe Generale Ghana.
“The signing of this agreement reflects the confidence we have in Ghana’s development prospects as well as in the quality of Societe Generale Ghana,” he said.
“We are convinced that our institution’s expertise and our long and successful experience in integrating acquired banks into our group will enable us to continue the development of Societe Generale Ghana for the benefit of its customers, employees and all its partners.”
The strategy differs from establishing a new bank from the ground up, which would require Attijariwafa to build a customer base, recruit staff and establish distribution infrastructure.
Acquiring an established universal bank provides immediate scale. The challenge will be integrating Societe Generale Ghana into the Moroccan group without disrupting customer relationships or weakening the operational standards developed under its former parent.
The statement provides an explicit assurance that Attijariwafa will take over the bank’s operations, client portfolios and employees.
This means the transaction is structured as a change in controlling ownership rather than the closure of the bank or sale of isolated assets.
For customers, existing deposits, loans and banking relationships will remain with the institution during the approval process.
Nevertheless, a change of multinational parent could eventually affect branding, technology, product development, corporate governance and cross-border banking relationships.
Attijariwafa may seek to connect the Ghanaian operation to its wider African network, potentially creating new opportunities in trade finance, payments, investment banking and transactions linking Ghana with North, West and Central Africa.
Employees will be watching for clarity on management, integration and the future operating model. Although the buyer has agreed to take over the workforce, banking acquisitions frequently involve changes in organisational structure, technology and reporting lines.
The ability to manage that transition without losing key personnel or disrupting customer service will be one of the transaction’s early tests.
Completion remains conditional on approvals from the relevant financial, regulatory and stock-market authorities.
In Ghana, the Bank of Ghana will have to assess the suitability and financial strength of the proposed controlling shareholder, the implications for the bank’s governance and capital and the broader effects on financial stability.
The Securities and Exchange Commission and Ghana Stock Exchange will also have an interest because Societe Generale Ghana is publicly listed and minority shareholders must receive timely and complete information about a material change in control.
Regulators in Morocco will examine the transaction from the perspective of Attijariwafa’s capital position and cross-border expansion.
Until these conditions are satisfied, Societe Generale Group remains the controlling shareholder.
The announcement does not provide a proposed completion date or indicate whether the Societe Generale name will remain after the acquisition.
The transaction is part of a broader reordering of African banking in which some European institutions are reducing their direct presence while large African banking groups expand across the continent.
For Ghana, the immediate question is not simply why Societe Generale is leaving. It is what Attijariwafa intends to build with the franchise it is acquiring.
Societe Generale entered the Ghanaian bank in 2004 with a 51 per cent controlling interest, when the institution was known as Social Security Bank, before gradually increasing its shareholding and rebranding the business.
The proposed sale therefore closes one long chapter in the bank’s ownership and begins another.
If approved, the transaction will leave Societe Generale Ghana with an African controlling shareholder, a strengthened pension-fund investor and the same local operating platform.
The ownership nationality may be changing, but the commercial test remains the same: whether the new structure delivers stronger capital, better technology, broader regional connections and sustainable value for customers, employees and minority shareholders.

