

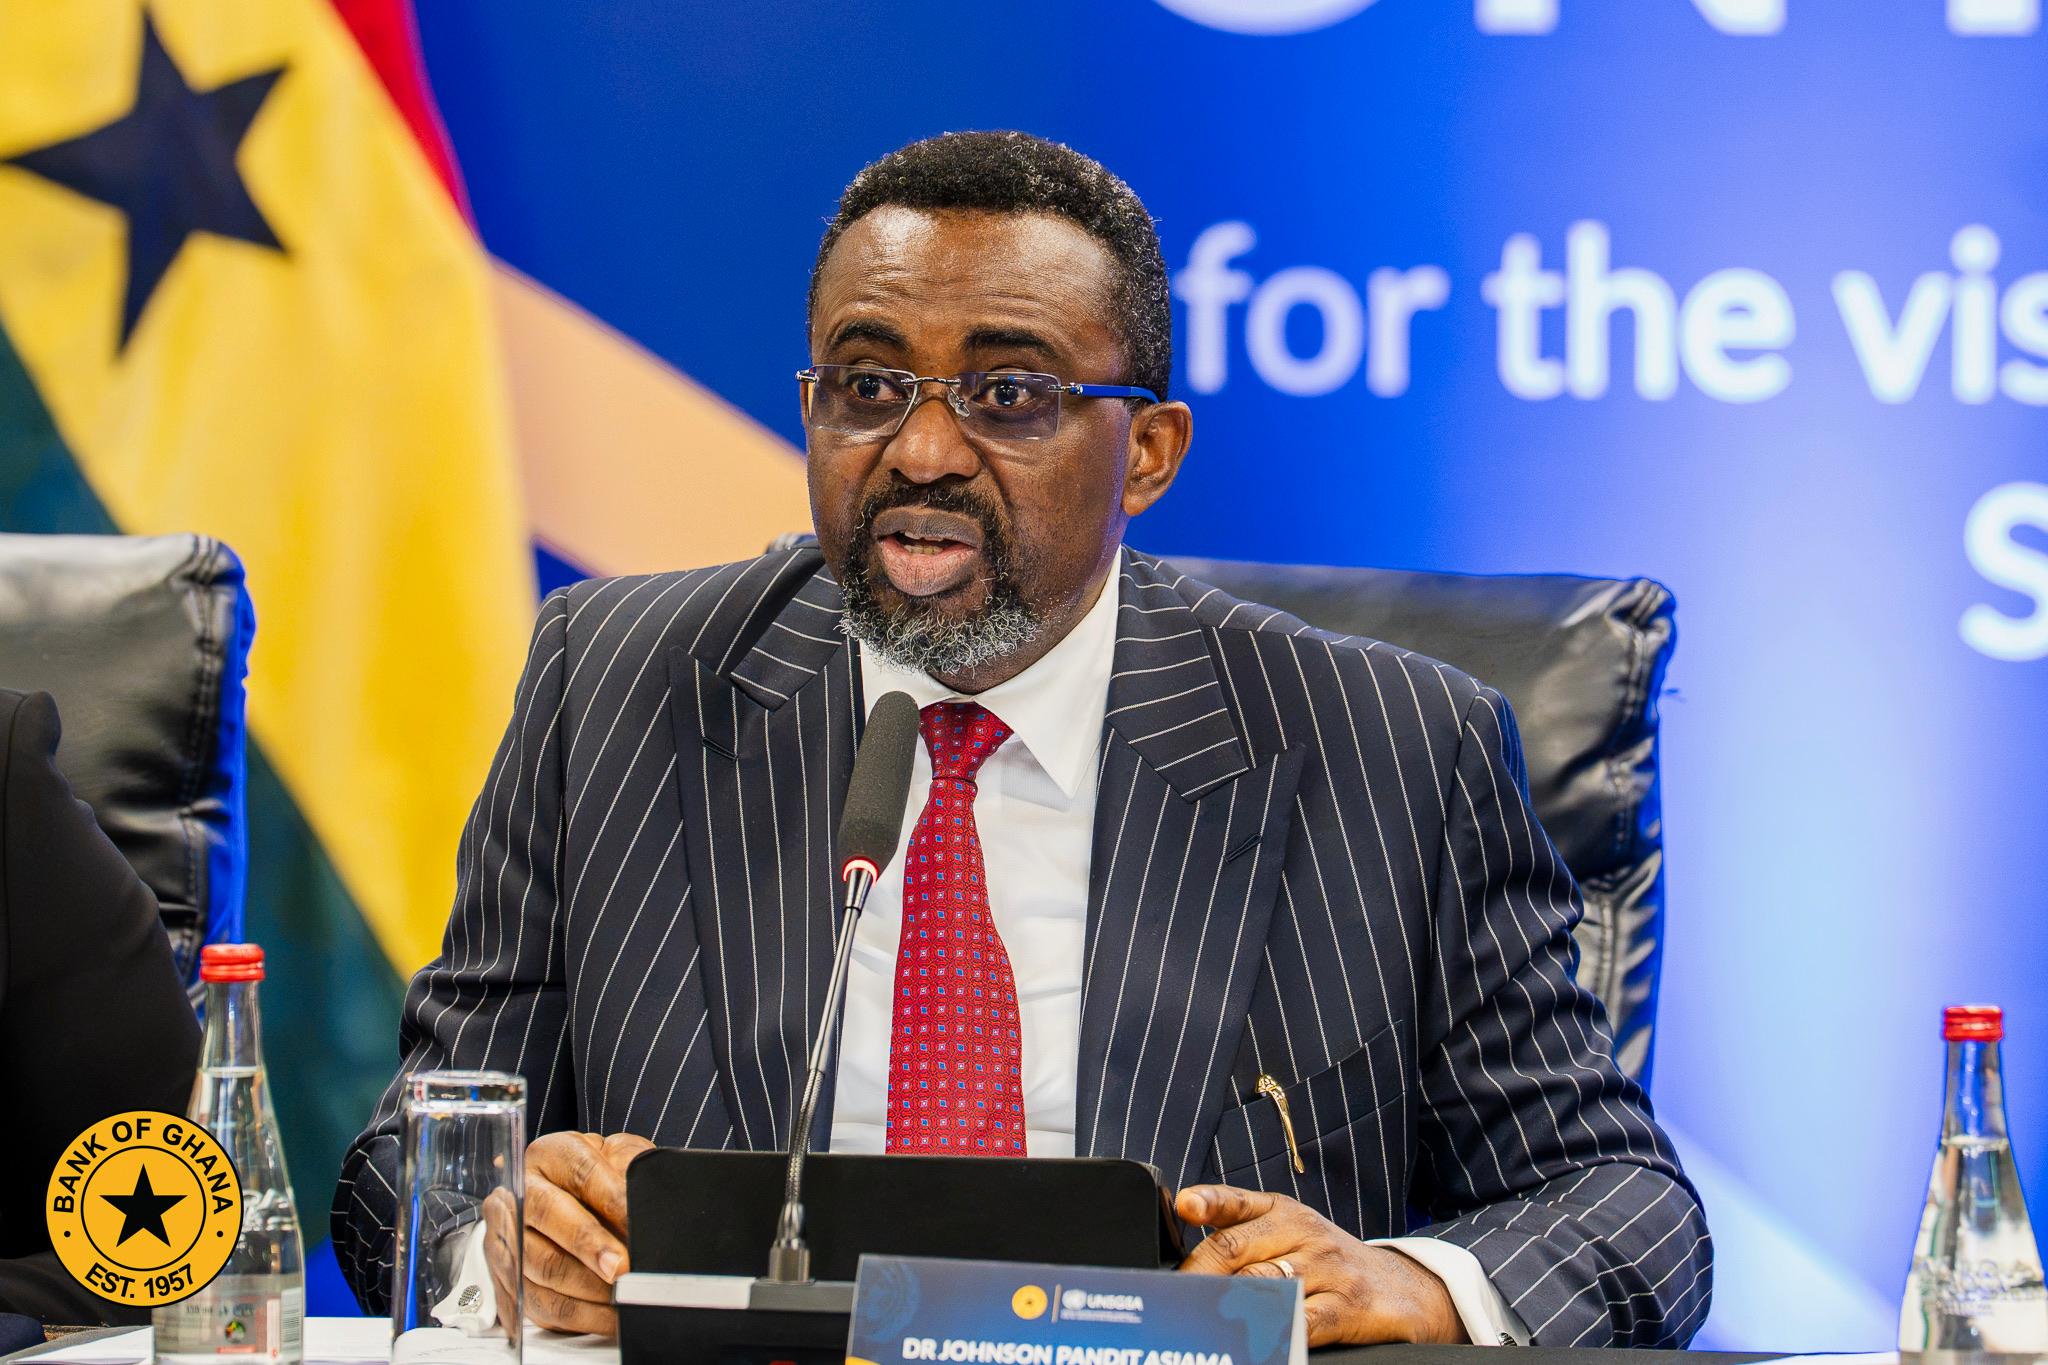

- Technology and Data Key to Fairer Credit for MSMEs, Women and Farmers — BoG Governor
Bank of Ghana Governor Dr Johnson Pandit Asiama has called for Ghana’s financial sector to move beyond expanding access to services and focus on whether households and businesses are becoming more financially secure.
Speaking at a Financial Health Leadership Roundtable in Accra on Wednesday, Dr Asiama said Ghana’s decade of investment in digital infrastructure had made financial services more accessible to millions. The next challenge, he argued, is ensuring those services help people save, manage risk, invest and build resilience.
The meeting was held during the visit of Queen Máxima of the Netherlands, the United Nations Secretary-General’s Special Advocate for Financial Health.
Dr Asiama said Ghana’s financial sector had been transformed by digital payments, mobile money, fintech innovation and regulation that supported growth and trust.
But access alone does not guarantee financial wellbeing. In his address, the Governor pointed to savings, insurance, pensions, investment opportunities and financial literacy as factors that shape financial health. He singled out productive and responsible credit as one of the most important routes to better outcomes in Ghana.
“Credit, when appropriately designed and delivered, enables households to invest in their futures and gives businesses the capital required to grow, innovate and create jobs,” he said.
That distinction matters for a country where digital finance has widened the channels through which people can make payments and interact with financial providers.
The policy question now is whether those channels can also help people build secure financial lives and enable viable businesses to obtain capital on fair and sustainable terms.
Dr Asiama placed micro, small and medium-sized enterprises at the centre of that challenge. He described them as the backbone of economic activity, creating jobs, supporting livelihoods and driving innovation, yet said many continue to face barriers to finance.
“Too often, credit is unavailable to businesses with potential simply because of unfair mechanisms,” he said.
He did not specify which mechanisms he had in mind. But his remarks place pressure on lenders, regulators and policymakers to examine how credit decisions are made, what information is used to assess borrowers and whether viable firms are being excluded from financing.
For smaller businesses, a lack of accessible finance can limit investment in equipment, inventory, technology and expansion. Yet widening credit access cannot mean lending without regard to borrowers’ ability to repay.
Dr Asiama’s emphasis on credit that is both productive and responsible points to a balance: extending finance to underserved businesses while ensuring that loan terms and repayment obligations are sustainable.
The Governor argued that technology, data and innovation could help address the financing gap by broadening access, reducing information asymmetries and creating pathways for viable businesses.
Better information can help lenders understand borrowers who may not fit conventional credit profiles. It can also support more informed decisions about risk and the terms on which financing is provided.
That opportunity will require trust. Digital systems can help make financial services more accessible, but the roundtable’s wider task is to focus on outcomes for people and businesses.
Providers and regulators will need to consider whether innovation is improving access to useful products and enabling customers to make informed financial decisions.
Asiama also urged participants to consider access to productive credit for women and smallholder farmers, alongside MSMEs. Those groups may have distinct financing needs, and a single approach to lending may not serve them equally.
The Governor’s address did not set out a new lending target or announce a specific programme. Instead, he asked the roundtable to identify practical solutions and concrete commitments.
His questions ranged beyond credit. He challenged participants to consider how to strengthen savings, insurance and long-term financial resilience, and how the next generation of financial services could deliver better outcomes.
The breadth of that agenda reflects the difference between being able to use a financial service and having the tools to withstand shocks, plan for the future and invest in opportunity.
The roundtable brought together representatives from financial institutions, regulators, government and development organisations. Asiama said that breadth of participation reflected a growing recognition that improving the financial health of households and businesses requires collective action.
That coordination will be important because no single institution can resolve the barriers to financial health.
Regulators can set rules and promote confidence; financial providers design and deliver products; government shapes the broader economic environment; and development partners can support innovation and evidence-based approaches.
The challenge is to turn dialogue among these actors into practical changes that customers and businesses can feel.
For the Bank of Ghana, the issue also extends the conversation about the role of financial innovation. The Governor’s speech recognised Ghana’s progress in digital finance while directing attention to the quality of outcomes that progress produces.
A strong payments infrastructure is an important foundation, but its value will depend in part on whether it helps people and businesses manage money more securely and access suitable financial products.
The test for the roundtable, therefore, will be whether it can move from broad agreement to clear priorities. That could mean identifying which barriers prevent viable small businesses from obtaining finance, improving how lenders assess borrowers, or strengthening access to savings and insurance products.
The address did not prescribe those steps, but it called on participants to identify barriers and agree on concrete commitments.
“If we leave this room with a clear set of priorities, this Roundtable will have achieved its purpose,” Asiama said.
His challenge is a shift in emphasis for Ghana’s financial sector: from counting how many people can reach financial services to asking whether those services are helping households and businesses become more resilient.
Ghana’s digital finance gains provide a platform. The next measure of progress will be whether that platform supports fairer access to productive credit, stronger financial security and better prospects for the businesses that sustain livelihoods and create jobs.

