


- Weak Governance, Not Only Low Capital, Remains Microfinance’s Central Risk
Ghana’s attempt to rebuild its microfinance sector will succeed only if stronger capital requirements are matched by better governance, effective supervision and meaningful protection for customers whose savings and livelihoods depend on small financial institutions.
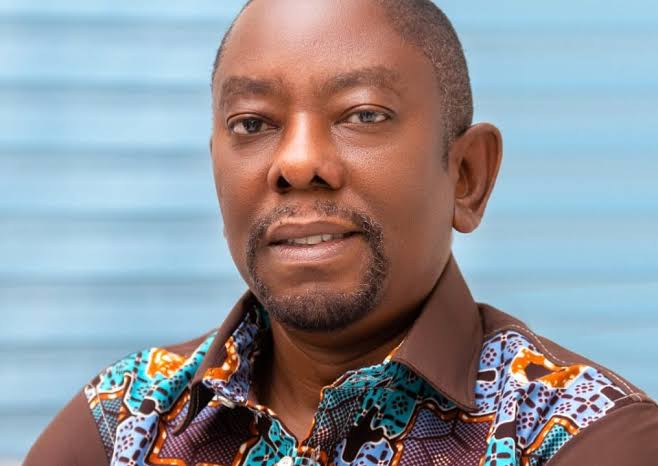
That is the central warning from Reverend Dr Daniel Agbeko, Senior Lecturer and Head of the Department of Multidisciplinary Studies at Ho Technical University, who says the reform programme must extend beyond restructuring institutions to correcting the weaknesses that repeatedly place depositors at risk.
Speaking at the 2026 Annual General Meeting of the Micro-Credit Association Ghana in Ho, Dr Agbeko said the revised Bank of Ghana framework presented an opportunity to strengthen accountability, improve risk management, protect customers, support responsible financial inclusion and promote institutional sustainability.
The policy direction is significant. Microfinance institutions serve traders, farmers, transport operators and small businesses that often lack access to conventional bank credit. When these institutions work properly, they convert small deposits into working capital and bring financial services closer to communities excluded from mainstream banking.
When they fail, however, the consequences are intensely personal. Customers may lose school fees, business capital, medical savings or retirement funds. The damage extends beyond individual institutions because every collapse weakens confidence in other operators, including those that are responsibly managed.
Microfinance failures are frequently presented as capital problems. Insufficient capital matters because it leaves institutions unable to absorb losses. But an institution can meet a minimum-capital requirement and still fail if directors misuse funds, managers lend to connected parties, internal controls are weak or financial reports conceal deterioration.
Dr Agbeko’s emphasis on institutional accountability should consequently be treated as central rather than supplementary to the reforms. Recapitalisation without governance improvement could merely provide poorly controlled institutions with larger amounts of money to place at risk.
The revised framework must therefore ensure that new capital is supported by competent boards, credible management and internal systems capable of identifying risks before they become losses.
Capital requirements can force stronger institutions to consolidate and create buffers against shocks. They cannot, however, substitute for ethical leadership, accurate reporting and proper oversight of how customer funds are invested.
Delegated supervision allows the regulator to assign specified monitoring functions to a competent body under clearly defined standards, reporting obligations and continuing regulatory oversight. It can bring supervisory capacity closer to institutions operating far from Accra.
According to Dr Agbeko, a properly designed system could expand supervisory reach, increase the frequency of monitoring, strengthen early-warning mechanisms and reduce the cost of routine oversight.
That could help the Bank of Ghana identify deteriorating loan portfolios, liquidity pressures, governance disputes or reporting failures before they become threats to depositors. Earlier intervention generally costs less than resolving an institution after it has collapsed.
Yet delegation carries its own risks. A body funded or controlled by the same institutions it supervises may hesitate to sanction influential members. Standards could be applied inconsistently, adverse findings could be softened and serious problems might reach the central bank too late.
Dr Agbeko therefore stressed that delegated supervision depends on clear mandates, competent supervisors, reliable information systems, enforcement power and sustained accountability. Delegation must extend the Bank’s reach, not dilute its responsibility.
The Bank of Ghana should retain authority over licensing, major sanctions and resolution decisions. Delegated bodies should operate under published service standards, conflict-of-interest rules, audit requirements and regular evaluation.
Supervisory reports should follow a standard format and be transmitted to the central bank within specified periods. Material breaches, liquidity shortages and suspected fraud must trigger immediate escalation rather than waiting for routine reporting cycles.
The strongest reform framework will be judged by what customers experience. Protection cannot consist only of warning people to deal with licensed institutions after losses have occurred.
Customers need clear information about interest rates, fees, penalties and the total cost of borrowing. Loan contracts should be written in accessible language, and borrowers should receive explanations before signing rather than discovering charges during repayment.
Institutions must also adopt fair collection practices. Microcredit can support enterprise, but aggressive recovery methods, public humiliation or misuse of personal information can turn financial inclusion into exploitation.
For depositors, protection requires accurate records, restrictions on the use of customer funds and accessible complaint-resolution mechanisms. Customers should know where to report misconduct and how quickly they can expect a response.
The Bank of Ghana and delegated supervisors should publish enforcement outcomes and complaint statistics. Transparency would help customers distinguish licensed, compliant institutions from operators repeatedly violating rules.
Technology introduces another layer of risk. Digital lending and mobile repayments can reduce costs and expand access, but they also create concerns about data privacy, automated credit decisions, fraud and over-indebtedness.
Institutions adopting technology must therefore strengthen cybersecurity and ensure that digital convenience does not remove human accountability. An algorithm should not become an excuse for unexplained rejection, discriminatory pricing or irresponsible lending.
Customer protection must also cover how institutions advertise their products. Claims about low interest rates can be misleading when processing fees, compulsory savings, insurance charges and penalties substantially raise the actual borrowing cost.
Regulators should require providers to disclose a standardised annual percentage rate or comparable total-cost measure. Customers would then be able to compare products across institutions rather than relying on headline rates that conceal additional charges.
The December 31 compliance deadline and new capital requirements have generated concern among industry associations. Stronger rules are necessary, but implementation should recognise that abrupt consolidation could reduce services in communities where alternatives remain limited.
Operators unable to meet the new standards should receive clear options and timelines. Those exiting deposit-taking activities must reconcile customer balances before licences are withdrawn, while viable institutions should be encouraged to merge rather than conceal weaknesses until the deadline.
Supervision should also be risk-based. A small non-deposit-taking lender does not present the same danger as a large institution holding substantial public deposits. Applying identical requirements without regard to business models could raise costs without improving protection.
The regulator must distinguish between institutions that need technical assistance, those capable of merging and those whose governance weaknesses make continued operation unsafe.
This approach would protect financial inclusion without treating every existing licence as entitled to survival. Access to finance is valuable only when the institutions providing it are stable enough to honour their obligations.
MCAG Board Chairman Benjamin Tuckson Jr said the industry’s future depended on embracing reform, investing in people, adopting appropriate technology and maintaining high standards of governance and consumer protection.
“The reputation of the industry is collective,” he said, urging operators to strengthen cooperation with regulators, institutions and the association.
Ghana’s reforms will ultimately be measured not by the number of licences converted or capital declarations submitted, but by whether customers can save, borrow and transact without fearing that weak governance will consume their money.
If delegated supervision becomes rigorous, transparent and accountable, it can close gaps that allowed problems to grow unnoticed. If it becomes a system of industry self-protection, the reforms will reproduce the weaknesses they are intended to correct.
The opportunity is to build a microfinance sector that extends credit without extending instability. For Ghana’s underserved communities, that distinction will determine whether financial inclusion becomes a pathway to resilience or another source of loss.

