


- Fuel Affordability and Supply Take Centre Stage in CBOD Talks With IMF
The Chamber of Bulk Oil Distributors (CBOD) has held discussions with an International Monetary Fund mission on fuel affordability, foreign exchange supply and the effects of Ghana’s petroleum price floor, putting the balance between consumer costs and reliable fuel supply under renewed scrutiny.
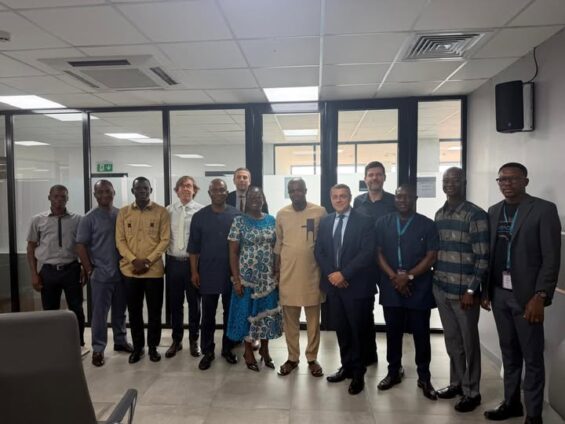
The meeting on October 30 brought together the Ministry of Finance, the IMF, the National Petroleum Authority (NPA) and CBOD. It formed part of the IMF’s first review of Ghana’s Policy Coordination Instrument, a non-financing programme under which the Fund monitors the country’s economic policies.
The discussion covered the sustainability of government interventions introduced in response to rising petroleum prices and the availability of foreign exchange for the downstream sector.
Participants also considered how the floor price policy affects product availability, affordability and the long-term sustainability of supply. No new policy decision or agreement was announced after the engagement.
The issues are closely linked. Ghana relies on imports to meet a significant share of its petroleum product needs, making the cost of foreign exchange and international market prices important to the final cost of supply.
When importers face higher acquisition costs, movements in the cedi, crude prices or refined-product prices can feed into the domestic pricing process. The challenge for policymakers is to manage those pressures without leaving consumers exposed to abrupt price movements or creating conditions that undermine supply.
The price floor adds another layer. For the first half of November, the NPA lowered the petrol floor from GH¢16.09 to GH¢15.39 per litre and the liquefied petroleum gas (LPG) floor from GH¢13.89 to GH¢13.73 per kilogramme.
The diesel floor moved in the opposite direction, rising from GH¢17.09 to GH¢17.41 per litre. These changes show why a single description of fuel affordability can conceal different pressures across products.
Those figures are minimum price floors, not a guarantee of what consumers will pay at the pump. The announced floors exclude certain international trading premiums and operating and marketing margins, which are determined separately under the pricing framework. Actual prices may therefore vary between retailers and may not move by the same amount as the floor.
That distinction makes the design and application of the policy important. A floor can serve as a minimum benchmark for pricing, but its effect on consumers depends on how it compares with the costs and margins that shape final pump prices.
If the floor is binding, it may limit the room for marketers to compete below it; if underlying costs are already higher, the floor may have less influence on the price consumers face. These are policy considerations raised by the issues discussed, not conclusions announced by the meeting.
The latest price changes also underline that relief can be uneven. Petrol users saw the minimum benchmark fall by 70 pesewas per litre, while LPG’s floor declined by 16 pesewas per kilogramme.
Diesel users faced a 32-pesewa increase per litre. The different directions reflect the distinct cost movements behind each product, and mean that affordability measures may benefit some consumers while offering less support to others.
Foreign exchange supply is another critical part of that equation. Bulk distributors need to finance purchases from international suppliers, and the cost of those purchases can be affected by exchange-rate movements.
A reliable supply of foreign currency can help companies plan imports and meet payment obligations; uncertainty can complicate those decisions and, in turn, affect the timing or cost of supply. The meeting’s focus on FX availability signals that fuel pricing cannot be separated from the wider macroeconomic environment.
Government interventions can cushion consumers against sudden price increases, but their sustainability depends on how they are financed, targeted and managed over time. The announcement did not specify which interventions were assessed or provide estimates of their fiscal cost. That leaves important questions open: how much relief reaches consumers, who benefits most, and what happens to supply and public finances if support is extended while international costs remain elevated?
For the IMF review, those questions matter because fuel prices affect more than household budgets. Petroleum costs influence transport, food distribution and the operating expenses of businesses.
At the same time, measures to moderate prices can carry fiscal implications, while insufficient cost recovery may affect importers’ ability to maintain supply. A durable approach would need to account for both the immediate impact on consumers and the financial conditions needed to keep products available.
There is also a trade-off between price stability and market competition. A price floor that is poorly aligned with actual costs could constrain price competition or fail to reflect changing conditions quickly enough.
But prices that do not support sustainable supply could expose the market to funding pressure and uncertainty. Regular review, transparent calculations and clear communication about what the floor includes would help consumers and industry participants understand how the system works.
The IMF meeting provided a forum for the parties to exchange views, but the public account of the engagement did not outline specific proposals from CBOD or responses from the authorities.
Nor did it report any new measures on fuel subsidies, FX provision or price-setting. The significance of the discussion lies in the issues placed before the review, rather than in a policy change already agreed.
CBOD said it remained committed to “constructive stakeholder engagement and policy dialogue” to support a “resilient, efficient and sustainable downstream petroleum sector”.
Turning that commitment into practical results will require more than dialogue: the next steps will need to clarify how government support is assessed, how the floor interacts with retail prices, and how the sector’s foreign exchange needs are addressed.
The central policy test is whether Ghana can protect consumers from damaging price shocks while preserving the financial capacity of importers and distributors to maintain regular supply.
The meeting has put that balance on the agenda. Its value will ultimately be judged by whether the review produces a clearer, more transparent and fiscally sustainable framework for managing fuel costs.

