


- Inflation At 5.00%, Reserves at US$11.07bn: BoG Enters Pivotal September Rate Meeting
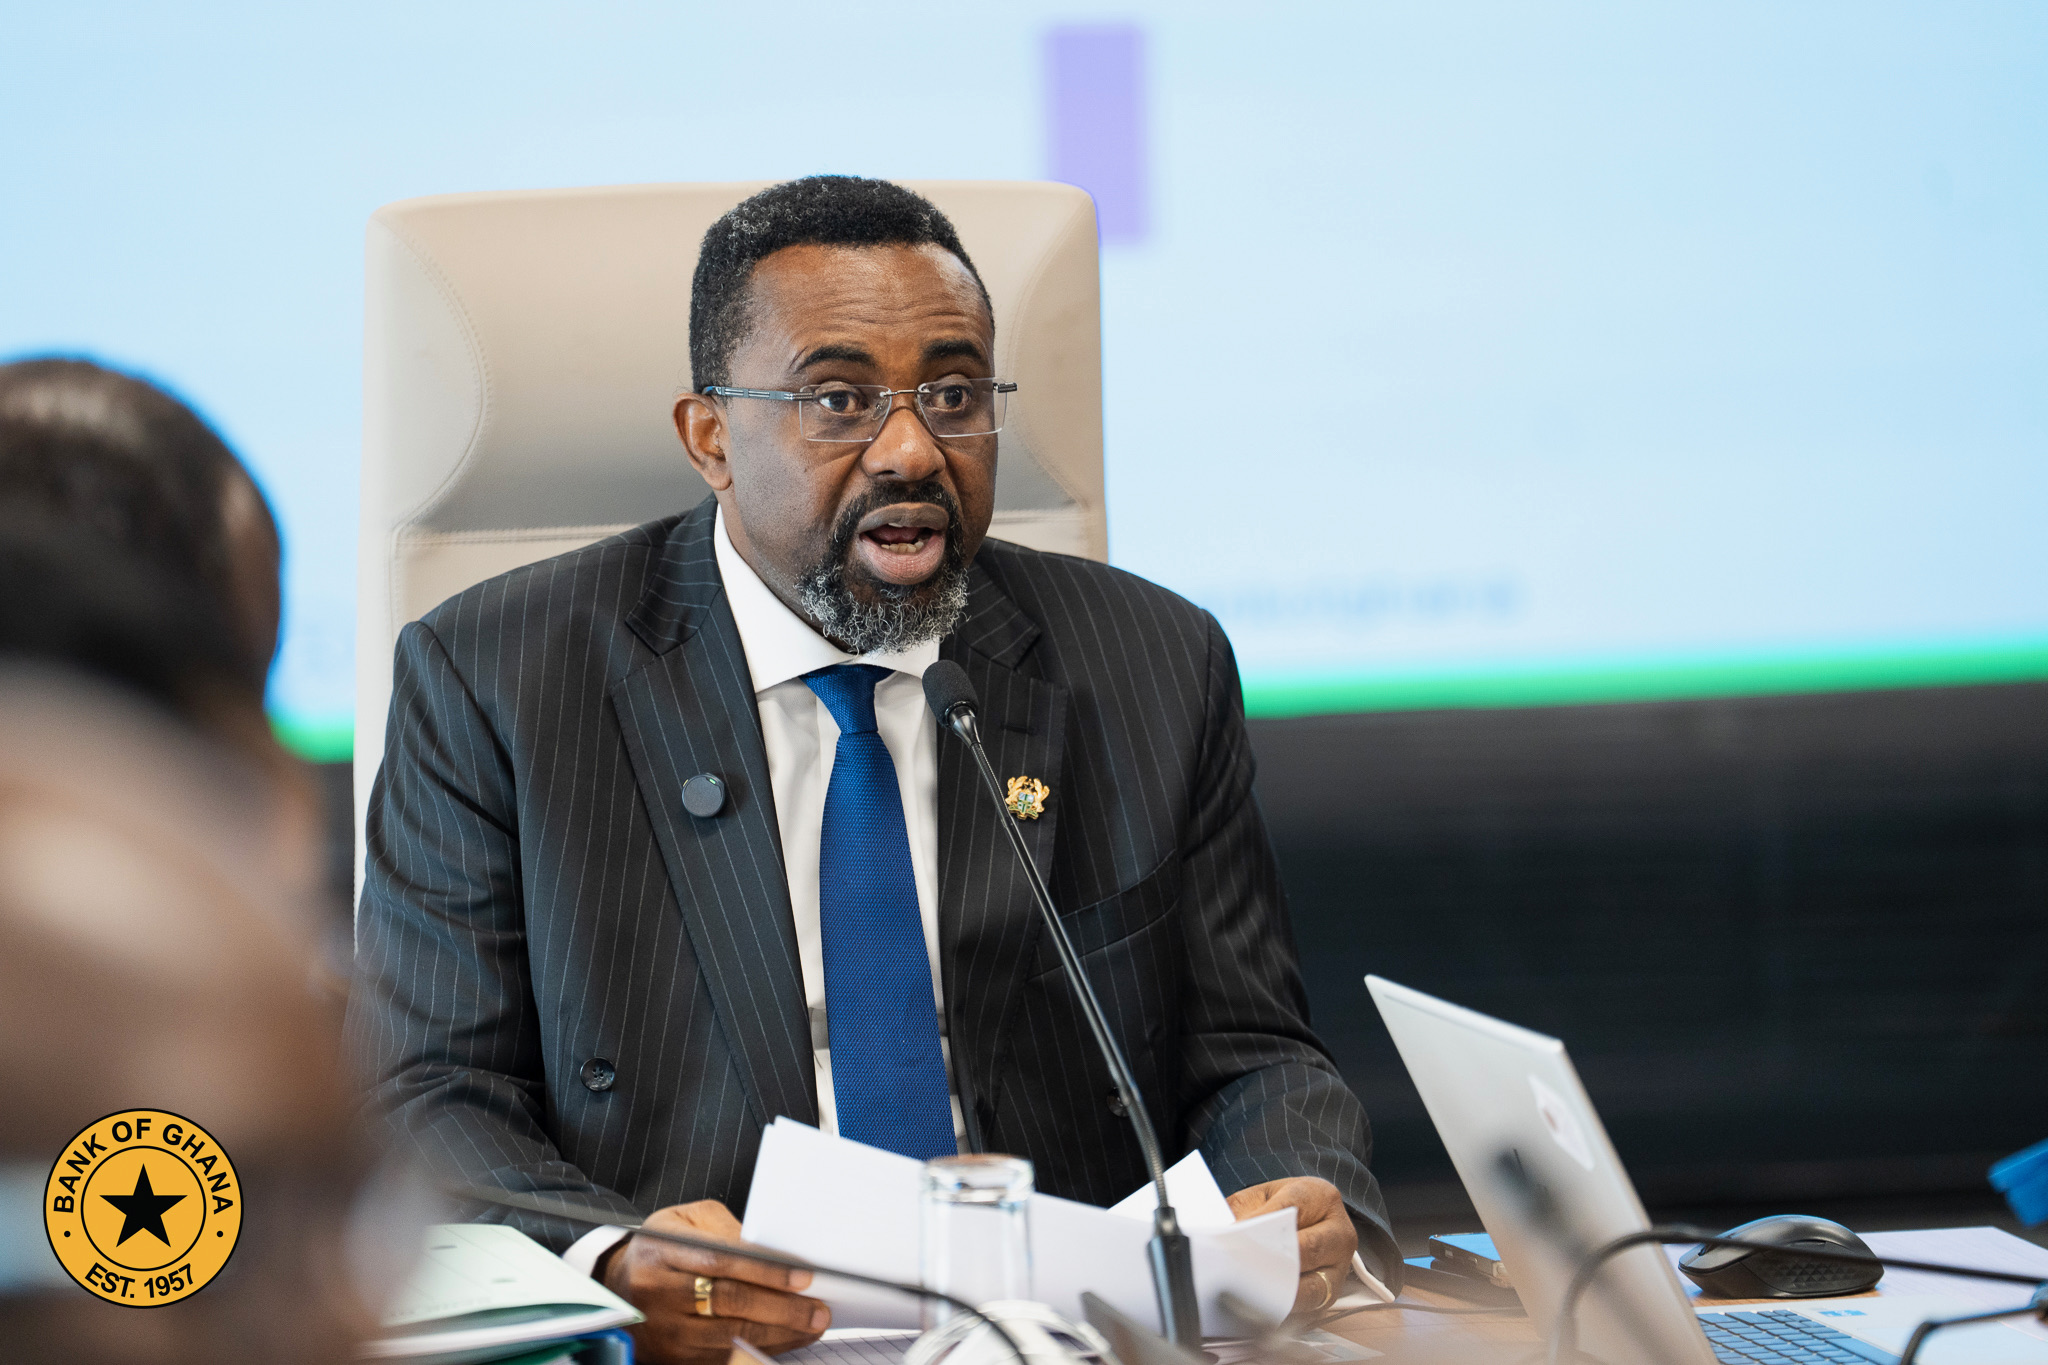
The Bank of Ghana has opened its 132nd Monetary Policy Committee meeting with Governor Dr Johnson Pandit Asiama signalling that the decision over whether to maintain the 14.00% policy rate has become more difficult as domestic inflation begins to rise and Ghana’s external buffers weaken.
The meeting, which began on September 23, is the first held under Ghana’s new 36-month Policy Coordination Instrument with the International Monetary Fund, placing additional emphasis on policy credibility after the country’s transition from crisis stabilisation.
Dr Asiama said the central question is whether the balance of risks has shifted sufficiently to justify a different monetary response or whether the current rate should remain unchanged.
The MPC unanimously maintained the policy rate at 14.00% at its July meeting, giving the central bank more time to assess the transmission of previous policy decisions and the economic impact of the Middle East conflict.
Two months later, Dr Asiama said banks were still reallocating resources following changes to the cash reserve ratio regime, while geopolitical risks had not dissipated.
The Bank of Ghana’s published opening remarks confirm that the current meeting is expected to reassess whether those developments have altered the appropriate monetary-policy stance.
Headline inflation stood at 5.00% in August, remaining below the lower boundary of the Bank’s 8.00% ±2 percentage-point target band, but the direction has changed materially since inflation reached 3.20% in March.
That represents a cumulative increase of 1.80 percentage points in five months, raising the question of whether the recent movement is temporary or the beginning of more persistent price pressure.
Dr Asiama said the Committee would need to determine whether expected increases over the coming months simply reflect higher energy prices and administered tariffs or could begin to unsettle inflation expectations.
The distinction is important because monetary policy normally responds differently to a one-off supply shock than to a broadening and persistent inflation process.
The Bank’s present policy rate therefore sits against an unusual backdrop in which inflation remains below target even as the underlying direction of travel has become less favourable.
Global developments have made that judgment more complicated. The Governor said the Middle East crisis had entered its seventh month, with renewed hostilities involving the United States and Iran disrupting trade through the Strait of Hormuz and attacks on Saudi oil infrastructure affecting alternative export routes.
Brent crude, which was above US$85 per barrel at the July MPC meeting, had climbed to about US$107 per barrel last week, increasing the risk that higher fuel and agricultural-input costs could feed into inflation in Ghana.
The shock is not entirely negative for Ghana because higher gold prices can strengthen export earnings, reserves and government revenues.
But the benefit is being offset by higher energy and fertiliser import costs, which can move rapidly through transportation, agricultural production and consumer prices.
Dr Asiama described the global shock as “double-edged”, requiring the Committee to judge which side of that equation is likely to dominate Ghana’s inflation and growth outlook.
The domestic economy nevertheless continues to provide the MPC with some room to manoeuvre.
Real GDP expanded 6.00% in the second quarter, led by services and information and communications technology, while private-sector credit accelerated sharply and the fiscal position performed better than programmed.
The Governor also cited a primary surplus above target, public debt at 45.00% of GDP, ratings upgrades and a banking sector he described as sound, liquid and profitable.
The more difficult signal is coming from the external sector. Gross international reserves declined to US$11.07bn, equivalent to 4.20 months of import cover, while the current account is projected to move into deficit in the third quarter as gold shipments slow and service payments increase.
“The domestic position affords policy space; the external position determines how much of it can safely be used,” Dr Asiama said, placing reserve rebuilding at the centre of the Bank’s priorities heading into the fourth quarter.
That external weakness could weigh heavily against any argument for aggressive monetary easing.
Lower policy rates can support domestic credit and activity, but if financial conditions loosen too quickly when foreign-exchange buffers are weakening, additional liquidity can place pressure on the currency and eventually feed back into imported inflation.
The Bank has already identified weaker reserves, a deteriorating current account and the pause in GoldBod gold exports since mid-August as risks that require close attention ahead of the usual increase in foreign-exchange demand towards year-end.
Fiscal developments represent the third major risk identified by the Governor. Government spending is expected to increase over the remainder of the year, the share of short-term domestic debt is rising and completion of external debt restructuring will raise debt-service obligations.
Each of those developments has implications for domestic liquidity and the exchange rate, meaning the MPC must assess monetary policy not in isolation but against the likely fiscal impulse entering the final quarter.
The meeting also has institutional importance because it is the first under the IMF’s Policy Coordination Instrument, approved by the Fund’s Executive Board on July 27.
Dr Asiama described the arrangement as marking Ghana’s movement from crisis stabilisation into a consolidation phase and said financial markets would judge both fiscal and monetary authorities on the credibility of their policy choices.
With the first PCI review approaching in October, the Governor said the Bank needed to demonstrate the same policy discipline that characterised the previous IMF-supported programme.
The September meeting therefore presents the MPC with a finely balanced choice. Inflation at 5.00% remains comfortably below the Bank’s target band and economic activity is relatively strong, conditions that ordinarily provide room for monetary support, but rising oil prices, weaker reserves, increasing fiscal pressures and renewed cedi vulnerability argue for caution.
The Bank of Ghana’s official website continues to show the current policy rate at 14.00%, with the next decision now hinging on whether the Committee believes preserving external stability outweighs the case for using the domestic policy space that lower inflation has creted.

