


- NPRA Demands Caution as Pension Capital Enters Ghana’s Cocoa Financing Market
Ghana’s GH¢16.3 billion cocoa financing programme has opened a channel between domestic savings and productive investment, but the National Pensions Regulatory Authority is warning that pension funds must not allow ambition to override their duty to protect workers’ retirement assets.
The intervention places a boundary around the enthusiasm generated by Cocoa Capital PLC’s inaugural commercial paper. The transaction demonstrates that Ghana’s capital market can mobilise billions of cedis for a strategic export industry. It tests whether trustees and fund managers can distinguish national economic importance from investment suitability.
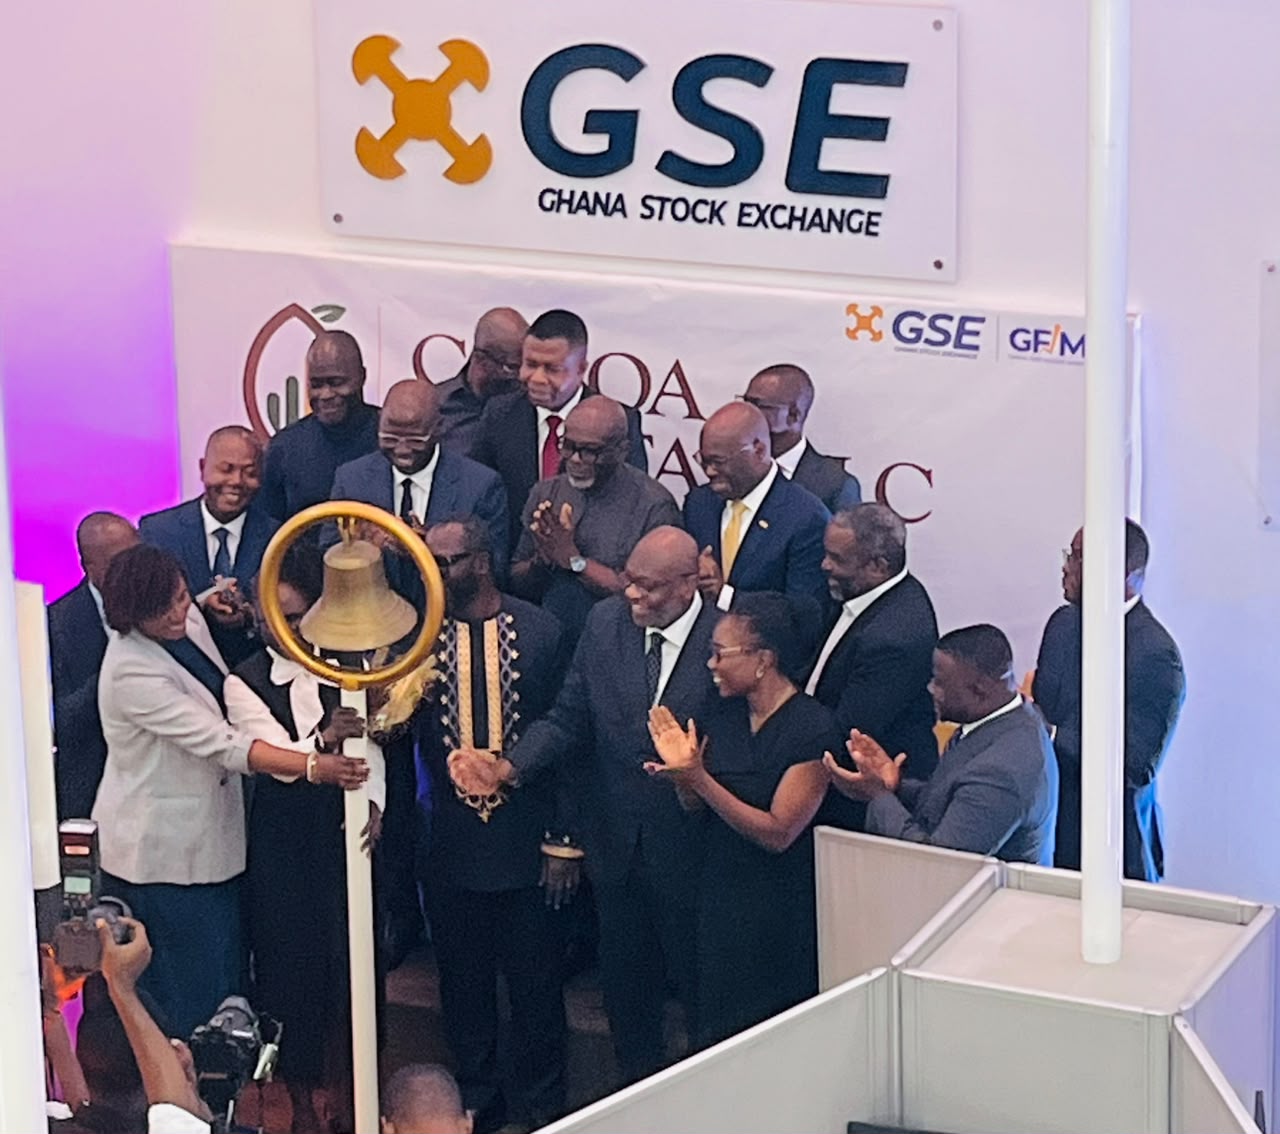
Philemon Laar, Director of Planning, Research, Monitoring and Evaluation at the NPRA, delivered the authority’s message when Cocoa Capital’s Series 1, Tranche 1 commercial paper was admitted to the Ghana Fixed Income Market on October 14, 2026.
The programme comprises GH¢14 billion in commercial paper and GH¢2.3 billion in bonds. Its purpose is to mobilise domestic capital for cocoa purchases and create an investable asset for institutions that manage pools of savings.
The inaugural issuance raised about GH¢3.39 billion after attracting approximately GH¢3.59 billion in demand. The 266-day paper carries an annual interest rate of 11 per cent and matures on June 28, 2027.
For pension schemes, however, demand from other investors cannot replace independent analysis. A security may be oversubscribed and still carry risks that are unsuitable for a particular fund’s liabilities, liquidity position or exposure limits.
That is the central meaning of the NPRA’s call for stronger investment discipline, regulatory compliance and transparency. Pension trustees do not invest their own money. They manage deferred income belonging to workers who may depend on those accumulated savings decades later.
Their first responsibility is therefore fiduciary rather than patriotic. Pension capital can help finance agriculture, housing, infrastructure and corporate expansion, but each allocation must be justified by expected return, credit quality, diversification and the probability that the investment will be repaid when required.
Cocoa Capital’s structure includes safeguards intended to improve that assessment. Repayment is supported by receivables from cocoa forward-sales contracts, with collections directed through ring-fenced accounts.
In principle, this creates a visible cash-flow pathway connecting export proceeds to debt-service obligations. Ring-fenced accounts can reduce the danger that money intended for investors is diverted towards unrelated expenditure or absorbed by competing operational demands.
Yet ring-fencing cannot manufacture cocoa beans, guarantee export volumes or prevent market disruption. The underlying receivables remain exposed to production shortfalls, crop disease, ageing farms, climate pressures, international price movements and operational execution.
Forward sales may improve revenue visibility, but the ultimate strength of the security still depends on whether contracted cocoa is produced, delivered and paid for. Pension investors must therefore evaluate the economic substance behind the structure rather than relying only on its legal architecture.
Liquidity presents another consideration. The commercial paper matures within 266 days, which may appear compatible with short-term portfolio management. But the ability to hold an instrument until maturity is different from the ability to sell it quickly without accepting a substantial discount.
Fund managers must determine whether an active secondary market exists and whether their schemes could meet benefit payments or portfolio obligations if trading conditions became difficult before June 2027.
Concentration risk is equally important. The inaugural issuance alone raised nearly GH¢3.4 billion, while the full programme is almost five times larger. If pension funds become major buyers across successive tranches, their exposure to one issuer, one commodity and one financing model could rise rapidly.
Ghana’s domestic debt restructuring gives the NPRA’s warning additional force. The episode demonstrated that instruments treated as dependable can be altered when fiscal or financial pressures intensify. It also showed how correlated exposures can transmit one borrower’s difficulties across banks, insurers, pension funds and households.
Cocoa Capital is not automatically comparable to government debt, and its receivables-based structure offers different protections. Nevertheless, the broader lesson remains applicable: yield must be assessed alongside the possibility of delayed payment, restructuring or loss.
An 11 per cent annual return cannot be considered attractive in isolation. Trustees must examine inflation expectations, alternative investments, credit risk, transaction costs and the duration of the commitment. The relevant question is not simply how much the paper pays, but whether that return adequately compensates contributors for every risk assumed.
Transparency will determine whether investors can answer that question throughout the instrument’s life. Cocoa Capital should provide timely information on funds deployed, cocoa purchased, forward contracts supporting repayment, collections entering ring-fenced accounts and the coverage available for upcoming obligations.
Disclosure cannot end once the money has been raised. Pension funds require continuing evidence that assumptions made at issuance remain valid and that emerging risks are identified early enough for trustees to respond.
The NPRA must also avoid becoming a passive observer. Clear exposure limits, consistent valuation rules, stress testing and enforcement will be necessary if pension participation expands. Regulation should protect contributors without preventing funds from accessing well-structured opportunities capable of improving long-term returns.
This balance matters for Ghana’s development. The pension industry offers a pool of domestic capital that could reduce dependence on foreign borrowing, deepen the fixed-income market and provide financing tailored to local economic priorities.
But mobilising domestic savings does not make financing cheaper if governance failures eventually impose losses on contributors. Nor should pension funds become a convenient source of capital for projects that cannot meet commercial standards elsewhere.
Cocoa Capital’s first issuance has proved that demand exists. Its maturity in June 2027 will test repayment execution, reporting quality and the credibility of its safeguards.
Successful repayment could strengthen confidence, broaden the market and encourage managed pension participation in productive assets. Failure would damage more than one programme: it could make trustees reluctant to support future agricultural or corporate issuances.
The NPRA’s position is therefore not opposition to development finance. It is a reminder that sustainable development cannot be built by weakening the protections surrounding retirement income.
Ghana can use pension capital to finance economic transformation, but only if every transaction respects the purpose for which those savings exist. Cocoa may be nationally strategic; contributors’ retirement security is no less so.

